
Mortgage Brokers in Clackmannanshire can help turn the question “how much can I borrow?” into the more valuable question: “what kind of home and mortgage can I comfortably live with?”
A mortgage is ultimately a financial agreement, but it usually stems from something more human: security, independence, a larger home, a different way of life, or simply the confidence of knowing where you belong.
Clackmannanshire may be Scotland’s smallest county, yet its housing market is remarkably varied. Alloa provides the area’s principal urban centre, while Tullibody, Sauchie, Clackmannan, Alva, Menstrie, Tillicoultry and Dollar each offer a different mix of housing, transport, heritage and surroundings. The Ochil Hills shape much of the landscape to the north, while connections towards Stirling, Fife, Falkirk and the wider Central Belt can influence where buyers decide to live.
Connect Experts lets you compare advisers by location, expertise, and communication preferences, rather than assuming the nearest adviser is automatically the most suitable.
Whether you are buying your first property, moving home, reviewing an existing mortgage, or considering an investment, the goal is the same: find an adviser whose experience fits both the borrower and the property.
Clackmannanshire Property Market: What Buyers Should Know
Price tells you what a property costs. It doesn’t always tell you what a lender will think.
The latest ONS housing data for Clackmannanshire shows the average house price was £171,000 in August 2026, provisionally about the same as a year earlier.
Average prices by property type were:
- Detached: £321,000
- Semi-detached: £190,000
- Terraced: £146,000
- Flats and maisonettes: £95,000
First-time buyers paid an average of £135,000, while mortgage buyers averaged £176,000. These are county-wide averages, not valuations for individual homes.
That distinction matters in Clackmannanshire.
A flat in Alloa, an established family home in Tullibody, a traditional property in Alva, a stone-built home in Dollar or a more rural property towards Muckhart may raise very different questions about condition, construction, valuation and future marketability.
The county also has seven conservation areas: Old Alloa, Alloa Glebe, Clackmannan, Dollar, Kennet, Pool of Muckhart and Tillicoultry. Conservation status does not prevent a property from being mortgaged, but alterations, condition, listed features, and future maintenance may warrant closer attention.
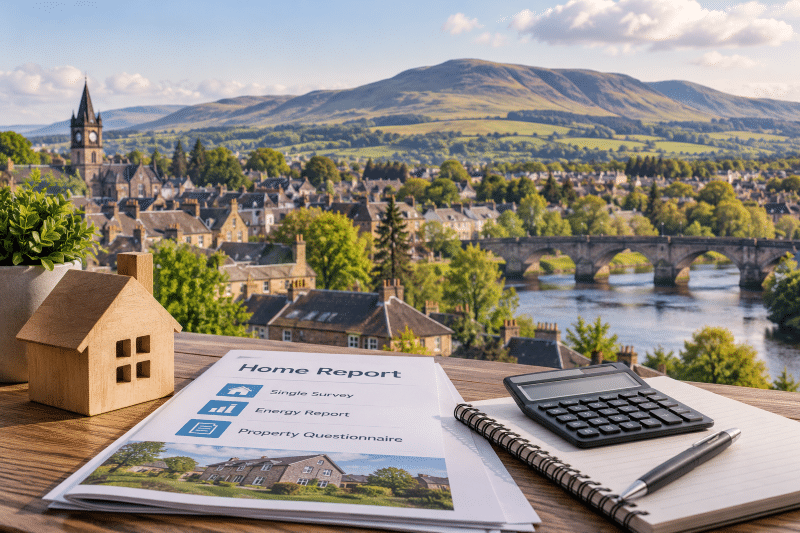
Scotland also has a different property-purchase process from England and Wales. Sellers will normally provide a Home Report, containing a Single Survey, Energy Report and Property Questionnaire. Buyers should read it carefully rather than concentrating only on the asking price.
Where an offer exceeds the valuation accepted by the mortgage lender, the buyer may need to fund the difference from their own resources.
A strong mortgage decision therefore begins before the application. It starts with understanding exactly what you’re buying.
Choosing Mortgage Brokers in Clackmannanshire
Good advice should reduce uncertainty, not replace one uncertainty with another.
When comparing Mortgage Brokers in Clackmannanshire, consider asking:
- Which lenders can you consider?
- Have you advised on properties like the one I intend to buy?
- How do you assess self-employed, variable or complex income?
- What adviser fee could I pay, and when?
- Are there lender, valuation, legal or product fees to consider?
- Can you help before I submit an application?
- How will you communicate during the mortgage process?
- Can appointments take place by telephone, video or face to face?
- What happens if the first lender does not accept the case?
- Do you also provide appropriate protection advice?
Regulation should also form part of your checks.
Use the FCA Financial Services Register to confirm that the firm or individual you are dealing with appears on the Register and that the firm’s permissions match the activity being provided.
No adviser can guarantee mortgage approval. Their value lies in helping you understand the criteria, risks, costs and available routes before unnecessary commitments are made.
Mortgage Advice Across Clackmannanshire
Different properties can require different conversations with a lender.
A straightforward modern home may fit widely used lending criteria. An older stone property, converted building, flat above commercial premises, house requiring substantial repairs or rural property with additional land may need closer assessment.
A mortgage adviser may be able to help with:
- first-time buyer affordability and deposits;
- residential home moves;
- remortgaging;
- self-employed and company-director income;
- variable earnings, bonuses or overtime;
- buy-to-let;
- adverse credit;
- larger mortgage requirements;
- later-life borrowing;
- unusual or older property types;
- protection alongside mortgage borrowing.
Clackmannanshire’s housing stock cannot sensibly be treated as one uniform market.
Alloa has flats, terraces, traditional housing and newer residential areas. Clackmannan has a historic core. Alva, Menstrie and Tillicoultry sit along the Hillfoots, while Dollar combines traditional housing, larger homes and a distinctive historic environment.
That is why choosing an adviser with relevant experience can matter as much as choosing one by geography.
Specialist Fiance
A mortgage decision sits at the meeting point between present circumstances and future plans.
Before choosing an adviser, think about three questions:
- What sort of property am I trying to finance?
- What makes my income or financial position straightforward or unusual?
- What commitments must remain affordable after the mortgage completes?
Answering these questions first can make your search for Mortgage Brokers in Clackmannanshire considerably more useful.
Education
A postcode can influence far more than travel time.
Clackmannanshire Council operates school catchment areas for primary schools, and pupils normally transfer to the associated secondary school based on their home address. Families planning a move should therefore check the relevant catchment rather than assuming that proximity guarantees admission.
The area also includes Dollar Academy, an independent school located in Dollar.
Where independent-school expenditure forms part of a household’s plans, school fees, transport, uniforms and other education costs should be considered alongside mortgage affordability rather than treated as an entirely separate decision.
Homeowners exploring how longer-term education expenditure might interact with property equity or secured borrowing can read Connect Mortgages’ Education Finance guide.
Financial planning isn’t simply about making today’s payment affordable. It is to leave enough room for tomorrow’s commitments as well.
Finance
Mortgage affordability starts with income, but it rarely ends there.
A lender may consider:
- basic salary;
- overtime;
- bonuses;
- commission;
- self-employed profits;
- dividends;
- retained company profit where permitted;
- pension income;
- rental income;
- existing borrowing;
- childcare;
- maintenance commitments;
- credit cards and loans;
- deposit source;
- loan-to-value.
Property type then adds another layer.
A lender prepared to accept the borrower’s income still needs to be satisfied with the property offered as security.
This is especially true for older homes, unusual construction, properties needing significant repairs, or homes where a survey flags issues that need further investigation.
The lowest advertised rate is therefore not always the most meaningful starting point.
Eligibility comes first.
Protecting the Mortgage and the Household
A mortgage can last for decades. Life rarely stays the same for that long.
When arranging borrowing, households may want to consider what would happen if illness, injury, death, or a prolonged loss of income made the monthly commitment harder to maintain.
Depending on individual circumstances, discussions may include:
- life insurance;
- critical illness cover;
- income protection;
- mortgage-related protection.
The appropriate type and level of cover depends on personal circumstances, existing workplace benefits, savings, dependants, mortgage commitments and budget.
Connect Experts has a dedicated guide to Protection Mortgage Brokers for people who want to understand this part of the mortgage journey in more detail.
Protection does not make uncertainty disappear. It is about deciding which financial risks you do not want your household to carry alone.
Specialist Mortgage Considerations in Clackmannanshire
Not every mortgage requirement fits neatly inside a standard affordability calculator.
A borrower may have substantial assets but irregular income. Another may be approaching retirement. Someone else may own several properties, receive income from a company or want to finance a property that requires specialist underwriting.
The purpose of specialist advice is not to make borrowing more complicated. It is to stop genuine complexity from being treated as though it were simple.
Later-Life Mortgage Choices in Clackmannanshire
Later life can change the purpose of borrowing.
Some homeowners may be approaching the end of an existing mortgage. Others may wish to move, reduce monthly commitments, help family members or release funds from property.
Possible discussions can include:
- conventional remortgaging;
- mortgages extending into retirement;
- retirement interest-only mortgages;
- downsizing;
- later-life lending;
- equity release.
Equity release requires specialist advice and should not be viewed simply as a method of accessing cash.
It may affect the value of an estate, inheritance, future flexibility and entitlement to means-tested benefits. Interest may also roll up depending on the product.
Homeowners considering this area can first read the Connect Experts Equity Release Mortgage Guide before discussing their circumstances with an appropriately qualified specialist.
The question in later life is rarely only, “Can I borrow?”
It is also, “What will this decision mean several years from now?”
High-Net-Worth
Clackmannanshire should not be characterised as uniformly high value. The ONS average house price of £171,000 demonstrates why that would be misleading.
However, the county also includes larger detached properties, substantial homes around locations such as Dollar and individual rural properties where borrowing requirements may be materially higher than the county average.
Complexity can also come from the borrower rather than the property.
Examples may include:
- directors retaining profits within a company;
- substantial bonuses;
- partnership income;
- investment income;
- multiple properties;
- foreign-currency earnings;
- significant assets alongside comparatively modest taxable income.
Borrowers in these circumstances can explore High-Net-Worth Mortgage Brokers.
When larger borrowing increases financial dependence on income or assets, clients may also want to explore High-Net-Worth Protection Services.
Wealth can strengthen a financial position. It does not always make that position easier for a standard underwriting system to understand.
Find Mortgage Brokers Across Clackmannanshire
Mortgage Broker in Glenochil Village: Plan With Confidence
Devonside Mortgage Advice: Ask Better Questions Before You Commit
Expert Advice in Forestmill: Answers to Question Before You Sign
Mortgage Broker in Kennet: Make Every Detail Count
Cambus Mortgage Advice: Let the Property Shape the Plan
Fishcross Mortgage Advice: Old Roots, Smarter Next Steps
Muckhart Mortgage Advice: Make Your Next Move Count
Mortgage Broker in Coalsnaughton: Confidence Starts With Context
Mortgage Broker in Dollar FK14: Make Property Detail Count
Mortgage Broker in Menstrie: Build Confidence Before You Buy
Clackmannan Mortgage Advice: Build on the Right Foundation
Mortgage Broker in Alva: Make Your Hillfoots Move Count
People Also Browse these Counties
A Mortgage Network for Advisers Serving Clackmannanshire
Finding the right client and the right adviser are two sides of the same idea: better connections lead to better conversations.
If you are an FCA-authorised mortgage adviser serving Clackmannanshire or clients elsewhere in Scotland, Connect for Intermediaries provides a route for brokers interested in joining the Connect network.
Explore the Connect mortgage network proposition.
The Connect proposition is designed for advisers who want network support while remaining focused on compliant, client-centred advice.
Connect Experts is a mortgage adviser directory and matching platform. Users can search for FCA-authorised mortgage advisers by location, specialism and personal preference. Mortgage advice is provided by the adviser or firm selected.
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us
Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.