
Mortgage Broker in Bridgend – Find a Mortgage Adviser

Mortgage Broker in Bridgend: A mortgage search in Bridgend starts with numbers, but the right decision depends on more than the interest rate. Property value, deposit, income, credit commitments, mortgage term and lender criteria can all change the products available to a borrower. Connect Experts helps you find a mortgage broker in Bridgend who can assess […]
Mortgage Broker in Port Talbot – Find the Right Adviser

Finding a mortgage broker in Port Talbot is not simply a question of choosing the adviser who is geographically closest to you. The more useful question is whether an adviser understands your mortgage requirements, communicates clearly and can research lenders whose criteria may suit your circumstances. Connect Experts helps people in Port Talbot search and […]
Mortgage Broker in Barry – Find a Mortgage Adviser

Mortgage Broker in Barry: A mortgage is ultimately a calculation about the future. The property has a price today, but the decision spans years of income, repayments, interest, and changing circumstances. If you are looking for a mortgage broker in Barry, Connect Experts helps you find mortgage advisers who can discuss those calculations with you […]
Mortgage Broker in Flackwell Heath HP10 – Find an Adviser

Looking for a mortgage broker in Flackwell Heath? Connect Experts is a mortgage adviser directory that helps you search for advisers who cover Flackwell Heath and the wider Buckinghamshire area. You can compare advisers by mortgage expertise, language and other preferences before deciding who you would like to contact. Flackwell Heath sits within Buckinghamshire and […]
Mortgage Broker in Great Missenden HP16 – Find an Adviser

A mortgage in Great Missenden can involve considerably more than comparing interest rates. Property value, deposit size, income structure, loan-to-value ratio, valuation, and the type of home being purchased can all influence which lenders are appropriate. Great Missenden and the wider HP16 area have a varied housing market, including established family homes, period properties, rural […]
Mortgage Broker in Gerrards Cross SL9 – Find an Adviser

Mortgage Broker in Gerrards Cross: A mortgage on a Gerrards Cross property is ultimately a calculation based on more than the property’s price. It connects the value of the home today with income, assets, deposit, borrowing capacity and financial commitments extending years into the future. That relationship becomes particularly important in Gerrards Cross, SL9, where property […]
Mortgage Broker in Bourne End SL8 – Find an Adviser

Mortgage Broker in Bourne End: Bourne End’s property market creates a particular mortgage question: does the mortgage fit both the borrower and the property being purchased? That distinction matters in SL8. Bourne End sits within Buckinghamshire and includes a mixture of established family homes, flats, riverside property and higher-value detached housing. For buyers, existing homeowners and […]
Mortgage Broker in Hazlemere HP15 – Find an Adviser

Mortgage Broker in Hazlemere: A mortgage search in Hazlemere starts with a property, but the lending decision starts with the numbers. Property value, deposit, income, existing commitments, credit history and loan-to-value can all influence which mortgage lenders may consider an application. The property itself also matters. Construction, condition, tenure and valuation can affect the final lending […]
Mortgage Broker in Princes Risborough HP27

Finding a mortgage broker in Princes Risborough is not simply a question of finding the nearest adviser. The useful question is whether the adviser understands your borrowing position, the property you want to finance and the lender criteria that could determine whether an application succeeds. Princes Risborough is a Buckinghamshire market within the HP27 postcode […]
Mortgage Broker in Bletchley MK2 – Find a Mortgage Adviser

Finding a mortgage broker in Bletchley begins with more than searching for the nearest name. A mortgage adviser needs to understand the financial circumstances behind your application, the type of property involved and the lending criteria that may apply. Someone buying their first home in Central Bletchley may therefore need different expertise from a landlord refinancing […]
Mortgage Broker in Beaconsfield HP9 – Find an Adviser

Mortgage Broker in Beaconsfield: A property’s price tells only part of its mortgage story. In Beaconsfield, the relationship between property value, income, deposit, liquidity and long-term plans can be especially important. Beaconsfield sits within the HP9 postcode area of Buckinghamshire and has a distinctly high-value residential property market. Buyers may therefore encounter mortgage requirements that go […]
Mortgage Broker in Chesham – Find a Mortgage Adviser

Finding a mortgage broker in Chesham is partly about finding a mortgage and partly about finding an adviser whose experience fits the way you intend to buy, own or refinance a property. Chesham sits in Buckinghamshire and is primarily covered by the HP5 postcode area. Property values, deposit size, income structure, credit commitments, and the […]
Mortgage Broker in Marlow SL7 – Find an Adviser

Find a Mortgage Broker in Marlow: A mortgage decision in Marlow can involve considerably more than comparing headline interest rates. Property value, deposit size, income structure, affordability, property type and lender criteria can all determine which mortgage routes are realistically available. Connect Experts helps people in Marlow, Buckinghamshire and the SL7 postcode area search for mortgage […]
Mortgage Broker in Amersham – Find the Right Adviser

Finding a mortgage broker in Amersham is not simply a search for somebody nearby. The practical question is whether the adviser understands how lenders may assess your income, deposits, property, borrowing capacity, and long-term plans. Amersham sits within one of the more valuable housing markets in Buckinghamshire. In May 2026, the average Buckinghamshire property price […]
Mortgage Broker in Aylesbury

Finding a mortgage broker in Aylesbury starts with something more important than simply finding the nearest person. The aim is to find an adviser whose mortgage expertise, regulatory position and approach fit the property you want to finance and your financial circumstances. The Connect Experts mortgage adviser directory helps people searching in Aylesbury compare mortgage […]
Mortgage Broker in Weston-super-Mare BS23: Find an Adviser

Finding a mortgage broker in Weston-super-Mare is not simply a matter of choosing the nearest name. A useful search considers three connected questions: does the adviser cover Weston-super-Mare, do they understand the mortgage requirement, and can they communicate their advice in a way that makes a complex financial decision clear? Connect Experts helps you search […]
Mortgage Broker in Mablethorpe: Clear Coastal Mortgage Advice

Mortgage Broker in Mablethorpe searches often begin with a house, but the more important question is whether the property and the borrowing plan belong together. Mablethorpe has characteristics that can make that assessment particularly important. It is a Lincolnshire coastal town within East Lindsey, with residential homes, bungalows, flats, holiday accommodation and properties close to […]
Mortgage Broker in Prestonpans

Mortgage Broker in Prestonpans: A mortgage broker serving Prestonpans can help you examine how a lender may assess your income, deposit, credit record and chosen property before you submit an application. Connect Experts lets you search for mortgage advisers covering Prestonpans and the EH32 postcode area by mortgage type, location, language and personal preference. The directory […]
Mortgage Broker in Ampthill: Confident Home Decisions

Mortgage Broker in Ampthill searches often begin with a property, but the important question is whether the finance fits it. A house can look right long before a lender decides whether the borrower and property meet its criteria. In Ampthill, that assessment can involve property value, construction, age, income, deposit and future plans. The town […]
Mortgage Broker in Flitwick: Find Suitable Advice

A Mortgage Broker in Flitwick can help turn a property decision into a clearer financial one. Where you live may influence what you want from a home. However, what you can borrow depends on something different: your income, deposit, commitments, credit history, property and the lender’s criteria. That distinction matters in Flitwick. The town combines […]
Mortgage Broker in Kempston: Local Mortgage Expertise

Mortgage Broker in Kempston searches often begin with a property, but the more important question is whether the finance fits the life being built around it. Kempston sits immediately south-west of Bedford and forms part of the wider MK42 residential market. Buyers can encounter established terraces, semi-detached homes, larger family properties and newer developments around […]
Mortgage Broker in Biggleswade: Smart SG18 Guidance

A Mortgage Broker in Biggleswade can help turn a property choice into a workable financial decision. A home is more than an asking price. Its construction, location and valuation matter. Your income, deposit and existing commitments matter too. The mortgage works only when those different pieces fit the lender’s criteria. That is particularly relevant in Biggleswade. SG18 combines […]
Mortgage Broker in Houghton Regis: New-Build Expertise

A Mortgage Broker in Houghton Regis can help turn a property search into a lending decision based on evidence, not assumptions. Houghton Regis is changing. Established neighbourhoods now sit alongside significant development around Linmere, Bidwell and Houghton Regis North. For buyers, that means more property choices, but mortgage requirements can vary considerably between an older […]
Mortgage Broker in Linslade: Bedfordshire Advice

Mortgage Broker in Linslade searches often begin with a property, but the real decision usually starts with affordability. A house may suit your plans perfectly. The mortgage must also suit your income, deposit, credit profile and the lender’s criteria. That distinction matters in Linslade. The area combines established residential streets, access to Leighton Buzzard town […]
How to Check and Choose a Sharia-Compliant Mortgage Adviser

How to Choose a Sharia-Compliant Mortgage Adviser: Choose an adviser by checking regulatory status, relevant product experience, provider access, communication, fees and appointment method. An adviser should explain financial structures without claiming authority to issue a religious ruling. Connect Experts allows users to compare adviser profiles rather than relying on a general internet search. Start […]
Islamic Home Finance for Self-Employed and Complex-Income Applicants
Islamic Home Finance for Self-Employed: Self-employed applicants can qualify for Islamic home finance, but income must be evidenced in accordance with the provider’s criteria. Sole traders, directors, contractors and business partners may be assessed differently. Accounts, tax documents, contracts and business bank statements can all be relevant. A suitable adviser can identify which providers are more […]
Sharia-Compliant Buy-to-Let Finance for UK Property Investors
Sharia-Compliant Buy-to-Let Finance: Sharia-compliant buy-to-let finance may allow eligible landlords to purchase or refinance rental property through a structure designed to avoid conventional interest. Provider choice is narrower than the wider buy-to-let market. Rental income, deposit, property type, applicant status and portfolio exposure can all affect availability. Connect Experts helps landlords find advisers with relevant […]
Legal Ownership in Islamic Home Finance
Legal Ownership in Islamic Home Finance: Islamic home finance can involve shared ownership, leasing or a purchase at an agreed profit. The legal title, beneficial interest and customer’s right to occupy the property depend on the contract. A solicitor experienced in the relevant structure should review the documents before exchange. A mortgage adviser can explain […]
Islamic Home Finance Deposits and Affordability Explained
Islamic Home Finance Deposits and Affordability: Islamic home finance providers assess whether payments appear affordable and sustainable. They may examine income, expenditure, credit history, deposit evidence and property details. A larger contribution may widen the available choices, but provider criteria still differ. Connect Experts helps users find advisers who understand Islamic home finance and affordability assessments. […]
Home Purchase Plan or Islamic Mortgage: What Are You Actually Applying For?
Home Purchase Plan or Islamic Mortgage? An Islamic mortgage is often structured as a Home Purchase Plan rather than an interest-bearing loan. The provider may buy all or part of the property, while the customer makes rental and acquisition payments. Before applying, establish which legal structure is being offered, how ownership changes and which costs […]
What Happens to a Second Charge Mortgage When You Move?
Second Charge Mortgage When Moving House: A second-charge mortgage usually needs attention when the property is sold. It may need to be repaid from the sale proceeds. Porting may sometimes be possible, but it requires lender approval and a suitable new property. Review the loan before marketing the home. What Happens to a Second Charge […]
Second Charge Mortgages for Self-Employed Borrowers
Second Charge Mortgages for Self-Employed: Self-employed borrowers can apply for second-charge mortgages. Lenders may assess accounts, tax calculations, dividends, salary, retained profit or contract income. The property provides security, but lenders must still assess whether repayments are affordable. Second Charge Mortgages for Self-Employed Borrowers Self-employment does not create one standard type of income. A sole […]
Second Charge Mortgages for Home Improvements
Second Charge Mortgages for Home Improvements: A second-charge mortgage may fund an extension, renovation or major repair while leaving the existing first mortgage in place. The application should be based on a realistic work budget, a contingency allowance, and an affordable repayment plan. Future value should not be assumed. Second Charge Mortgages for Home Improvements A […]
Using a Second Charge Mortgage for Debt Consolidation
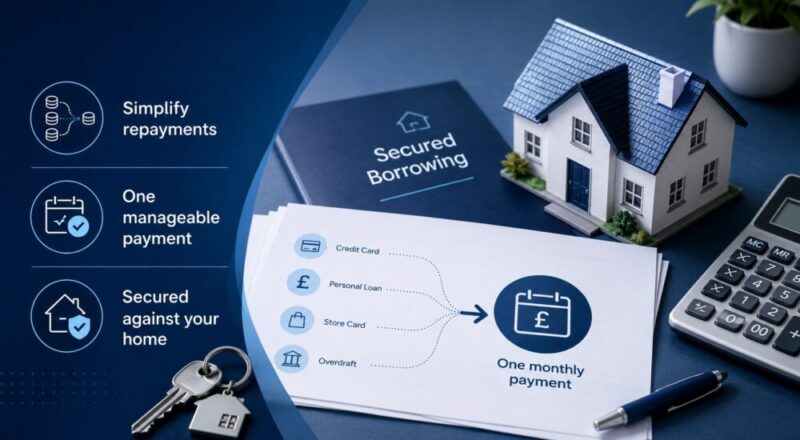
Second Charge Mortgage for Debt Consolidation: A second-charge mortgage may consolidate selected debts into a single secured payment. However, reducing the monthly payment can increase the repayment period and total interest. Unsecured debts also become secured against the property. Advice should examine the cause of the debt, not only its current balance. Using a Second Charge […]
Second Charge Mortgage, Remortgage or Further Advance?
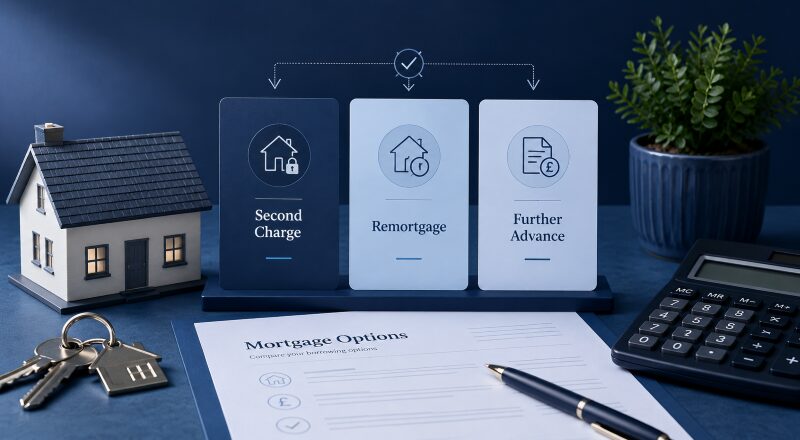
Second Charge vs Remortgage or Further Advance: A remortgage replaces the existing mortgage. A further advance adds borrowing from the current lender. A second-charge mortgage creates a separate secured loan. The right option depends on rates, fees, equity, affordability and future plans. Second Charge Mortgage, Remortgage or Further Advance? Homeowners raising money from a property […]
Second Charge Mortgage Costs: What Should You Compare?
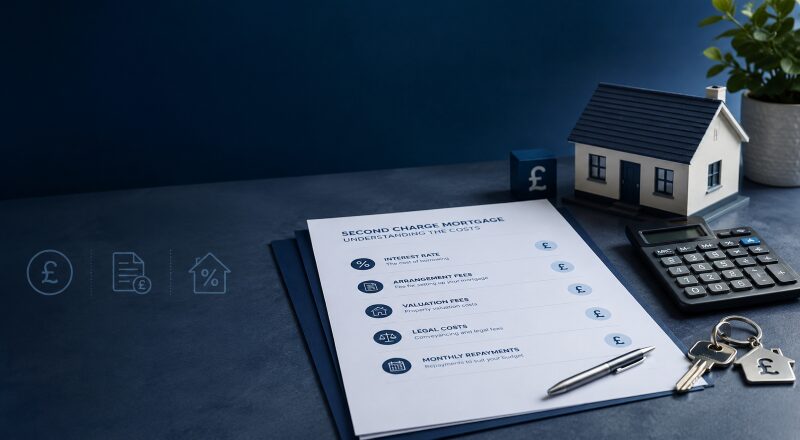
Second Charge Mortgage Costs: A second-charge mortgage should not be judged by its interest rate alone. The term, fees, repayment structure and early repayment conditions all affect its real cost. A suitable adviser should show the total amount repayable and compare it with remortgaging, a further advance and unsecured borrowing. Second Charge Mortgage Costs: What […]
Refinancing an Expiring Commercial Bridging Loan
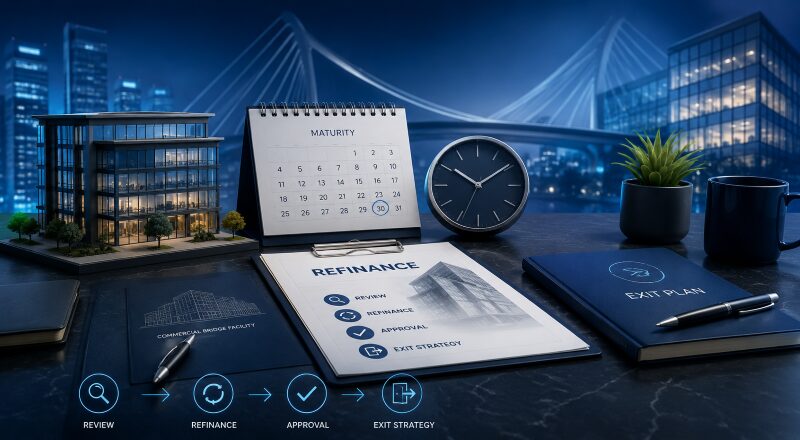
Refinancing an Expiring Commercial Bridge: A bridging loan maturity date is not an administrative reminder. It is the point by which the agreed capital, interest and charges are expected to be repaid. When a commercial bridge approaches expiry, the borrower should examine the problem before the remaining time becomes the main problem. Refinancing may be possible, […]
Bridging Loans for Owner-Occupied Commercial Property
Bridging Loans for Business Premises: Business premises are both property and infrastructure. A warehouse supports distribution. A surgery provides treatment rooms. An office gives a company a working base. When the acquisition deadline is short, bridging finance may provide temporary funding before a commercial mortgage becomes available. The assessment must consider both the building and the […]
Bridge-to-Commercial Mortgage Finance: Planning the Exit Before the Loan Begins
Bridge-to-Commercial Mortgage Finance: Every bridging loan begins with an ending. Bridge-to-commercial mortgage finance uses a short-term loan first, followed by a longer-term commercial mortgage. The approach may solve an immediate problem. However, it only works when the second loan remains achievable. The bridge creates time. It does not remove the long-term lender’s criteria. At a […]
Semi-Commercial Bridging Loans for Mixed-Use Property
Semi-Commercial Bridging Loans Explained: A mixed-use building does not fit neatly into one lending category. A shop with flats above combines commercial and residential space. So might an office with living accommodation or a public house with an owner’s residence. Semi-commercial bridging loans can provide short-term finance where the property, deadline or intended works prevent […]
Commercial Refurbishment Bridging Loans: Finance Before a Property Meets Mortgage Criteria
Commercial Refurbishment Bridging Loans: A building may have value even if it is not ready for long-term lending. Its roof may require repair. Essential services may be absent. The layout may no longer suit modern commercial use. Commercial refurbishment bridging loans can provide temporary funding while the property moves from its current condition to a financeable […]
Commercial Auction Bridging Loans: Funding a Time-Limited Purchase
Commercial Auction Bridging Loans: A commercial auction purchase is governed by the clock. Once the hammer falls, the buyer normally becomes legally committed. The completion deadline appears in the auction contract rather than the buyer’s preferred mortgage timetable. Commercial auction bridging loans provide short-term funding when a standard commercial mortgage may not be completed within that […]
New-Build Mortgages for First-Time Buyers

New-Build Mortgages for First-Time Buyers: New-build mortgages can involve stricter LTV limits, developer incentives and fixed reservation deadlines. The lender values the completed property rather than accepting the developer’s price automatically. Buyers should coordinate the mortgage offer, legal work and construction timetable. What Counts as a New-Build Property? A new-build is usually a property being […]
Shared Ownership Mortgages for First-Time Buyers

Shared Ownership Mortgages for First-Time Buyers: Shared ownership allows an eligible buyer to purchase a share of a property and pay rent on the remaining share. Affordability must include the mortgage, rent, service charge and household costs. The property, lease, and housing provider requirements must also satisfy the lender. How Does Shared Ownership Work? A […]
Family-Assisted Mortgages Without Giving Away the Deposit

Family-Assisted Mortgages Without a Deposit Gift: Some family-assisted mortgages allow relatives to support a first-time buyer without making a permanent cash gift. Support may involve savings, property security, a guarantee or joining the mortgage. Each structure creates different risks and legal responsibilities. Why Might Families Prefer an Assisted Mortgage? Parents or relatives may want to help […]
Joint Borrower Sole Proprietor Mortgages for First-Time Buyers
JBSP Mortgages for First-Time Buyers: A joint borrower sole proprietor mortgage can include another person’s income without placing that person on the property title. All borrowers remain responsible for the mortgage debt. The arrangement requires careful consideration of legal rights, affordability and future borrowing. What Does Joint Borrower Sole Proprietor Mean? A JBSP mortgage separates mortgage […]
Gifted Deposits for First-Time Buyers Explained
Gifted Deposits for First-Time Buyers: A gifted deposit is money given towards a property purchase without an expectation of repayment or ownership. Lenders and solicitors normally need evidence of the donor, the source of funds and the nature of the gift. Prepare the paperwork before submitting the mortgage application. What Is a Gifted Deposit? A […]
How Do 100% Mortgages Work for First-Time Buyers?
How 100% Mortgages Work for First-Time Buyers: A 100% mortgage may allow an eligible buyer to borrow the entire purchase price. These products remain subject to affordability, credit, property and lender criteria. They may also carry greater negative-equity risk than lower-LTV borrowing. Compare the structure with 95% and family-assisted options before applying. What Is a 100% […]
New-Build Buy-to-Let Mortgages: Deposits, Valuations and Completion Risks
New-build buy-to-let mortgages finance a newly constructed property intended for rental. Lenders may set different loan-to-value limits for new-build houses and flats. The valuation, developer incentives, lease terms and completion date can all affect the mortgage. Off-plan buyers should consider what happens when the mortgage offer expires before construction finishes. What counts as a new-build […]
Student Buy-to-Let Mortgages: Finance for Property Rented to Students
Student buy-to-let mortgages finance property intended for student tenants. The lender will consider the property structure, tenancy model, location, rental demand and landlord experience. A shared student house may be treated as an HMO. A self-contained flat may fit ordinary buy-to-let criteria. The right mortgage category must be established before an application is submitted. What […]
Buy-to-Let Remortgages and Capital Raising: What Landlords Should Check
Buy-to-Let Remortgages and Capital Raising: A buy-to-let remortgage replaces an existing landlord mortgage with another mortgage. Landlords may remortgage to review their rate, change the term or release equity. The lender will reassess the property, rent, loan-to-value ratio and borrower’s wider position. Equity is not automatically available simply because the property value has increased. What is […]
Multi-Unit Freehold Block Mortgages: Finance for Several Homes Under One Title
Multi-Unit Freehold Block Mortgages: A multi-unit freehold block comprises several separate homes held under a single freehold title. It may include converted flats, purpose-built units or several self-contained residences. Standard buy-to-let lenders may not accept this structure. Specialist lenders can assess the block, individual rents and overall marketability. Connect Experts helps landlords find advisers with relevant […]
Consumer Buy-to-Let Mortgages: When Landlord Finance Is Treated Differently
Consumer buy-to-let mortgages may be suitable when someone becomes a landlord without initially intending to run a property business. This can happen after inheriting a property or moving home and renting out the previous residence. The classification matters because consumer buy-to-let lending is subject to a different regulatory framework from ordinary business buy-to-let lending. A […]
How Property Type Affects Buy-to-Let Mortgages
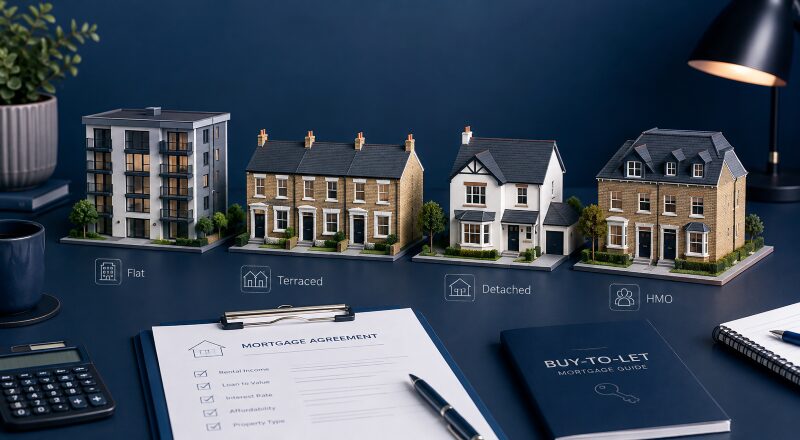
How Property Type Affects Buy-to-Let Mortgages: Buy-to-let lenders assess both the landlord and the property. Construction, tenure, location, occupancy, lease terms and letting model can all affect lender choice. A property may be suitable to rent but unsuitable for a particular mortgage lender. The intended use should be checked before an application or auction commitment. A […]
Personal or Limited Company Buy-to-Let: What Lenders Assess
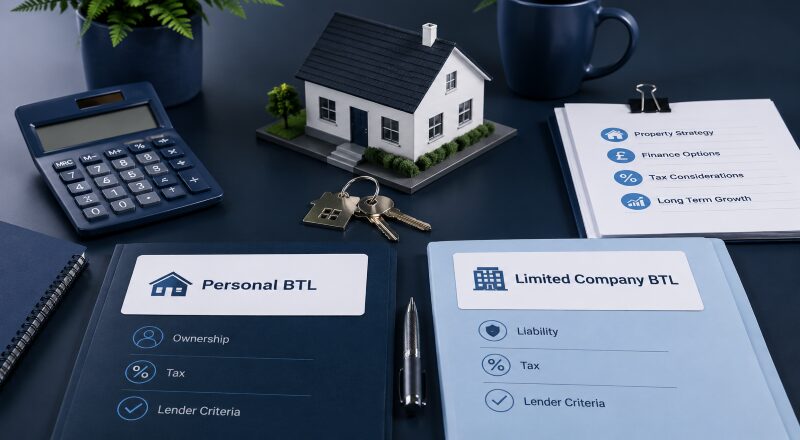
Personal or Limited Company Buy-to-Let: A buy-to-let property can be financed in a personal name or through a company, subject to lender criteria. The two routes may involve different mortgage products, documents, guarantees, costs and tax treatment. A mortgage adviser can explain lender requirements. A qualified tax adviser should assess the tax consequences. Ownership Structure Changes […]
Buy-to-Let Mortgage Application Checklist for Landlords
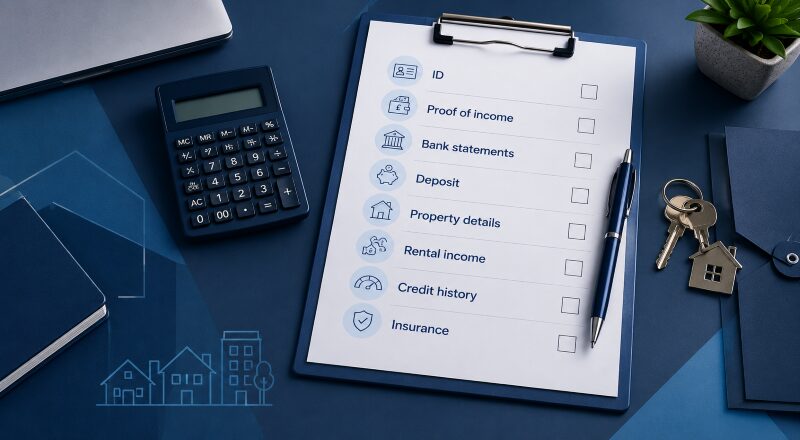
Buy-to-Let Mortgage Application Checklist: A complete buy-to-let application usually depends on four connected areas: the borrower, the deposit, the property and the expected rent. Portfolio and limited company cases may require further records. Preparing information early helps an adviser assess lender criteria and identify missing evidence before submission. A Mortgage Application Begins Before the Form A […]
Real Cost of Moving Home With a Mortgage
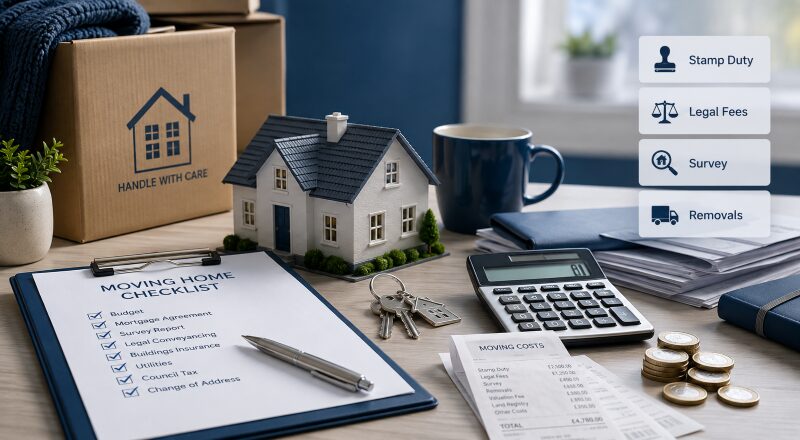
The Real Cost of Moving Home With a Mortgage: The deposit is not the complete cost of moving home. A household may have enough equity for the next purchase but insufficient cash for the transaction itself. Mortgage charges, legal work, property tax, surveys and removals can all become payable within a short period. A complete budget […]
Property Chains and Mortgage Offers When Moving Home
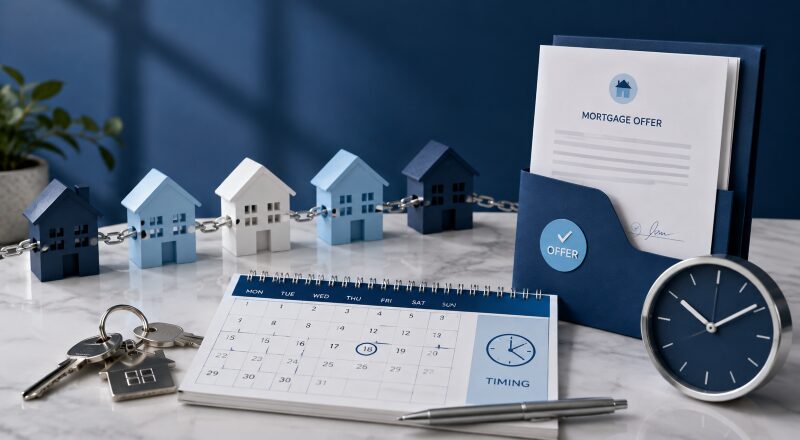
Property Chains and Mortgage Offer Timing: A mortgage can be affordable and suitable but still fail to complete on time. Moving home depends on several parties completing connected legal and financial tasks. The mortgage offer is only one part of that system. Understanding timing can reduce the risk of an expired offer, a lost rate, or […]
Moving Home Affordability: What Lenders Reassess
Moving Home Affordability: A homeowner may have paid their mortgage reliably for years. That record is important. However, it does not fix the amount they can borrow for their next home. Moving house creates a new mortgage decision. The lender must consider the applicant’s current finances, the requested loan amount, and the proposed property. At a […]
Mortgage Porting When Moving Home: How It Works
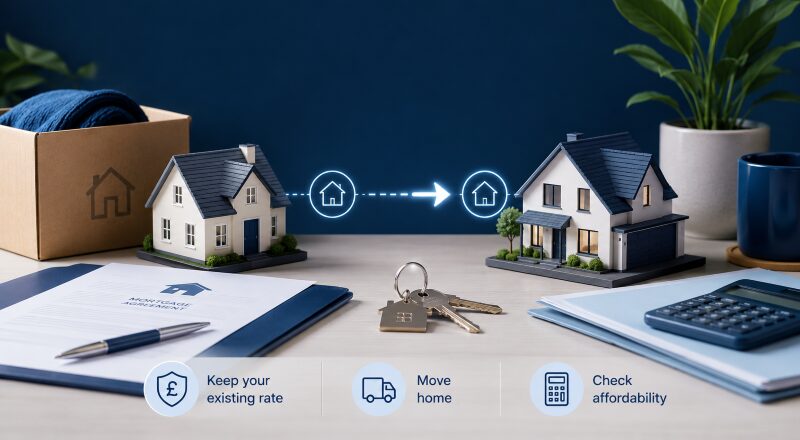
Mortgage Porting When Moving Home: Mortgage porting sounds like a simple transfer. In practice, the lender normally closes the mortgage on one property and creates another mortgage on the next property. The product may move. The original mortgage security does not. This distinction matters because homeowners can wrongly assume that portability guarantees approval. It does […]
How to Compare Mortgage Advisers When You Are Self-Employed
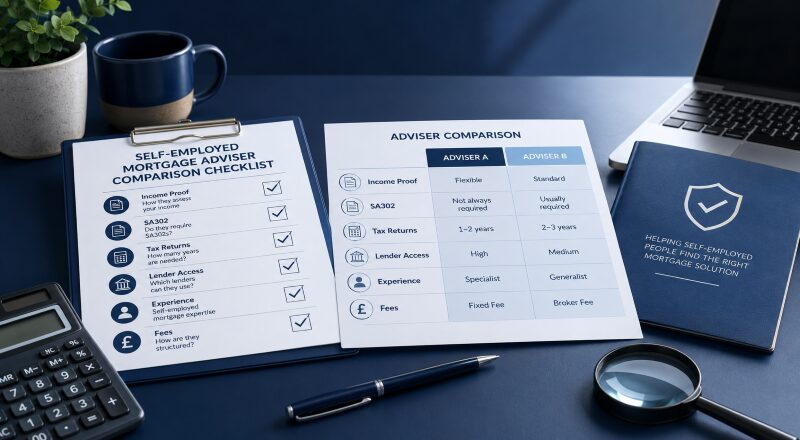
How to Compare Self-Employed Mortgage Advisers: Do not compare advisers only by distance or headline fee. Consider: Experience with your income structure Lender access How income will be assessed Required documents Service and communication Fees Regulatory status Support after submission Connect Experts lets you compare adviser profiles by practical criteria. The directory does not provide […]
When Should a Self-Employed Applicant Start Preparing for a Residential Mortgage?
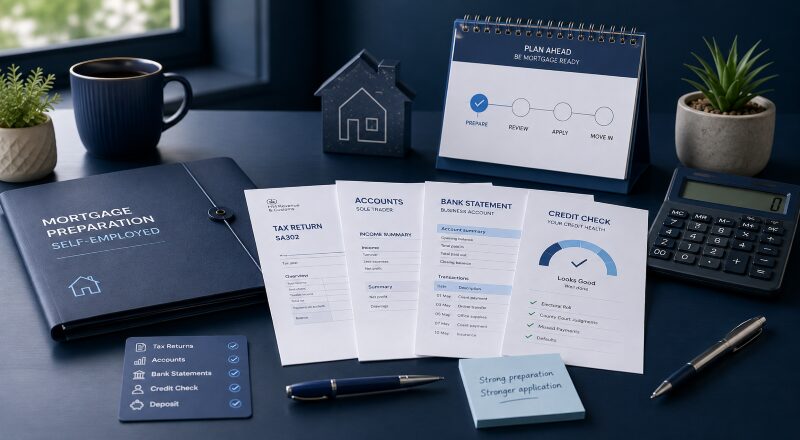
When to Prepare for a Self-Employed Mortgage: Begin preparing before a property purchase or remortgage becomes urgent. Early preparation can help you: Identify missing tax documents. Check whether accounts need finalising. Understand which income periods may be assessed. Document the deposit. Review credit commitments. Avoid unsuitable lender applications. Plan around a fixed-rate end date. Preparation […]
Salary, Dividends or Retained Profit: How Might Lenders Read a Director’s Income?
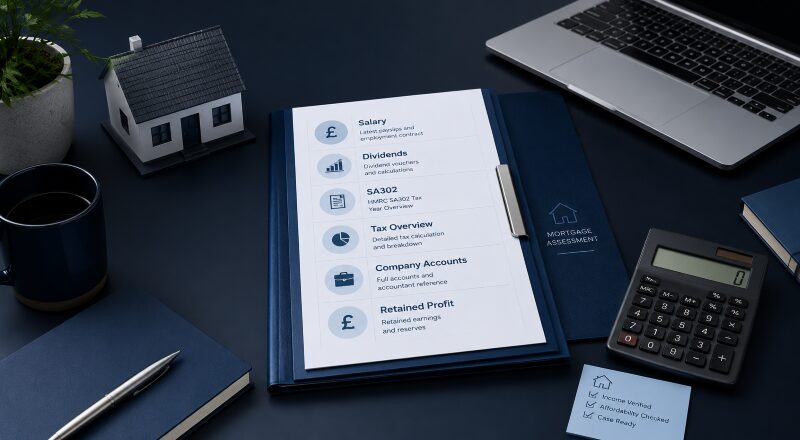
Director Mortgage Income: Limited company accounts can produce several income figures. A lender may assess a director using: Salary Salary and dividends Salary and a share of company profit An average taken across several years The permitted calculation depends on the lender, shareholding and wider case. Company turnover is not the same as personal income. […]
What Documents Does a Mortgage Adviser Need Before Your Rate Ends?
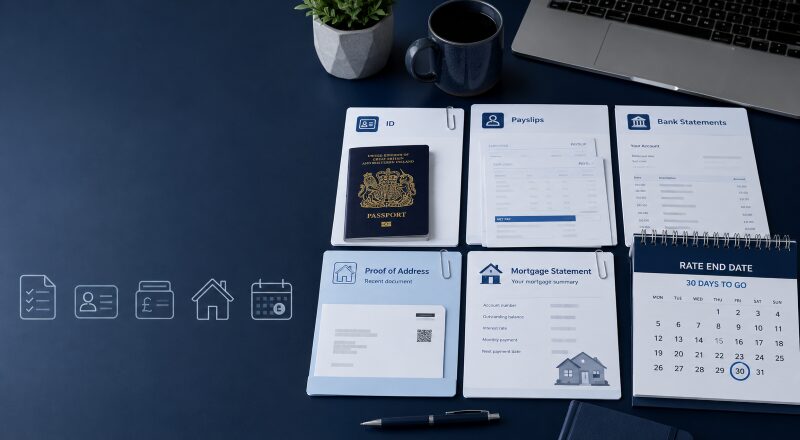
Documents Needed Before Your Mortgage Rate Ends: Preparing documents early can make a mortgage rate review more accurate. An adviser may ask for: Proof of identity and address. Current mortgage statements. Income evidence. Bank statements. Details of loans and credit cards. Property information. Evidence of savings. Insurance or lease documents where relevant. Information about future […]
Mortgage Rate Ending After Your Circumstances Changed
Mortgage Rate Ending After Circumstances Changed: A mortgage rate ending does not mean the next application will be assessed under the original rules. A lender may consider your current: Employment and income. Credit commitments. Payment history. Household expenditure. Property value and condition. Residency. Mortgage balance. Intended property use. Retirement plans. Do not assume that changed […]
Product Transfer or Remortgage? Compare the Full Cost Before Your Rate Ends
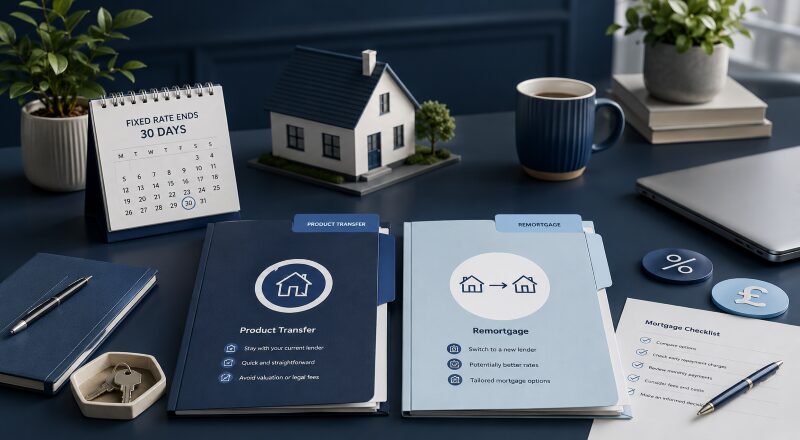
Product Transfer or Remortgage Before Rate Ends: A product transfer keeps the mortgage with the current lender. A remortgage normally moves the borrowing to another lender. The lowest advertised rate may not produce the lowest overall cost. Compare: Interest over the relevant period. Product and adviser fees. Legal and valuation costs. Cashback or incentives. Early […]
Six Months Before Your Mortgage Rate Ends
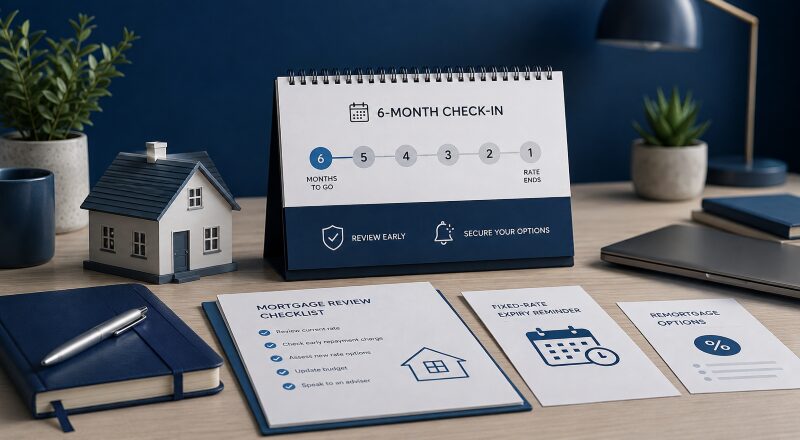
Six Months Before Your Mortgage Rate Ends: A mortgage review should begin before the final monthly payment under your current deal. Starting several months early gives you time to: Confirm the exact end date. Check any early repayment charge. compare product transfers and remortgage options. Review your property value and remaining balance. Prepare income and […]
What an Equity Release Adviser Should Compare Before Recommending a Plan
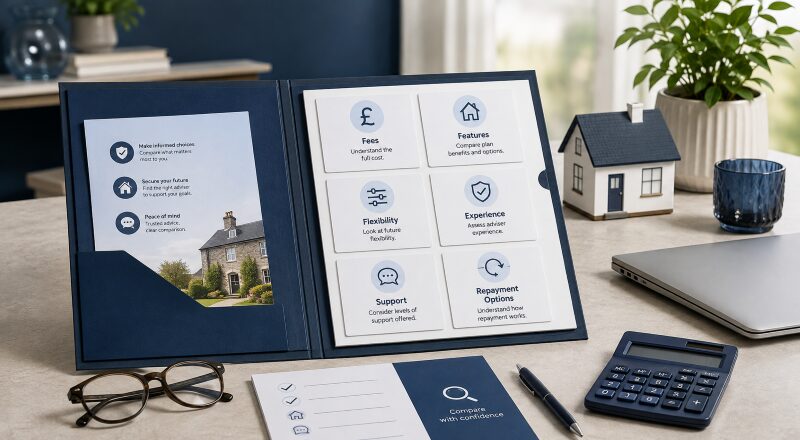
What Equity Release Advisers Should Compare: An equity release recommendation should compare costs, alternatives, risks, property criteria and future needs. The largest available release is not automatically the most suitable choice. Use the Connect Experts directory to find an adviser who can complete a personal assessment. Advice should begin before product selection Equity release is often […]
Preparing for Your First Meeting With an Equity Release Adviser
First Equity Release Adviser Meeting: A well-prepared first meeting helps an adviser understand your property, finances, objectives and future plans. Gather the basic documents, list your questions, and decide whether the family should attend. Find someone to speak with through the Connect Experts equity release adviser directory. Preparation improves the quality of the discussion An […]
What to Compare in an Equity Release Adviser Directory Profile

Compare Equity Release Adviser Profiles: An adviser profile should help you compare regulation, specialist experience, communication, location and service. It should not be treated as an equity release recommendation. Use the Connect Experts adviser directory to identify possible advisers. Then confirm their service directly before proceeding. A profile is a starting point, not a recommendation A […]
When Should You Review Mortgage Protection Insurance?
When Should You Review Mortgage Protection Insurance? Protection should be reviewed after material changes to the mortgage, income, work, health or household. A review does not always mean replacing a policy. Existing cover may contain valuable terms that cannot be reproduced through a new application. Protection is based on a moment in time Every protection […]
Mortgage Protection for Self-Employed Borrowers: What Should You Consider?
Mortgage Protection for Self-Employed Borrowers: Self-employed borrowers may have limited sick pay and variable earnings. A protection review should consider personal income, business costs, savings, mortgage payments and financial dependants. Policy definitions are particularly important where work involves specialist, manual or changing duties. A mortgage payment is personal, but income may depend on a business […]
How Much Mortgage Protection Cover Do You Need?
How Much Mortgage Protection Cover Do You Need? The mortgage balance is only the starting point. A suitable protection calculation may also include income, household bills, debts, dependants, savings and workplace benefits. Different policies solve different financial problems. Therefore, each cover amount should be calculated separately. Protection is a calculation, not a standard package A […]
Life Insurance, Critical Illness or Income Protection: What Is the Difference?
Life insurance vs critical illness vs income protection: Life insurance typically pays out after death. Critical illness cover can pay after a qualifying diagnosis. Income protection can provide regular payments when illness or injury prevents you from working. These products respond to different events. One policy does not automatically replace the others. A mortgage protection […]
How to Choose a Mortgage Broker by Language and Expertise

Choose a Mortgage Broker by Language: A shared language can make detailed mortgage discussions clearer. However, language should not be the only selection criterion. Check the adviser’s firm, regulatory status, mortgage permissions, relevant experience, fees and appointment format. The adviser should understand both your communication needs and your type of mortgage application. Connect Experts lets […]
Mortgage Documents Explained by a Multilingual Broker
Mortgage Documents Explained by Multilingual Brokers: Mortgage applications rely on accurate documentation. A multilingual broker can explain what documents are requested, why lenders need them and how they relate to the application. However, an explanation is not automatically a certified translation. Applicants should confirm whether foreign-language documents need professional translation and whether the lender has […]
Mortgage Advice in Your First Language: What Should Be Explained?
Mortgage Advice in Your First Language: Mortgage advice should explain the proposed product, costs, risks and application process in terms you understand. Speaking with an adviser in your preferred language can help you discuss detailed circumstances and ask precise questions. However, language ability should be considered alongside the adviser’s qualifications, permissions and relevant mortgage experience. […]
Why Search for a Mortgage Broker by County?

Why Search for a Mortgage Broker by County? Searching by county can make your mortgage adviser search more focused. It lets you compare advisers who cover your wider area, rather than limiting your search to one town. However, location should not be the only deciding factor. You should also consider regulatory status, mortgage expertise, communication […]
Mortgage Broker in St John’s Wood

Mortgage Broker in St John’s Wood: A valuable property does not always produce a straightforward mortgage application. In St John’s Wood, the property may be substantial, but the applicant’s income can be equally complex. Earnings may include bonuses, dividends, retained company profits, overseas income or investment returns. A Mortgage Broker in St John’s Wood can examine […]
Mortgage Broker in Chelsea SW3

Mortgage Broker in Chelsea: Property finance in Chelsea often begins with a simple question. Does the lender understand the borrower, the property and the proposed structure? Chelsea’s SW3 market includes apartments, period houses, high-value homes and investment properties. Their prices and legal structures can make lender selection particularly important. A mortgage broker in Chelsea can assess […]
Mortgage Broker in Knightsbridge SW1X

Mortgage Broker in Knightsbridge: A Knightsbridge property may appear simple from the pavement yet prove complex from a lender’s desk. High property values can increase the loan required. However, price alone does not determine whether a mortgage is suitable or affordable. Income structure, property condition, lease terms, deposit source and repayment plans can all affect […]
Mortgage Broker in Belgravia SW1X

A mortgage broker in Belgravia can help buyers and homeowners assess finance for prime London property. Belgravia mortgage cases often involve high property values, substantial deposits, complex income or international financial arrangements. The question is rarely limited to how much someone earns. The stronger question is how their income, assets, liabilities and property plans should […]
Mortgage Broker in Holloway N7

Mortgage Broker in Holloway N7: A property address may look straightforward, but lenders assess much more than the postcode. In Holloway, the property may be a leasehold flat, a converted house, an ex-local-authority home, or a mixed-use building. Each feature can affect lender choice, valuation and affordability. A mortgage broker in Holloway can examine your income, […]
Mortgage Broker in Bermondsey SE1

Mortgage Broker in Bermondsey: Bermondsey combines established residential streets, converted industrial buildings, modern developments and riverside apartments. That variety can create very different mortgage questions within a relatively small area. A lender does not assess Bermondsey as a single property market. It assesses the applicant, property, tenure, valuation and proposed use. Connect Experts helps you find […]
Mortgage Broker in North West London

Mortgage Broker in North West London: A postcode can indicate where a property is located. It cannot explain how a lender will assess the person buying it. North West London includes varied property types, values, ownership structures and borrower profiles. A mortgage application in Hampstead may involve a high-value flat and a short lease. One […]
Mortgage Broker in North East London

Mortgage Broker in North East London: A mortgage application brings together a person, a property and a lender’s rules. In North East London, that relationship can become complicated. The area contains Victorian terraces, purpose-built flats, converted properties, new developments and former local authority homes. Each property and borrower may be assessed differently. Connect Experts helps you […]
Mortgage Broker in South London

Mortgage Broker in South London: South London is not one uniform mortgage market. A flat in Battersea may raise different lending questions from a house in Bromley. A self-employed buyer in Croydon may also need a different assessment from a landlord purchasing in Lewisham. The property provides the security. However, the borrower, income, deposit and intended […]
Mortgage Broker in Central London
Mortgage Broker in Central London: A Central London mortgage often begins with an unusual combination of property, income and timing. The property may be a leasehold flat above commercial premises. The applicant may receive bonuses, dividends or income from several countries. The purchase could also involve a short lease, substantial service charges or a high deposit. […]
Mortgage Broker in South West London

Finding a mortgage broker in South West London begins with understanding the property, the applicant and the purpose of the borrowing. South West London includes contrasting property markets within a relatively compact area. A leasehold flat in Battersea may raise different questions for lenders than a family house in Wimbledon. A buy-to-let property in Tooting […]
Mortgage Broker in West Acton

Mortgage Broker in West Acton: A mortgage application connects three practical questions: what the applicant can afford, what the property is worth and what a lender will accept. In West Acton, those questions may involve higher London property values, flats with leasehold conditions, varied income arrangements and different plans for the property. A Mortgage Broker in […]
Mortgage Broker in East Acton

Mortgage Broker in East Acton: A mortgage decision begins with a property, but it is determined by evidence. Your income, deposits, credit history, existing commitments, and property type can all affect which lenders may consider your application. Connect Experts helps you find a mortgage broker in East Acton by mortgage type, location, language, and personal preferences. […]
Mortgage Broker in South Acton

Mortgage Broker in South Acton: A mortgage application turns a future housing plan into a present financial commitment. For people buying or refinancing property in South Acton, that commitment may involve more than comparing headline rates. Lender criteria can differ across income types, deposits, credit histories and property structures. Connect Experts helps you search for a […]
Mortgage Adviser in Walthamstow E17

Finding a mortgage adviser in Walthamstow starts with matching your circumstances to the right type of mortgage expertise. Your income, deposit, credit history and chosen property will affect the lenders available to you. Property type, lease terms and monthly commitments can also change the outcome. Connect Experts helps you compare mortgage advisers serving Walthamstow, E17 […]
Mortgage Adviser in Clapton Common SW4, SW11 and SW12

Mortgage Adviser in Clapton Common: A property decision begins with figures, but it rarely ends there. The mortgage must also fit the property, income, deposit, future plans and acceptable level of financial risk. Connect Experts helps you find a mortgage adviser in Clapton Common based on location, expertise, language and personal preference. You can review adviser […]
Mortgage Adviser in Soho W1

Finding a mortgage adviser in Soho starts with matching your circumstances to the right expertise. Soho sits within one of London’s most distinctive property areas. Flats, converted buildings, leasehold homes and mixed-use streets can create detailed lending questions. Borrowers may also receive income through salaries, bonuses, commissions, company profits or several income sources. Connect Experts […]
Mortgage Adviser in Nuneaton CV10 & CV11

Mortgage Adviser in Nuneaton: A mortgage connects a long-term financial commitment to a particular property, income and stage of life. The figures matter, but so do the decisions made before an application reaches a lender. Connect Experts helps you search for a mortgage adviser in Nuneaton based on your mortgage needs and personal preferences. You can […]
Mortgage Broker in Hampton: Expert Mortgage Help
Mortgage Broker in Hampton: Hampton has grown around modern housing, lakes, schools, and distinct neighbourhoods rather than a traditional historic town centre. That makes its mortgage market different from many nearby parts of Cambridgeshire. For somebody buying in Hampton PE7, the property itself can be as important as the applicant. New-build status, incentives, tenure, service […]
Mortgage Broker in Harrogate: Period Homes and New Growth
A Mortgage Adviser in Harrogate often start where two kinds of value meet: the character a buyer sees in a property and the value a mortgage lender is prepared to place on it. That distinction matters in Harrogate. The town contains substantial established housing, including Victorian and Edwardian property within and around its conservation areas. At […]
Find a Trusted Mortgage Adviser in Great Yarmouth Today

Finding a mortgage adviser in Great Yarmouth starts with matching your circumstances to the right expertise. Connect Experts lets you compare mortgage advisers by location, mortgage type, language and other preferences, whether you are buying a home, remortgaging, investing in rental property or dealing with a more specialist mortgage case. Search Great Yarmouth mortgage expertise […]
Protection Adviser in Maidenhead

Looking for a protection adviser in Maidenhead? Connect Experts helps you search for advisers who can discuss protection cover for your income, mortgage, family or business needs. Protection advice is not only for people buying a home. It can also help homeowners, parents, landlords, self-employed workers and people with financial commitments. Maidenhead sits within the Royal […]