Mortgage Brokers in Cumbria can support buyers, homeowners and property investors across a county with very different housing markets.
A county can share one name without sharing one type of property.
Carlisle offers an established city market. West Cumbria includes coastal communities and important employment centres. South Cumbria extends to Kendal, the Furness peninsula, and the Lake District.
Property type, income, deposit, location and borrowing requirements can therefore affect which lenders may consider your application.
Cumbria Property Market and Mortgage Considerations
Cumbria does not have one uniform housing market.
Current ONS figures demonstrate the difference between its two unitary authority areas.
In Cumberland, the provisional average house price was £172,000 in June 2026. First-time buyers paid an average of £152,000.
In Westmorland and Furness, the provisional June 2026 average was £230,000. First-time buyers paid an average of £193,000.
These figures are useful indicators, not valuations for individual homes.
Location can make a significant difference.
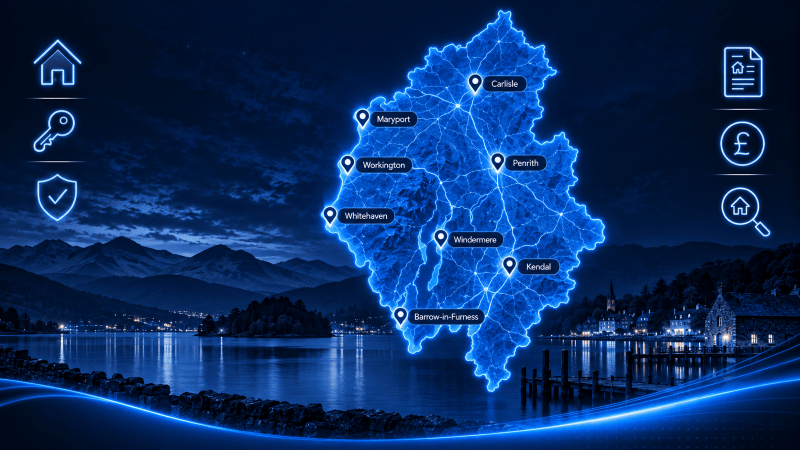
Carlisle provides city housing and access to the M6 and West Coast Main Line. West Cumbria includes established communities around Whitehaven, Workington and Maryport.
Further south, Kendal and the wider Furness area provide access to employment centres, countryside and Lake District communities.
Buyers may therefore encounter different considerations involving:
- property valuations;
- rural access;
- older construction;
- leasehold or freehold tenure;
- land or outbuildings;
- local resale demand;
- affordability and deposit requirements.
Lender criteria can differ significantly, even where two properties have similar asking prices.
Mortgage Advice Across Cumbria
A mortgage adviser can review your circumstances before you approach a lender.
This may include:
- your income and employment structure;
- deposit or available equity;
- existing borrowing and regular commitments;
- credit history;
- property type and condition;
- required loan-to-value;
- lender affordability and underwriting criteria.
This can be particularly useful where a property or applicant does not fit standard lending criteria.
Cumbria includes rural homes, traditional stone properties, flats, modern developments and properties close to protected landscapes.
Some buyers may also need advice involving self-employed income, buy-to-let finance, complex earnings or specialist property lending.
Clear communication matters too. Users who prefer another language can explore bilingual mortgage brokers through the directory.
Moving within Cumbria can involve very different property decisions.
A buyer moving to Carlisle may prioritise commuting, schools and access to city services. Someone buying near the Lake District may place greater emphasis on rural access and property character.
Coastal locations can create another set of considerations, while parts of South Cumbria are influenced by employment around Barrow-in-Furness and neighbouring communities.
Transport should also factor into the wider buying decision.
The M6 provides north-south road access through eastern Cumbria. Carlisle and Penrith sit on the West Coast Main Line, while other rail routes connect communities across the county.
The mortgage itself remains based on affordability, property suitability and lender criteria rather than location alone.
Specialist Mortgage Considerations in Cumbria
Not every Cumbria mortgage application will require specialist advice.
However, extra experience may be valuable where circumstances involve:
- self-employed or variable income;
- company directors and retained profits;
- bonuses or multiple income sources;
- unusual or rural property;
- buy-to-let portfolios;
- larger borrowing requirements;
- bridging or other specialist property finance.
The objective should be to understand the case before selecting a lender.
This can reduce the risk of submitting an application where the lender’s criteria are unsuitable.
How to Choose a Mortgage Broker in Cumbria
Location helps, but it shouldn’t be the only deciding factor.
A suitable mortgage broker should understand both your circumstances and the type of finance you require.
Before choosing an adviser, consider:
- whether they advise on the mortgage type you need;
- experience with similar income or property circumstances;
- how they search available lenders;
- whether any adviser fee applies;
- how appointments are provided;
- whether face-to-face advice matters to you;
- how clearly they explain lender criteria and risks.
You should also confirm the adviser’s or firm’s regulatory status before proceeding.
A local adviser may offer helpful knowledge of Cumbria property. However, an adviser elsewhere may still be suitable if specialist expertise matters more than distance.
Start Your Search for a Mortgage Adviser in Cumbria
Finding the right adviser becomes easier when the search starts with your circumstances rather than a mortgage rate alone.
Education and Household Planning
Education costs can form part of wider household expenditure and long-term financial planning.
Cumbria and surrounding areas include independent education options, particularly around established towns and rural school communities.
Families considering school fees alongside property borrowing can read more about Education Finance.
Consider education costs alongside income, mortgage payments, and other household commitments.
Finance and Affordability
Mortgage affordability depends on more than salary.
Lenders may consider existing credit commitments, dependants, deposit size, income structure and the proposed property.
Two households with the same income may therefore receive very different borrowing assessments.
A mortgage adviser can explain how those factors interact with lender criteria before you apply.
High-Net-Worth Mortgage Requirements
Cumbria is not uniformly a high-value property market.
However, larger country homes, substantial rural properties and higher-value Lake District locations can create more complex borrowing requirements.
Applicants may also have bonuses, investment income, retained company profits or several income sources.
Where relevant, users can explore High Net Worth Mortgage Brokers for more specialist borrowing circumstances.
Those with more complex estates or family financial responsibilities can also review High Net Worth Protection Services.
Mortgage Protection and Household Security
Taking a mortgage can also be an appropriate time to review household protection.
Depending on individual circumstances, an adviser may discuss life cover, critical illness cover, income protection or related insurance.
The purpose is not simply to protect the property.
It is to consider how mortgage payments and household commitments might be managed if income or health circumstances changed.
Protection needs and eligibility vary between households.
Later-Life Property Decisions in Cumbria
Older homeowners may also consider how property wealth fits their wider retirement plans.
Equity release is a specialist form of later-life lending and is not suitable for everyone.
It can affect inheritance, means-tested benefits and the value remaining in an estate.
Homeowners considering this area can read about Equity Release Advisers in Cumbria and the alternatives to consider before proceeding.
A mortgage decision begins with the property, but it is shaped by the person buying it.
Your income, deposit, existing commitments, future plans and property choice all influence the mortgage options available.
Use Connect Experts to compare advisers whose experience matches what you actually need.
Find a suitable mortgage adviser in Cumbria and begin your search with clearer information and greater choice.
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it.
If you are Looking for a Mortgage Network
If you are Looking for a Mortgage Network
“Hi, I’m Liz Syms, Chief Executive Officer and founder of Connect Experts, Connect Mortgages, and Connect for Intermediaries.
If you are a UK mortgage broker based in Cumbria, joining our mortgage network can help you increase your visibility to clients actively searching for trusted, FCA-authorised advice. Brokers featured on our mortgage brokers in Cumbria page are matched with clients who value clear communication and professional guidance, including those who prefer advice in a specific language.
Our platform is designed to support compliant, client-focused advisers and help you connect with the right audience across Cumbria.”
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us