

Mortgage Brokers in Dumfriesshire: A mortgage decision can start with a property, but it depends on much more than the asking price.
Mortgage Brokers in Dumfriesshire can help buyers, homeowners, and landlords understand how income, deposit, credit history, property type, and lender criteria come together before making an application.
Dumfriesshire has its own mortgage considerations. Dumfries is the region’s main urban centre, while places such as Annan, Lockerbie, Moffat, Sanquhar and Thornhill offer different combinations of rural housing, commuter links, older properties and local demand. The existing Connect Experts page also identifies traditional stone homes, rural cottages, properties with land and smaller new-build developments as part of the local housing mix.
Use Connect Experts to compare advisers by location, mortgage experience and communication preferences before deciding who to contact.
At a glance: Mortgage Brokers in Dumfriesshire
- Dumfriesshire combines town, village, rural and border property markets.
- Dumfries and Galloway’s average house price was £170,000 in July 2026.
- First-time buyers paid an average of £143,000.
- Homes bought with a mortgage averaged £166,000.
- Detached homes averaged £260,000, compared with £88,000 for flats and maisonettes.
- Rural properties, land, outbuildings and older construction can require closer lender assessment.
- Cross-border employment and variable or self-employed income may affect underwriting.
- Adviser expertise can matter more than physical distance.
The latest ONS figures are provisional and apply to the wider Dumfries and Galloway local authority rather than historic Dumfriesshire alone
Mortgage Advice Across Dumfriesshire
The nearest mortgage broker is not automatically the most suitable one.
What matters is whether the adviser understands the type of mortgage, income and property involved.
A borrower buying a conventional home in Dumfries may face a relatively straightforward valuation. Someone purchasing a rural cottage, converted property or home with land outside one of the larger settlements may encounter different lender criteria.
Mortgage advice may be useful for:
- first-time buyers;
- home movers;
- remortgages;
- self-employed applicants;
- borrowers with variable or multiple income streams;
- buy-to-let landlords;
- applicants with previous credit problems;
- larger or more complex mortgage requirements;
- rural and non-standard property.
A suitable adviser can compare lender criteria before submitting an application, rather than relying on the headline interest rate alone.
Some borrowers may also prefer advice in another language. Connect Experts allows users to search for bilingual mortgage brokers where available.
Moving to Dumfriesshire
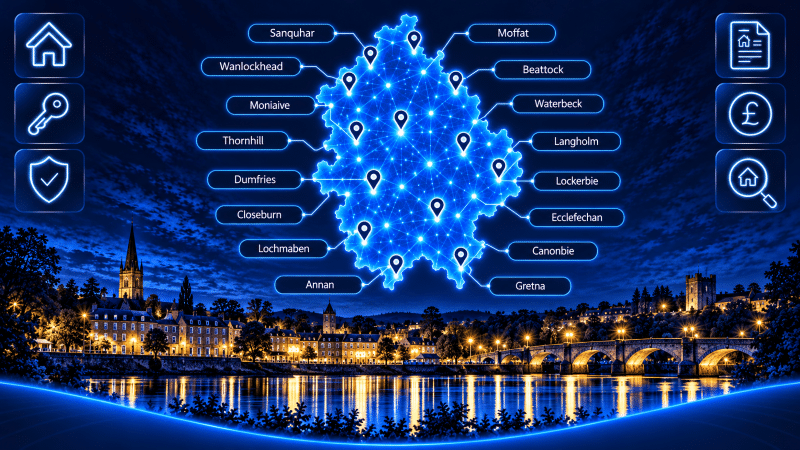
Moving to Dumfriesshire can mean choosing between very different types of locations, from Dumfries and established market towns to smaller villages, rural communities and properties close to the English border.
For mortgage planning, the move itself can affect more than the purchase price. Commuting costs, employment location, childcare, education, existing borrowing and day-to-day household commitments can all influence affordability.
Areas such as Annan, Gretna and Canonbie may appeal to households with cross-border connections, while Lockerbie and Moffat benefit from strong north-south transport links. Dumfries offers the region’s broadest mix of employment, services and housing, while places such as Thornhill, Moniaive and Langholm may involve more rural property characteristics.
Before applying for a mortgage, it can help to review:
- how your income will change after the move;
- whether commuting or travel costs will increase;
- the deposit available after fees and moving costs;
- any childcare or education commitments;
- existing loans, credit cards or mortgages;
- the type, condition and location of the property;
- whether rural features such as land, outbuildings or private access may affect lender criteria.
A move to Dumfriesshire can therefore be as much about understanding the financial impact of the new location as choosing the property itself.
For more local context, read Why Move to Dumfriesshire.
How to Choose a Mortgage Broker in Worcestershire
A useful adviser search starts with your circumstances, not your postcode alone.
Consider asking:
- Does the adviser regularly deal with my type of mortgage?
- Have they worked with applicants whose income is structured like mine?
- Can they advise on rural or unusual property where relevant?
- What range of lenders can they consider?
- What fees will I pay?
- How will they support the application during underwriting?
- Can meetings take place remotely if the adviser is not nearby?
You can use the Connect Experts adviser search to compare mortgage advisers by location and requirements. Connect Experts describes its role as a directory and matching platform, not the provider of mortgage advice itself.
You can also check the relevant firm and permissions through the FCA Financial Services Register.
Local knowledge can help, but specialist experience may matter more when income, credit, borrowing size, or property type falls outside straightforward lender criteria.
Start Your Search for a Mortgage Broker in Dumfriesshire
A mortgage rarely exists separately from the rest of household finances.
The most useful adviser search considers what the mortgage needs to support both today and over the years ahead.
Education
Families moving within Dumfriesshire may need to factor school costs, transport and other education commitments into household budgeting.
Regular education expenditure can affect disposable income and, therefore, mortgage affordability.
Where private education is part of the wider financial plan, Connect Mortgages provides separate guidance on Education Finance.
Finance
Mortgage affordability depends on more than income.
Lenders may consider:
- deposit;
- credit commitments;
- childcare;
- household expenditure;
- existing mortgages;
- property type;
- loan-to-value;
- term;
- income structure.
Someone with straightforward employed income may be assessed differently from a business owner, contractor, farmer or applicant whose earnings vary through the year.
Protection and Longer-Term Planning
The mortgage itself is only one financial commitment.
An adviser may also discuss whether the household has suitable arrangements in place if income is affected by death, serious illness or another major change.
This can include life insurance, critical illness cover, or other protection, depending on individual circumstances.
Assess protection separately, based on its own merits and budget, rather than treating it as an automatic part of arranging a mortgage.
Later-Life Property Decisions in Dumfriesshire
For some older homeowners, the question is no longer how to buy a property but how the value already held within it might support later-life plans.
Options can include remortgaging, downsizing or, for eligible homeowners, considering equity release.
Equity release is a long-term financial commitment and can reduce the value of an estate or affect entitlement to means-tested benefits. It should therefore be assessed separately from conventional mortgage borrowing. Connect Lifetime explains these considerations in its wider equity release guide
Specialist Mortgage Considerations in Worcestershire
High-Net-Worth
Dumfriesshire should not be assumed to be uniformly high-net-worth.
However, larger country houses, estates, land and borrowers with significant assets or complex income can create specialist mortgage requirements.
Applicants whose finances include bonuses, investment income, retained company profits, multiple properties or larger borrowing requirements can explore High Net Worth Mortgage Brokers.
Where larger borrowing or assets create wider protection considerations, information is also available through High Net Worth Protection Services.
People Also Browse these Counties
If you are Looking for a Mortgage Network
“Hi, I’m Liz Syms, Chief Executive Officer and founder of Connect Experts, Connect Mortgages, and Connect for Intermediaries.
If you are a UK mortgage broker based in Dumfriesshire, joining our mortgage network can help you increase your visibility to clients actively searching for trusted, FCA-authorised advice. Brokers featured on our Dumfriesshire mortgage brokers page are matched with clients who value clear communication and professional guidance, including those who prefer advice in a specific language.
Our platform is designed to support compliant, client-focused advisers and help you connect with the right audience across Dumfriesshire.”
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us
Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.