

Finding Mortgage Brokers in Rutland starts with choosing an adviser who understands your borrowing needs and the type of property you plan to buy.
Rutland is England’s smallest historic county, with a distinctive housing market spanning Oakham, Uppingham, Rutland Water and surrounding rural communities. A period townhouse, modern family home or converted agricultural building may each present different mortgage considerations.
Connect Experts helps you compare mortgage advisers by location, specialist knowledge and personal preferences. Whether you are buying your first home, moving, remortgaging or investing in property, the directory provides a practical starting point.
Rutland Property Market and Mortgage Considerations
Rutland combines traditional stone-built properties, village houses, modern developments and individual country homes. Property prices and lender requirements can vary considerably by location and property type.
According to the latest available ONS housing data for Rutland, the average house price was £299,000 in July 2026, provisionally 6.5% below July 2025.
Average house price
£299,000
July 2026, provisional
First-time buyers
£233,000
July 2026, provisional
These figures provide county-wide context, not a valuation for an individual property.
Oakham offers established neighbourhoods, traditional town-centre housing and newer residential developments. Uppingham has a different character, with historic buildings and family housing around its market town.
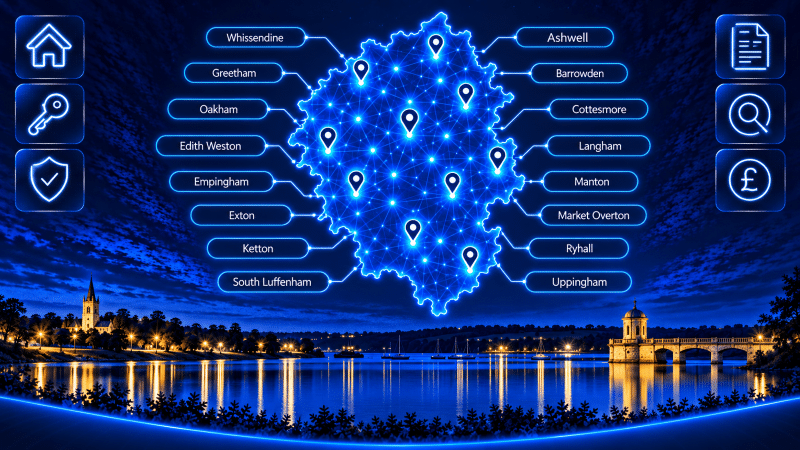
Villages such as Empingham, Edith Weston and Ketton introduce additional rural considerations, including property age, construction, plot size and comparable sales.
For properties requiring specialist valuation, discussing construction and condition with an adviser before applying can help identify suitable lender criteria.
Mortgage Advice Across Rutland
Mortgage advice can be useful at different stages of property ownership.
Some borrowers require straightforward residential mortgages. Others have financial circumstances or properties that need more specialist assessment.
A mortgage adviser may help with:
- First-time buyer deposits and affordability.
- Residential mortgages and home moves.
- Remortgaging and reviewing existing borrowing.
- Self-employed or variable income.
- Buy-to-let properties and rental income.
- Rural homes and non-standard construction.
- Credit history and lender eligibility.
- Larger mortgages and specialist lending.
A Rutland property may require a lender comfortable with traditional construction, while a borrower with several income sources may need an adviser experienced in complex underwriting.
If you would prefer to discuss financial decisions in another language, you can also explore Bilingual Mortgage Brokers.
The most suitable adviser is not necessarily the closest. Relevant experience and lender access can be equally important.
How to Choose a Mortgage Broker in Rutland
Choosing a suitable mortgage adviser involves assessing more than location.
Before selecting an adviser, consider whether their experience matches your financial circumstances and property requirements.
Useful questions include:
- Which lenders can the adviser consider?
- Do they have experience with rural or period properties?
- Can they assess self-employed or irregular income?
- What mortgage and arrangement fees could apply?
- How will they manage the application and lender enquiries?
- Can appointments take place remotely or in person?
You can check the regulatory status and permissions of an adviser or firm through the FCA Financial Services Register.
For borrowers comparing mortgage brokers in Rutland, professional experience, transparent fees and clear communication should guide the decision.
Moving to Rutland: Understanding the Financial Commitment
Rutland offers a largely rural setting, historic market towns and access to neighbouring employment centres.
Oakham has rail connections towards Leicester, Peterborough and other destinations. The A1 runs close to the county’s eastern boundary, while the A47 provides an important route towards Leicester and Peterborough.
For households relocating from larger urban areas, mortgage affordability should reflect Rutland’s full cost of living.
Relevant considerations include:
- Commuting distance and transport costs.
- Household income and employment arrangements.
- Childcare and education expenses.
- Property maintenance and energy costs.
- Existing loans and regular commitments.
- Deposit size and mortgage term.
Older rural homes may require more maintenance, while properties with extensive land or outbuildings may require additional lender checks.
A lender’s maximum borrowing figure should not replace careful household budgeting.
Start Your Search for a Mortgage Broker in Rutland
A successful mortgage application begins with understanding the relationship between property choice, household commitments and longer-term financial plans.
Three considerations can help narrow your adviser search.
Education
Rutland has a strong independent education presence, particularly through Oakham School and Uppingham School.
For households considering fee-paying education, school fees, boarding arrangements and related expenses may affect disposable income and future mortgage affordability.
Education costs are separate from the mortgage, but they remain important when assessing the sustainability of monthly repayments.
Families balancing borrowing and independent-school commitments can explore Education Finance.
Finance
Mortgage lenders assess both income and financial commitments.
Salary, self-employed earnings, dividends, bonuses, existing borrowing and deposit sources can influence mortgage eligibility.
Property type and loan-to-value also affect which lenders you can choose.
An adviser can help identify lending criteria that reflect your circumstances rather than relying solely on headline mortgage rates.
Mortgage Protection and Household Security
A mortgage creates a financial commitment that may continue for many years.
Alongside affordability, it may be sensible to consider how mortgage repayments and household finances would be managed after illness, death, or loss of income.
Depending on individual circumstances, protection discussions may include life insurance, critical illness cover or income protection.
The appropriate level of cover depends on existing benefits, savings, dependants and borrowing commitments.
Specialist Mortgage Considerations in Ruthland
Later-Life Mortgage Considerations in Rutland
Homeowners approaching retirement may have different borrowing priorities.
Some may wish to remortgage, move to a smaller property or review how existing borrowing affects retirement income.
Others may consider later-life mortgages or equity release.
Equity release requires specialist advice because it can affect inheritance, future financial flexibility and entitlement to means-tested benefits.
Borrowers should consider the costs, alternatives and long-term implications before proceeding.
Homeowners considering this route can explore Equity Release Advisers in Ruthland.
High-Net-Worth
Rutland is not uniformly a high-net-worth market. However, larger country homes, substantial detached properties, and individual rural estates may require higher borrowing.
Higher-value borrowing can also involve complex income structures, including investment income, bonuses, partnership earnings, dividends and retained company profits.
Borrowers with these requirements may benefit from advisers experienced in larger mortgages and private-bank lending.
Where appropriate, explore High Net Worth Mortgage Brokers.
Higher mortgage commitments can make wider financial protection especially important. Relevant households can also consider High-Net-Worth Protection Services.
Find Mortgage Brokers Across Rutland
Whissendine Mortgage Advice: The Right Path to Your Next Move
Mortgage Broker in Uppingham: Seek Expert Advice Before You Buy
South Luffenham Mortgage Advice: Look Beyond the Rate
Ryhall Mortgage Advice: Make the Right Move with Confidence
Mortgage Advice in Oakham: Look Beyond the Purchase Price
Manton Mortgage Advice: Expert Mortgage Broker Help – LE15
Mortgage Broker in Market Overton: LE15 Recommended Expert Advice
Mortgage Broker in Langham: Expert Brokers in Rutland – LE15
Ketton Mortgage Advice: Look Beyond the Village Charm
Greetham Mortgage Advice: Get Your Next Move Right in Rutland
Mortgage Broker in Exton: Looking Beyond the Immediate Decision
Empingham Mortgage Advice: Decision On Your Options
Edith Weston Mortgage Adviser: Advice Based on Your Circumstances
Cottesmore Mortgage Advice: The Confidence You Need
Mortgage Broker in Barrowden: Seek Expert Advice Near You
Ashwell Mortgage Advice: Make Every Decision Count
People Also Browse these Counties
If you are Looking for a Mortgage Network
“Hi, I’m Liz Syms, Chief Executive Officer and founder of Connect Experts, Connect Mortgages, and Connect for Intermediaries.
If you are a UK mortgage broker based in Ruthland, joining our mortgage network can help you increase your visibility to clients actively searching for trusted, FCA-authorised advice. Brokers featured on our Ruthland mortgage brokers page are matched with clients who value clear communication and professional guidance, including those who prefer advice in a specific language.
Our platform is designed to support compliant, client-focused advisers and help you connect with the right audience across Ruthland.
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us
Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.