

Finding mortgage brokers in Lanarkshire is partly about location, but the more important question is whether an adviser understands your finances and the property you hope to buy.
Lanarkshire covers contrasting markets across North Lanarkshire and South Lanarkshire. Buyers can encounter affordable first homes, established commuter towns, modern estates, traditional properties and rural homes within the same wider area.
The latest ONS data illustrates the difference. In June 2026, the provisional average house price was £156,000 in North Lanarkshire and £187,000 in South Lanarkshire.
First-time buyers paid an average of approximately £133,000 in North Lanarkshire and £147,000 in South Lanarkshire during the same period.
That difference matters when considering deposit requirements and loan-to-value.
Property choice also changes considerably by location.
A buyer in Airdrie or Coatbridge may be considering a different housing stock and budget from someone purchasing around Hamilton, East Kilbride or the Clyde Valley.
Across Lanarkshire, buyers may encounter:
- traditional terraced and semi-detached homes
- flats and maisonettes
- modern housing developments
- larger detached family homes
- older stone properties
- semi-rural and rural homes
North Lanarkshire’s June 2026 average prices ranged from about £91,000 for flats to £323,000 for detached homes. In South Lanarkshire, the corresponding averages were approximately £105,000 and £388,000.
These are area averages, not property valuations. A lender will assess the individual property alongside the applicant’s circumstances.
Mortgage Advice Across Lanarkshire
A mortgage adviser can assess more than the advertised interest rate.
They may consider:
- your income and employment structure
- deposit and loan-to-value
- existing borrowing and regular commitments
- credit history
- property type and valuation
- mortgage term and repayment method
- lender affordability and underwriting criteria
This can be particularly useful where income is self-employed, comes from several sources, or includes bonuses, overtime, or retained company profits.
Local knowledge can also help when a property raises questions about construction, condition, valuation, or location.
For borrowers who would prefer to discuss detailed financial information in another language, Connect Experts also provides access to mortgage brokers by language.
Lanarkshire appeals to people at very different stages of the property journey.
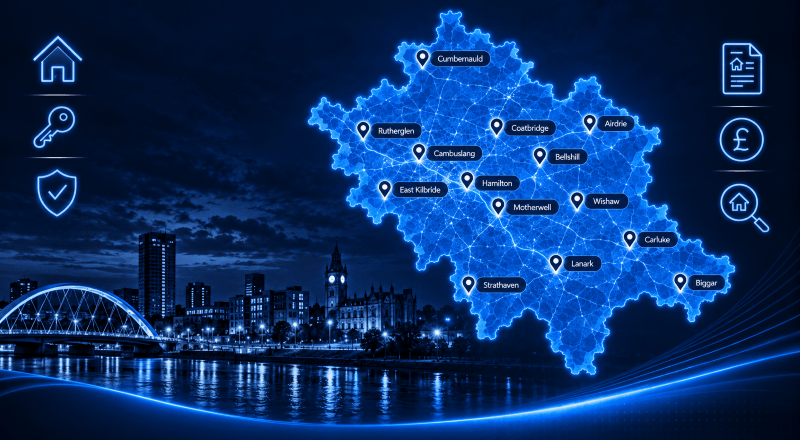
North Lanarkshire includes major centres such as Airdrie, Coatbridge, Cumbernauld, Bellshill, Motherwell and Wishaw. South Lanarkshire includes Hamilton, East Kilbride, Cambuslang, Lanark and communities extending into the Clyde Valley.
Road and rail connections towards Glasgow are important for many commuters. The wider area also includes access to the M8, M73, M74 and M80 corridors.
Buyers should still assess the location at property level.
A commuter may prioritise railway access. A family could place greater weight on space and education. Another buyer may prefer a rural property, where acreage, outbuildings, access or construction could influence valuation and lender criteria.
Mortgage advice should therefore connect the borrower, property and purpose of the loan, rather than rely on postcode alone.
How to Choose a Mortgage Broker in Lanarkshire
The nearest adviser is not automatically the most suitable adviser.
Before choosing a mortgage broker in Lanarkshire, consider whether they regularly deal with your type of mortgage and financial circumstances.
Useful questions include:
- Does the adviser cover the mortgage type I need?
- Do they understand my income structure?
- Can they explain their lender access?
- What fees could apply?
- Can they provide telephone, online or face-to-face appointments?
- Are they comfortable dealing with the property type I am considering?
- Can I check their regulatory position?
You can check firms and individuals through the Financial Services Register provided by the Financial Conduct Authority.
A suitable adviser should clearly explain both the advantages and limitations of any mortgage recommendation.
Start Your Search for a Mortgage Adviser in Lanarkshire
Choosing where to live often means balancing today’s purchase against tomorrow’s commitments.
Education and Household Planning
Families may consider state-school catchments, commuting, childcare or independent education when choosing where to live.
Education costs can affect disposable income and longer-term affordability. Buyers considering private schooling may therefore want to understand how those commitments could interact with future borrowing.
Connect Mortgages provides further information about Education Finance for households considering how school costs could fit into wider financial planning.
Finance and Affordability
Mortgage affordability depends on more than salary.
Lenders can consider expenditure, outstanding credit, dependants, income structure, deposit size and the proposed property.
Existing loans or significant household commitments can reduce borrowing capacity even where income appears strong.
A mortgage adviser can assess these factors before an application reaches underwriting.
Higher-Value and Complex Borrowing
Lanarkshire is not universally a high-value market. However, larger detached properties, rural homes and higher borrowing requirements can create more complex cases.
Applicants may also have:
- investment income
- substantial bonuses
- company profits
- multiple income sources
- significant assets
- larger deposits
- complex business ownership structures
In those circumstances, searching for an adviser with relevant experience through High Net Worth Mortgage Brokers may be useful.
Where larger mortgages create wider family financial commitments, users can also explore High Net Worth Protection Services.
Considering Protection
Taking a mortgage also creates a long-term financial commitment.
Where appropriate, an adviser may discuss whether life cover, critical illness cover, income protection or buildings insurance should form part of the wider financial conversation.
Protection needs depend on individual circumstances and should not be assumed simply because somebody has a mortgage.
A mortgage can last for decades, so the adviser search deserves more thought than simply choosing the nearest name.
Use the Connect Experts Directory to compare advisers by location, mortgage expertise, language and other preferences.
Find a Mortgage Adviser with Connect Experts
Choose the adviser whose experience best reflects your circumstances and the property you are considering.
People Also Browse these Counties
Mortgage Brokers in Midlothian
If you are Looking for a Mortgage Network
“Hi, I’m Liz Syms, Chief Executive Officer and founder of Connect Experts, Connect Mortgages, and Connect for Intermediaries.
If you are a UK mortgage broker based in South Lanarkshire, joining our mortgage network can help you increase your visibility to clients actively searching for trusted, FCA-authorised advice. Brokers featured on our South Lanarkshire mortgage brokers page are matched with clients who value clear communication and professional guidance, including those who prefer advice in a specific language.
Our platform is designed to support compliant, client-focused advisers and help you connect with the right audience across South Lanarkshire.”
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us
Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.