Finding mortgage brokers in Hampshire starts with understanding both your finances and the property you plan to buy.
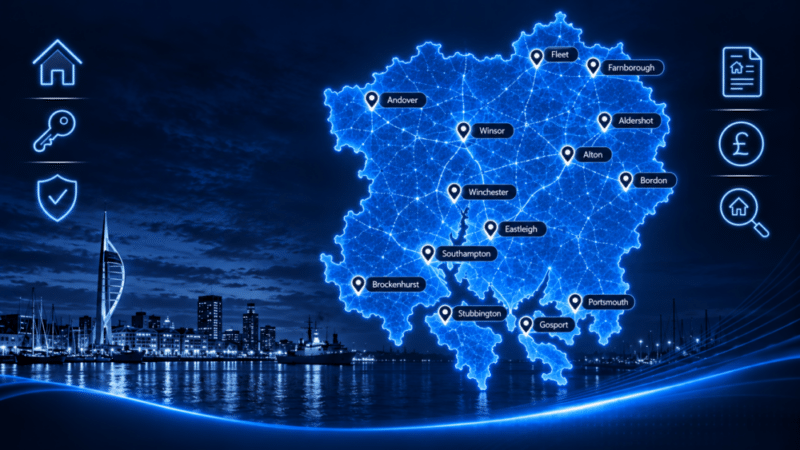
Hampshire contains very different housing markets. Southampton and Portsmouth offer substantial apartment and terrace markets. Winchester sits at a much higher price point. Farnborough, Fleet and Aldershot serve important commuter areas, while Brockenhurst and Winsor offer a different New Forest setting.
These differences can affect deposit requirements, loan-to-value, valuation and lender criteria.
Connect Experts helps you compare mortgage advisers by location, mortgage expertise, language and personal requirements.
Hampshire Property Market and Mortgage Considerations
There is no single Hampshire housing market.
Latest Office for National Statistics housing data shows an average Southampton property price of £236,000 in July 2026. First-time buyers paid an average of £210,000.
In Winchester, the equivalent average was £463,000, while first-time buyers paid £345,000. Detached properties averaged £746,000.
These figures show why a county average gives limited guidance.
Hampshire buyers may encounter:
- Leasehold flats in Southampton and Portsmouth
- Established suburban homes around Eastleigh
- Commuter property in Fleet, Farnborough and Aldershot
- Higher-value housing around Winchester
- Rural and period property around the New Forest
- Coastal housing around Gosport and Stubbington
- Newer development around Bordon
Property type can affect mortgageability as well as price.
Lease terms, service charges, construction, valuation, property condition and resale demand may influence lender underwriting.
Official property statistics provide useful context. They are not mortgage valuations or predictions.
Use the Find a Mortgage Adviser directory to begin your search.
Mortgage Advice Across Hampshire
A mortgage adviser can assess more than the interest rate.
Your circumstances may include:
- Income and employment structure
- Deposit or existing equity
- Credit commitments
- Credit history
- Property type and tenure
- Required mortgage amount
- Loan-to-value
- Existing mortgages
- Longer-term financial commitments
This matters across Hampshire because borrowers can face very different property and affordability profiles.
A Southampton first-time buyer purchasing a flat may need different support from someone buying a detached Winchester home. A purchaser in Brockenhurst may also face property considerations that differ from those in Farnborough or Eastleigh.
Moving to Hampshire
Hampshire combines major cities, market towns, coast, countryside and established commuter areas.
Southampton and Portsmouth provide large employment centres and varied housing. Winchester combines historic property with a higher-value residential market.
Northern Hampshire includes locations such as Fleet, Farnborough and Aldershot, with access towards Surrey and London. The M3 corridor is particularly relevant for buyers balancing housing with commuting.
Further south, the M27 connects communities around Southampton, Eastleigh, Portsmouth and Gosport.
The New Forest creates another distinct market. Brockenhurst and Winsor include countryside and period property that can require closer consideration of construction, land or valuation.
Where you live matters. However, affordability and lender criteria still determine whether a mortgage is suitable.
How to Choose a Mortgage Broker in Hampshire
The closest mortgage broker is not automatically the most suitable.
A practical search should consider three areas.
Relevant mortgage experience
Look for an adviser whose permitted areas match your circumstances.
That may include residential borrowing, remortgaging, buy-to-let, self-employed income or specialist property finance.
Lender access and criteria knowledge
Different lenders can assess the same borrower differently.
Income structure, deposit, property type, credit history and loan size can affect which lenders may consider an application.
Regulation and clear explanations
Before proceeding, check the firm providing the advice.
The FCA Firm Checker confirms whether a firm is authorised and has relevant permissions.
You should also understand any adviser fees, lender fees, repayment terms and important mortgage conditions.
Clear advice should help you understand why a recommendation is considered suitable.
Start Your Search for a Mortgage Adviser in Hampshire
A Hampshire mortgage search can involve more than the purchase price.
Your household plans, income and future commitments can influence what remains affordable over the mortgage term.
Education and household commitments
Hampshire has a wide range of state and independent schools.
Where private education forms part of family planning, fees can affect disposable income and mortgage affordability.
Parents considering these costs can read more about Education Finance.
Consider school costs alongside mortgage payments, household expenditure, and other long-term commitments.
Finance and affordability
Mortgage affordability normally considers the wider household position.
Relevant factors can include:
- Basic and variable income
- Self-employed profits or dividends
- Deposit or equity
- Loans and credit commitments
- Dependants
- Mortgage term
- Property value
- Existing borrowing
An adviser can compare these circumstances with lender criteria before you submit an application.
That can be especially helpful where income includes bonuses, overtime, commissions, contracting or company profits.
Higher-value and complex borrowing
Hampshire should not be treated as uniformly high-value.
However, areas such as Winchester demonstrate that some purchases can involve larger deposits and mortgage requirements. Winchester’s average detached price was £746,000 in July 2026.
Applicants requiring larger loans may also have complex income.
Examples include bonuses, investment income, retained company profits, several income sources or substantial assets.
You can compare High Net Worth Mortgage Brokers when specialist experience matters.
Households with more complex financial arrangements may also wish to consider High Net Worth Protection Services.
A higher property price alone does not define a borrower as high net worth.
Mortgage Protection and Longer-Term Planning
A mortgage creates a long-term household commitment.
Mortgage advice may therefore include discussion about how repayments or household finances could be protected following illness, death or loss of income.
Protection needs depend on personal circumstances. Consider them separately from finding the mortgage itself.
Later-life homeowners may also have different objectives, including downsizing or using property wealth.
Finding a mortgage adviser should begin with your circumstances rather than a postcode alone.
Compare location, relevant mortgage expertise, communication preferences and regulatory information before deciding who to contact.
Use the Connect Experts directory to find a suitable mortgage adviser covering Hampshire.
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it.
People Also Browse these Counties
If you are Looking for a Mortgage Network
“Hi, I’m Liz Syms, Chief Executive Officer and founder of Connect Experts, Connect Mortgages, and Connect for Intermediaries.
If you are a UK mortgage broker based in Hampshire, joining our mortgage network can help you increase your visibility to clients actively searching for trusted, FCA-authorised advice. Brokers featured on our Hampshire mortgage brokers page are matched with clients who value clear communication and professional guidance, including those who prefer advice in a specific language.
Our platform is designed to support compliant, client-focused advisers and help you connect with the right audience across Hampshire.”
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us
Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.