

Finding Mortgage Brokers in Surrey is about more than choosing the adviser closest to your postcode.
Surrey contains very different mortgage markets. A higher-value home around Cobham can raise different lending questions than a flat in Woking, a family house in Epsom or a property close to the North Downs.
Your income, deposit, existing borrowing, property type and longer-term plans all influence which mortgage options may be suitable.
A mortgage adviser can assess those factors before an application reaches a lender. This can make it easier to understand affordability, lender criteria, documentation and potential property-related issues.
Surrey Property Market and Mortgage Considerations
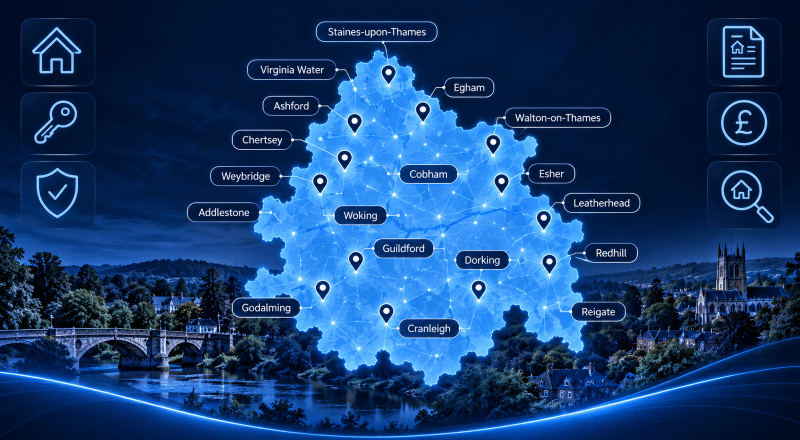
Surrey combines commuter towns, riverside locations, established suburbs, high-value residential areas and communities around the Surrey Hills.
The latest available UK House Price Index for July 2026 puts the Surrey average at approximately £522,523. However, county averages disguise considerable local variation.
For example:
- Elmbridge: approximately £748,080
- Epsom and Ewell: approximately £568,214
- Guildford: approximately £532,917
- Woking: approximately £439,916
These are market indicators, not individual property valuations.
You can review the official figures through the UK House Price Index.
Those differences can influence deposit requirements, borrowing levels and loan-to-value calculations.
Property type also matters. Surrey buyers may encounter:
- leasehold flats around larger town centres;
- higher-value detached homes in parts of Elmbridge;
- period and character properties;
- new-build developments;
- riverside properties;
- rural homes close to protected countryside;
- properties where construction, access or valuation requires closer underwriting.
A lender will assess the individual property as security rather than relying on Surrey’s average value.
Mortgage Advice Across Surrey
A Surrey postcode tells a lender where the property is. It does not tell them whether the mortgage will be suitable.
Lenders can consider income, existing borrowing, deposit, credit history, property value and the type of property being offered as security. A Surrey flat, high-value detached home, rural property or buy-to-let investment may therefore raise different underwriting questions.
This can make mortgage advice particularly useful for:
- First-time buyers entering a relatively high-value market.
- Home movers relocating from London or elsewhere in the South East.
- Self-employed applicants and company directors.
- Borrowers receiving bonuses, commission or investment income.
- Landlords arranging buy-to-let mortgage advice.
- Buyers requiring larger mortgages.
- Applicants purchasing unusual or higher-value property.
When communication preferences matter, users can also search for advisers who offer support in different languages.
Moving to Surrey
Surrey’s relationship with London remains an important part of its housing market.
Woking, Guildford, Epsom and other established towns provide rail connections towards London, while the A3, M25 and wider road network connect different parts of the county.
However, you should not consider commuting separately from mortgage affordability.
A move may change:
- The amount you need to borrow.
- Your monthly mortgage commitment.
- Travel costs.
- School costs.
- Council tax and household expenditure.
- The size of deposit required.
- The type of property you can afford.
Someone moving from London may release substantial equity from an existing property but still face a larger mortgage because of the Surrey property they choose.
Speaking to an adviser before committing to a purchase can provide a clearer view of those numbers.
How to Choose a Mortgage Broker in Surrey
The nearest adviser isn’t automatically the most suitable.
Start by considering the problem you need the adviser to solve.
A straightforward first purchase may require different experience from a seven-figure mortgage using salary, bonuses and retained company profits. Likewise, a landlord may need someone familiar with rental calculations, HMO lending or limited company borrowing.
Before choosing an adviser, consider:
- Whether they advise on the mortgage type you require.
- Whether they understand your income structure.
- Their experience with the relevant property type.
- How they research lender criteria.
- What fees may apply.
- Whether advice is available face-to-face, online or by telephone.
- Whether language support matters to you.
For regulated financial services, you can also check the adviser or firm through the Financial Conduct Authority register.
Start Your Search for a Mortgage Broker in Surrey
A mortgage decision rarely exists on its own. Where you live, how you earn and what your household needs to fund can all influence affordability.
Education
Surrey has a significant independent-school sector.
Surrey County Council’s published education data identifies schools including ACS Cobham International School, Epsom College, Reigate Grammar School, Caterham School, St John’s School and Reed’s School among independent schools serving the county.
For some households, school fees therefore form a meaningful part of regular expenditure.
Those costs should be considered alongside the mortgage, deposit, household spending and longer-term plans. Families considering how property wealth might fit into wider funding arrangements can read about Education Finance.
Education should never be viewed in isolation from affordability.
Finance
Lenders assess more than salary.
Mortgage affordability can be affected by:
- Household commitments.
- Existing loans and credit.
- Deposit size.
- Employment or business income.
- Bonuses and commission.
- Property type.
- Loan-to-value.
- Mortgage term.
- Other properties or mortgages.
The right lender depends on how the whole case fits its criteria, not simply who advertises the lowest rate.
Later-Life Property Wealth in Surrey
Surrey’s property values also mean some older homeowners may hold substantial equity in their homes.
Equity release is not suitable simply because a property has increased in value. Review age, existing secured debt, property eligibility, inheritance plans, future housing needs, and alternatives.
Homeowners considering later-life borrowing can read the specialist guide for Equity Release Advisers in Surrey. The Surrey guide specifically stresses assessing alternatives and the longer-term impact before deciding whether equity release is appropriate.
Equity release can reduce the value of your estate and may affect entitlement to means-tested benefits.
Find a Mortgage Adviser in Surrey
Some Surrey mortgage applications need more specialised consideration.
Higher-value and complex mortgages
Cobham and parts of the wider north Surrey market show why high-value borrowing matters in the county, without suggesting every Surrey borrower is high net worth.
Applicants buying higher-value homes may receive income through salaries, bonuses, dividends, investments, retained company profits or several sources at once.
Different lenders can assess these differently.
Users with larger or more complex requirements can search for High Net Worth Mortgage Brokers.
Where significant property wealth sits alongside wider family or financial commitments, High Net Worth Protection Services may also be relevant.
Start your search for a suitable mortgage adviser in Surrey.
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured against it.
People Also Browse these Counties
If you are Looking for a Mortgage Network
“Hi, I’m Liz Syms, Chief Executive Officer and founder of Connect Experts, Connect Mortgages, and Connect for Intermediaries.
If you are a UK mortgage broker based in Surrey, joining our mortgage network can help you increase your visibility to clients actively searching for trusted, FCA-authorised advice. Brokers featured on our Surrey mortgage brokers page are matched with clients who value clear communication and professional guidance, including those who prefer advice in a specific language.
Our platform is designed to support compliant, client-focused advisers and help you connect with the right audience across Surrey.”
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us
Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.