

Finding mortgage brokers in London is not simply about finding the adviser nearest to your postcode.
London contains many different property markets. A leasehold apartment in Canary Wharf can raise different lending questions from a family house in Bromley or a higher-value property in Kensington.
Your income, deposit, existing commitments and chosen property all influence what may be affordable.
London remains significantly more expensive than most UK housing markets.
The latest available UK House Price Index places the average London property at approximately £554,000 in June 2026. That was 2.5% below June 2025. Flats and maisonettes averaged around £431,000, while detached homes averaged more than £1.16 million.
Those figures hide substantial local differences.
HM Land Registry data for June 2026 placed Barking and Dagenham at around £371,000, while Kensington and Chelsea averaged approximately £1.25 million.
This difference matters because affordability, deposit requirements and required borrowing can change considerably between London locations.
Property type is equally important. London buyers frequently encounter:
- leasehold ownership
- service charges and ground rent
- short or unusual lease terms
- converted houses
- ex-local authority flats
- high-rise blocks
- new-build developments
- shared ownership property
Not every lender assesses these properties in the same way.
The UK House Price Index provides current official London market data.
Mortgage Advice Across London
A London mortgage adviser can assess both you and the property before an application reaches a lender.
This can be particularly valuable where the application involves:
- leasehold flats and maisonettes
- new-build apartments
- properties above commercial premises
- high-rise developments
- self-employed or contractor income
- bonuses, commission or retained company profits
- buy-to-let and portfolio borrowing
- higher-value mortgages
- complex deposits or existing financial commitments
London’s property mix means postcode alone rarely tells the whole story.
A lender may also consider lease length, service charges, building construction, valuation, loan-to-value and local resale demand.
People who would prefer to discuss these matters in another language can also search for a mortgage broker by language.
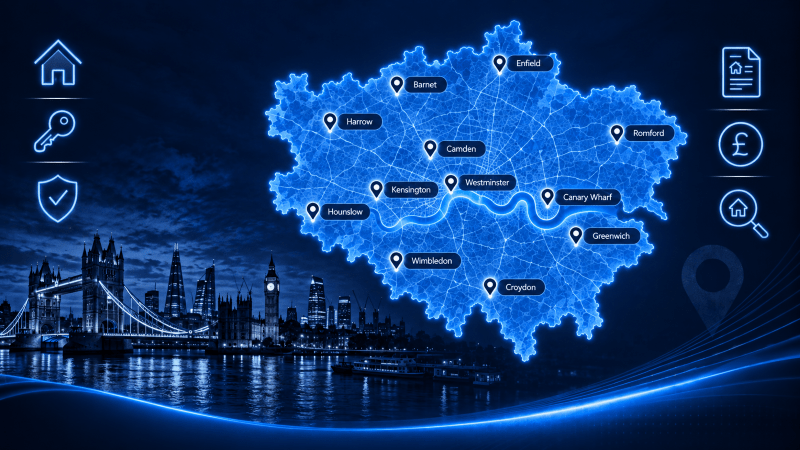
Central London offers access to major employment districts, universities, cultural attractions and extensive public transport. Areas such as Westminster, Kensington and Chelsea, Camden and the City can provide shorter journeys to key business districts, but property prices and service charges may be considerably higher.
Outer London boroughs can offer a different balance. Areas such as Bromley, Croydon, Barnet, Enfield and Havering may provide larger homes, more suburban surroundings and access to green space while retaining transport links into central London.
East London includes major regeneration areas and newer developments, while west and south-west London combine established residential neighbourhoods with strong rail and Underground connections. Buyers may also find significant differences between leasehold flats, period conversions, new-build apartments and freehold houses.
When deciding where to live in London, practical considerations can include:
- Journey time to work.
- Underground, rail and bus connections.
- School catchment areas.
- Local amenities and green space.
- Leasehold service charges and ground rent.
- Parking and permit restrictions.
- Property maintenance costs.
- Council tax and wider household expenses.
These factors can affect both the cost of buying and how comfortable the mortgage remains after completion. A property that appears affordable on purchase price alone may carry higher ongoing costs depending on its location, tenure and building type.
How to Choose a Mortgage Broker in London
The nearest broker isn’t automatically the most suitable.
A more useful approach is to compare advisers based on your circumstances and the transaction you’re considering.
Before choosing an adviser, consider:
- Mortgage expertise: Does the adviser regularly handle your type of mortgage?
- Property experience: Are they familiar with flats, new builds, investment properties or higher-value borrowing?
- Income: Can they assess salary, self-employed income, bonuses, commission or retained profits?
- Lender access: How broad is the range of lenders they can consider?
- Fees: What might you pay and when?
- Communication: Can meetings take place by telephone, video or face to face?
- Language: Can the adviser explain important mortgage information in your preferred language?
- Regulation: Is the adviser or firm appropriately authorised for the advice required?
For regulated residential mortgages, affordability and suitability remain central considerations. The Financial Conduct Authority’s mortgage information explains the regulatory framework consumers should expect.
A suitable adviser should help you understand the complete borrowing arrangement rather than concentrating only on the advertised interest rate.
Start Your Search for a Mortgage Adviser in London
A mortgage decision becomes clearer when the property, borrowing requirement and wider household finances are considered together.
Education and Household Planning
London provides extensive state and independent education choices.
For households considering independent schooling, fees can form a significant ongoing commitment. These costs may affect disposable income, mortgage affordability and longer-term financial planning.
Families who want to consider the wider funding implications can read about Education Finance.
Education should therefore be considered alongside the mortgage, not after the property decision has been made.
Income, Deposit and Existing Finance
Mortgage affordability normally considers more than salary.
An adviser may need to understand:
- household income
- deposit size and source
- loans and credit commitments
- childcare costs
- property tenure
- service charges
- bonus or commission income
- self-employed earnings
- rental commitments or investment properties
Clear information helps an adviser identify suitable lender criteria before submitting an application.
Higher-Value London Property
London has some of Britain’s highest-value residential markets, particularly in areas such as Kensington and Chelsea, Westminster, parts of Richmond, Hampstead, and Central London.
Higher property values do not automatically complicate a mortgage. However, larger borrowing requirements may coincide with bonuses, investment income, dividends, retained profits, overseas income or more complex ownership arrangements.
In these circumstances, users may wish to explore High Net Worth Mortgage Brokers.
Larger financial commitments can also increase the importance of protecting household income and liabilities. Relevant users can explore High Net Worth Protection Services.
This does not mean every London borrower requires specialist advice. The appropriate approach depends on the borrower, property and amount being financed.
Mortgage Protection and Your Wider Plan
A mortgage may remain in place for many years.
For some households, mortgage planning will therefore include a discussion about life insurance, critical illness cover, income protection or other appropriate protection.
The purpose is not simply to secure borrowing. It is to consider what could happen to the mortgage and household finances if circumstances change.
Any protection recommendation should reflect individual needs, existing cover and affordability.
Later-Life Property Finance in London
London’s higher property values can also mean some older homeowners hold substantial equity within their homes.
Later-life borrowing is different from a standard residential mortgage and should be considered carefully.
Homeowners exploring this route can read about Equity Release Brokers in London.
Equity release reduces the value of your estate and may affect entitlement to means-tested benefits. Consider alternatives, costs, and long-term consequences before proceeding.
Every mortgage begins with numbers, but the decision behind those numbers is personal.
The right question is not simply, “Who is the closest mortgage broker?”
It is whether an adviser understands your income, property, priorities and the lender criteria that apply.
Use the Connect Experts directory to compare advisers covering London and choose a professional whose experience matches your needs.
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it.
People Also Browse these Counties
If you are Looking for a Mortgage Network
“Hi, I’m Liz Syms, Chief Executive Officer and founder of Connect Experts, Connect Mortgages, and Connect for Intermediaries.
If you are a UK mortgage broker based in London, joining our mortgage network can help you increase your visibility to clients actively searching for trusted, FCA-authorised advice. Brokers featured on our London mortgage brokers page are matched with clients who value clear communication and professional guidance, including those who prefer advice in a specific language.
Our platform is designed to support compliant, client-focused advisers and help you connect with the right audience across London.”
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us
Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.