
Mortgage Brokers in County Londonderry can help turn a property choice into a financial decision built for real life.
A home can be chosen with the heart. A mortgage must still work with income, expenditure, property condition and future plans.
County Londonderry makes that distinction particularly important.
The historic county stretches from Derry~Londonderry and the River Foyle to Limavady, Coleraine, Portstewart, Magherafelt and rural communities.
That creates a varied housing market. Buyers may consider city terraces, coastal homes, newer developments, rural houses, apartments or substantial detached properties.
Connect Experts helps you compare advisers by location, mortgage expertise and personal preferences.
You can also explore our Why Move to County Londonderry guide for wider information about living, property and lifestyle in the county.
County Londonderry Property Market and Mortgage Considerations
A county boundary tells you where a property stands. It does not tell a lender everything it needs to know.
Historic County Londonderry crosses parts of several modern local government districts. These include Derry City and Strabane, Causeway Coast and Glens, and Mid Ulster.
For that reason, there is no responsible single official house-price figure covering the historic county.
Northern Ireland Statistics and Research Agency data recorded a standardised Northern Ireland house price of £202,487 in Q2 2026. That represented annual growth of 9.2%.
Within areas relevant to County Londonderry, Q2 2026 standardised prices were:
- Derry City and Strabane: £189,474
- Causeway Coast and Glens: £218,871
- Mid Ulster: £195,453
These are broad market indicators rather than individual property valuations.
A property in Portstewart may therefore raise different questions from a terrace in Derry or a rural home near Draperstown.
Lenders can consider:
- property value;
- construction;
- condition;
- tenure;
- access;
- land and outbuildings;
- intended use;
- marketability;
- deposit size;
- borrower income;
- credit history.
Historic property also needs care.
Derry City and Strabane District Council identifies conservation areas including the Historic City, Clarendon Street and Magee areas.
Conservation status does not automatically prevent mortgage lending.
However, alterations, condition, planning history and valuation can become more important.
The lesson is simple. A postcode starts the mortgage conversation. The property itself often determines where that conversation goes.
How to Choose a Mortgage Broker in County Londonderry
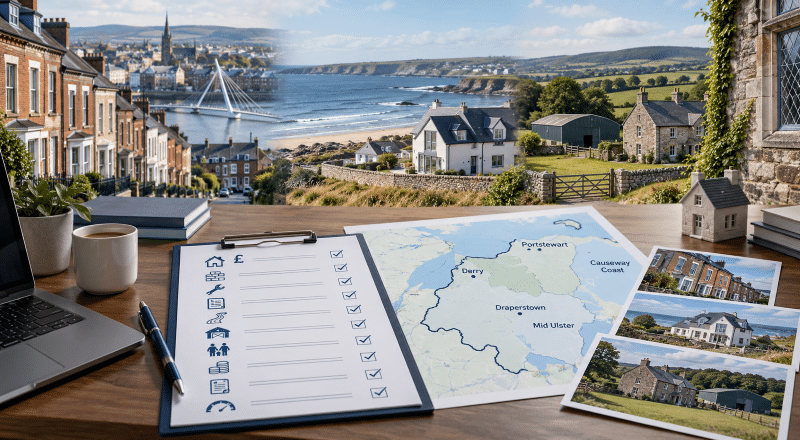
Choosing an adviser is not simply a search for somebody nearby.
It is a search for somebody who understands the financial problem you need to solve.
Before selecting an adviser, ask:
- Which lenders can you consider?
- Do you regularly deal with my type of mortgage?
- Have you handled rural or unusual properties?
- Can you assess self-employed or company-director income?
- What fees apply?
- When are those fees payable?
- How will you communicate during the application?
- Can meetings take place remotely?
- Who deals with lender queries after submission?
- Do you provide protection advice?
For regulated mortgage advice, check the adviser or firm through the FCA Financial Services Register.
The best adviser is not necessarily the person closest to the property.
Experience, lender access, transparency and communication can matter just as much.
Mortgage Advice Across County Londonderry
Mortgage Brokers in County Londonderry may support borrowers at very different stages of property ownership.
Some clients need an ordinary residential mortgage.
Others need a lender willing to understand circumstances that do not fit a standard application.
Advice may be useful for:
- first-time buyers;
- home movers;
- remortgage clients;
- self-employed applicants;
- company directors;
- contractors;
- landlords;
- portfolio landlords;
- borrowers with credit problems;
- buyers of unusual properties;
- larger mortgage applications;
- commercial property;
- later-life borrowing.
The correct mortgage does not begin with the lowest advertised rate.
It begins with eligibility.
A competitive rate has little value when the lender will not accept the income, property or borrowing structure.
County Londonderry also has different property environments within a relatively small geographic area.
Derry~Londonderry contains established urban housing and historic buildings.
Coleraine can attract homeowners, students and landlords.
Portstewart and Castlerock introduce coastal and second-home considerations.
Limavady connects town living with rural and coastal communities.
Magherafelt and surrounding areas include family homes, business owners and applicants with varied income structures.
If communication in another language matters, explore Bilingual Mortgage Brokers.
Specialist Mortgage Considerations in County Londonderry
Mortgage Brokers in County Londonderry should be compared against the life attached to the borrowing.
Property is only one part of that picture.
Three areas deserve particular thought.
Education
Where children learn can influence where families choose to live.
County Londonderry includes grammar, integrated, maintained and other education options across Derry, Coleraine, Magherafelt and surrounding communities.
The county also has independent education.
For example, the Independent Schools Council lists OneSchool Global UK Knockloughrim Campus in County Londonderry. It provides education for pupils aged 7 to 18.
Families considering fee-paying education should include those costs when judging future mortgage affordability.
School expenditure can involve far more than tuition.
Transport, uniforms, activities, equipment and future fee increases can all affect household cash flow.
Where property-backed borrowing is being considered to address education costs, explore Education Finance.
Education should create possibilities for a child. Funding it should not quietly weaken the household supporting them.
Later-Life Mortgage Considerations in County Londonderry
Homeownership changes meaning over time.
A property may begin as somewhere to raise a family. Decades later, it may represent a large part of retirement wealth.
Older homeowners in County Londonderry may consider:
- remortgaging;
- moving home;
- downsizing;
- retirement interest-only borrowing;
- later-life mortgages;
- lifetime mortgages;
- equity release.
The right route depends on income, age, property, existing borrowing and future plans.
Someone living in a larger rural property may want to downsize.
A homeowner in Derry may wish to remain close to family.
A coastal homeowner may want to preserve the property for inheritance.
Others may want to release part of their housing wealth.
Equity release requires specialist regulated advice.
It can reduce an estate’s value and may affect entitlement to means-tested benefits.
Alternatives should therefore be considered before a recommendation is made.
For dedicated later-life support, see Equity Release Advisers in County Londonderry.
Tomorrow’s housing needs matter when choosing today’s borrowing.
High-Net-Worth
County Londonderry is not a uniformly high-value market.
That would oversimplify it.
However, some borrowers and properties can still create high-net-worth or larger-loan requirements.
Examples may include:
- substantial detached properties;
- higher-value coastal homes;
- larger homes around desirable residential areas;
- rural homes with significant land;
- business owners with complex income;
- borrowers using investment income;
- directors retaining profits within companies;
- applicants with several properties.
Portstewart can be particularly relevant where coastal property values, second homes and investment demand increase borrowing requirements.
Larger homes around Derry, Culmore and other established residential areas may also create substantial mortgage needs.
However, property value alone does not make somebody a high-net-worth borrower.
The financial structure matters.
A £1 million mortgage supported by salary creates a different underwriting case from borrowing supported by dividends, investment income and company profits.
Clients requiring specialist larger-loan advice can explore High Net Worth Mortgage Brokers.
Where substantial assets and borrowing create wider family risks, also consider High-Net-Worth Protection Services.
Wealth can create more options. It can also create more moving parts.
Good advice should understand both.
Finance in County Londonderry: Planning Beyond
Finance
Income tells a lender part of the story.
How that income is earned can change the rest.
County Londonderry borrowers may include:
- salaried employees;
- contractors;
- sole traders;
- company directors;
- agricultural businesses;
- professionals;
- landlords;
- business owners;
- applicants with investment income.
A lender may assess salary differently from dividends.
Lenders may treat retained profits differently.
Bonuses, commission and overtime may require a history.
Rental income has separate criteria.
Applicants working across Northern Ireland and the Republic of Ireland can also require careful assessment where income or financial commitments cross currencies or jurisdictions.
An adviser can help identify lenders whose criteria reflect the real structure of the applicant’s finances.
Mortgage Protection and Household Security
Buying a home creates an asset.
It also creates an obligation.
That obligation can remain even when life changes unexpectedly.
A mortgage and protection discussion may therefore consider:
- life insurance;
- critical illness cover;
- income protection;
- family income benefit;
- mortgage payment protection.
The appropriate cover depends on the household.
Someone with significant savings may have different requirements from a family relying on one main income.
Self-employed people may also have different employer benefits from salaried workers.
The purpose is not to insure everything.
It is to identify which financial risks the household could not comfortably absorb.
You can compare Protection Mortgage Brokers for specialist protection advice.
Specialist Mortgage Considerations in County Londonderry
Some mortgages become more complicated because of the borrower.
Others become complicated because of the property.
County Londonderry can present both.
Areas worth discussing before applying may include:
Rural property
Homes with acreage, agricultural connections, private access, outbuildings or unusual services can require extra lender checks.
Historic property
Older buildings may require closer consideration of construction, repairs and previous alterations.
Coastal property
Homes around Portstewart and Castlerock can appeal to homeowners, landlords and holiday-let investors. Intended use matters because residential, buy-to-let and holiday-let criteria differ.
Student property
Derry~Londonderry and Coleraine have university populations. A standard buy-to-let, student let or HMO can each require different lending and regulatory considerations.
Self-employed income
Farming, tourism, hospitality, trades and local businesses can create variable or seasonal income.
Commercial use
A home containing significant business use, commercial premises or mixed-use accommodation may fall outside ordinary residential criteria.
Describe the property accurately from the beginning.
Trying to make an unusual case appear ordinary rarely improves the mortgage application.
Find Mortgage Brokers Across County Londonderry
Portstewart Mortgage Advice: Make Your Coastal Move Count
Mortgage Broker in Magherafelt: Expert BT45 Mortgage Advice
Maghera Mortgage Advice: Strong Choices Start With Local Detail
Limavady Mortgage Advice: Strong Ground for Your Next Move
Kilrea Mortgage Advice: Make the Right Move from the Start
Garvagh Mortgage Advice: Make the Property Fit the Plan
Eglinton Mortgage Advice: A Clearer Route to Your Next Home
Advisers in Dungiven: Expert Advice Over the Phone
Draperstown Mortgage Advice: Clarity Before Commitment
Mortgage Broker in Derry: Make Your Next Move Count
Coleraine Mortgage Advice: Think of a Decision in Principal
Mortgage Advice in Claudy: Make the Property Fit the Plan
Mortgage Broker in Castlerock: Make the Coast Part of the Plan
Mortgage Broker in Castledawson: Always Expert Advice
Bellaghy Mortgage Advice: Take in Every Advice
Ballykelly Mortgage Advice: Make Your BT49 Move Count
People Also Browse these Counties
A Mortgage Network for Advisers Serving County Londonderry
A strong adviser network should help brokers become more visible without losing sight of its purpose: connecting the right client with the right expertise.
If you are a UK mortgage broker covering County Londonderry, joining the Connect network can help you reach clients actively searching by location, mortgage requirement and language.
The platform is designed around compliant, client-focused advice and allows consumers to look beyond a generic list of brokers to find somebody whose experience reflects their needs.
For advisers seeking network support, compliance infrastructure and greater consumer visibility, explore Connect for Intermediaries and its mortgage network.
The aim is not simply to appear in more searches.
It is to be found by the people you are genuinely equipped to help.
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us
Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.