

Finding Mortgage Brokers in Lincolnshire is not simply about choosing the adviser nearest to your postcode.
A suitable adviser should understand your income, deposit, property, borrowing requirements and lender criteria. They can then help you assess mortgage options that fit your circumstances.
Connect Experts helps you compare mortgage advisers covering Lincolnshire by location and mortgage expertise.
A mortgage adviser may help you:
- Assess how much you may be able to borrow.
- Review deposit and loan-to-value requirements.
- Compare suitable mortgage products and lender criteria.
- Present employed, self-employed or complex income correctly.
- Understand property-related lending requirements.
- Prepare documents before submitting an application.
- Deal with valuation or underwriting questions.
- Consider protection alongside your mortgage where appropriate.
Lincolnshire Property Market and Mortgage Considerations
Lincolnshire does not have one uniform property market.
The provisional UK House Price Index recorded an average Lincolnshire property price of about £219,000 in July 2026. However, local figures show clear variation. Lincoln averaged about £187,000, while South Kesteven averaged around £260,000. Boston was approximately £177,000.
Review the latest UK House Price Index data
These figures are county and local-authority averages, not individual property valuations.
They do show why affordability and lender requirements can differ across Lincolnshire.
For example:
- Lincoln includes apartments, terraces, period property and newer developments.
- South Kesteven includes Grantham, Stamford and higher-value rural housing.
- East Lindsey combines market towns, villages and coastal communities.
- Boston and the surrounding area generally sit at a lower price point than parts of South Kesteven.
- Rural homes may include land, private drainage, outbuildings or non-standard construction.
An adviser can help you determine whether the property and your finances meet a lender’s criteria before you submit a full application.
Mortgage Advice Across Lincolnshire
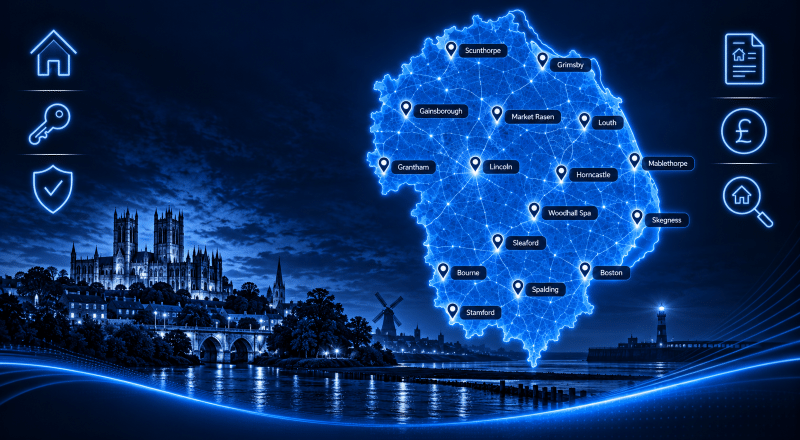
Lincolnshire covers very different housing markets.
Someone buying a flat or terrace in Lincoln may have different mortgage requirements from someone purchasing a rural cottage near Louth or Market Rasen.
Coastal property around Skegness and Mablethorpe can raise different valuation, insurance or property-use questions. Homes with land, outbuildings or unusual construction may also require more detailed lender assessment.
A mortgage adviser can consider both sides of the application: the borrower and the property.
That may be particularly valuable if you are:
- Buying your first home.
- Moving within Lincolnshire.
- Remortgaging.
- Self-employed or receiving variable income.
- Buying a rural or unusual property.
- Considering buy-to-let or specialist lending.
Moving to Lincolnshire
Lincolnshire offers a combination of city living, market towns, agricultural communities, countryside and coastline.
Transport options also vary considerably.
Grantham sits on the East Coast Main Line and provides strong north-south rail connections. Lincoln has regional and London services, while the A1 serves the western side of the county.
Elsewhere, routes including the A15, A16, A17, A46 and A52 connect Lincolnshire’s towns, villages and coastal areas. Rural locations may involve greater reliance on road travel.
Before choosing a property, consider the wider monthly cost of living there, including:
- Mortgage repayments.
- Commuting.
- Council tax.
- Insurance.
- Energy costs.
- Service charges where applicable.
- Property maintenance.
- Future household commitments.
You can also read the Connect Experts guide to moving to Lincolnshire.
How to Choose a Mortgage Broker in Lincolnshire
A good adviser match depends on more than distance.
Consider whether the adviser has suitable experience for:
- Your income structure.
- The mortgage type you need.
- Your chosen property.
- Complex or specialist lender criteria.
- The amount you need to borrow.
- Your preferred way of communicating.
You should also understand their fees, the lenders they can consider, and how they will deliver advice.
If required, you can check regulatory details independently through the Financial Conduct Authority.
Check the Financial Services Register
Clear communication can be particularly important when discussing affordability, mortgage terms and legal or financial documents.
Start Your Search for a Mortgage Adviser in Lincolnshire
A mortgage is usually easier to assess once you consider your wider financial position.
Education and Household Commitments
Families may need to account for childcare, university planning or independent school fees alongside their mortgage.
Lincolnshire and its surrounding area include independent education options in places such as Lincoln and Stamford.
Education costs can become an important part of long-term affordability. Where suitable, homeowners may wish to understand whether Education Finance could form part of their planning.
Borrowing against a property increases secured debt and should be considered carefully.
Finance and Affordability
Mortgage affordability can be affected by:
- Income and employment structure.
- Deposit or existing equity.
- Credit commitments.
- Dependants.
- Loan term.
- Property type.
- Existing mortgages or other borrowing.
Different lenders can assess the same circumstances differently. Specialist advice may help when an application does not fit standard criteria.
Higher-Value and Complex Borrowing
Lincolnshire is not uniformly a high-value market. However, larger or higher-value properties can be found around Stamford, parts of South Kesteven and selected rural locations.
Clients with substantial borrowing requirements, investment income, bonuses, retained company profits or several income sources may benefit from a High Net Worth Mortgage Broker.
Where the mortgage forms part of a wider financial arrangement, suitable High Net Worth Protection Services may also be worth considering.
Protection discussions can include how mortgage commitments or household finances might be affected by death, illness or loss of income. Suitability will depend on individual circumstances.
Older homeowners considering later-life borrowing can explore Equity Release Advisers in Lincolnshire separately.
A mortgage brings together your income, deposit, property, lender criteria and plans for the years ahead.
The most useful adviser is therefore not always the person nearest to you. It is someone whose experience and permissions suit your circumstances.
Use Connect Experts to compare advisers covering Lincolnshire and choose a suitable mortgage professional for your needs.
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it.
People Also Browse these Counties
If you are Looking for a Mortgage Network
“Hi, I’m Liz Syms, Chief Executive Officer and founder of Connect Experts, Connect Mortgages, and Connect for Intermediaries.
If you are a UK mortgage broker based in Lincolnshire, joining our mortgage network can help you increase your visibility to clients actively searching for trusted, FCA-authorised advice. Brokers featured on our Lincolnshire mortgage brokers page are matched with clients who value clear communication and professional guidance, including those who prefer advice in a specific language.
Our platform is designed to support compliant, client-focused advisers and help you connect with the right audience across Lincolnshire.”
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us
Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.