

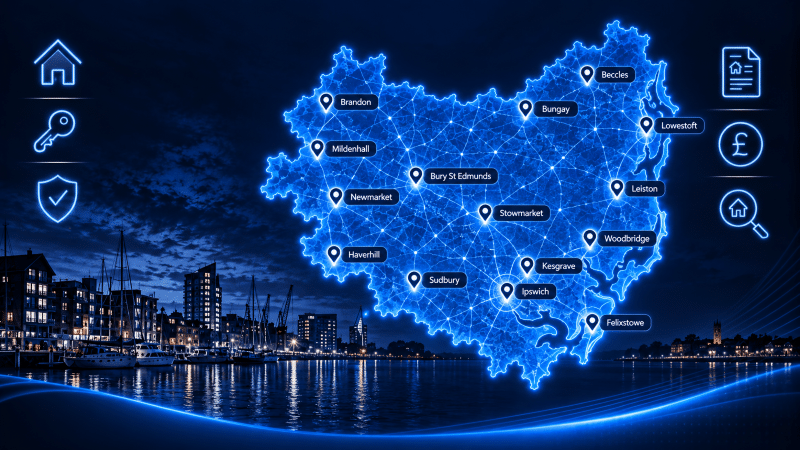
Finding the right mortgage brokers in Suffolk starts with understanding more than where an adviser is based.
Suffolk includes Ipswich, historic market towns, rural villages and coastal communities. Property values, housing types and borrowing requirements can therefore vary considerably across the county.
A mortgage adviser can assess your income, deposit, existing commitments and intended property before identifying lenders whose criteria may fit your circumstances.
They may help you:
- Understand how much you may be able to borrow
- Review deposit and affordability requirements
- Compare mortgage options from an extensive range of lenders
- Understand lender criteria for your chosen property
- Present employed, self-employed or complex income correctly
- Prepare documents before applying
- Understand valuation and underwriting requirements
- Review mortgage costs and longer-term commitments
Suffolk Property Market and Mortgage Considerations
Suffolk is not one uniform housing market.
The latest provisional ONS figures for July 2026 show average house prices of approximately:
- £331,000 in Babergh
- £316,000 in Mid Suffolk
- £295,000 in West Suffolk
- £276,000 in East Suffolk
- £221,000 in Ipswich
These are local-authority averages, not valuations for individual homes. The ONS also warns that local figures can be more volatile because they are based on fewer transactions.
View the latest ONS housing market data
That variation matters when arranging a mortgage.
A buyer in Ipswich may require a different deposit and borrowing level from someone buying in Babergh or rural Mid Suffolk. Coastal homes, older properties, flats and properties with land can also introduce different valuation or lender criteria.
The useful question, then, is not simply, “What is the average Suffolk house price?”
Mortgage Advice Across Suffolk
A postcode tells an adviser where the property is. It does not explain the whole mortgage case.
Buying a flat in Ipswich can produce different lending considerations from purchasing a period property in Bury St Edmunds, a rural home in Mid Suffolk or a coastal property around Lowestoft and Felixstowe.
Mortgage lenders can consider factors including:
- Income and employment structure
- Deposit and loan-to-value
- Existing credit commitments
- Property value and condition
- Freehold or leasehold tenure
- Construction type
- Intended property use
- Affordability under the lender’s own criteria
For borrowers whose income comes from a company, investments, bonuses or several sources, lender selection can become particularly important.
If communicating about detailed financial information in another language would help, Connect Experts also lets you search for bilingual mortgage brokers.
How to Choose a Mortgage Broker in Suffolk
The nearest mortgage adviser is not necessarily the adviser best suited to your circumstances.
Before choosing someone, consider:
- Their experience with your type of mortgage
- Whether they understand your income structure
- Their knowledge of the property type involved
- Which lenders they can consider
- How their fees work
- Whether they offer remote, telephone or face-to-face advice
- Their regulatory status
You can independently check regulated firms and individuals through the Financial Services Register.
Connect Experts lets you compare advisers by location, language, and mortgage expertise before deciding who to contact.
Moving to Suffolk
Moving to Suffolk can mean very different things depending on where you settle.
Ipswich provides an urban property market with rail links towards London. Towns such as Bury St Edmunds, Stowmarket and Newmarket serve different parts of the county, while East Suffolk includes coastal locations such as Felixstowe and Lowestoft.
Your mortgage planning should therefore consider more than the purchase price.
Practical costs can include:
- Mortgage repayments
- Commuting and transport
- Council tax
- Insurance
- Maintenance
- Leasehold or service charges where relevant
- Education costs
- Existing borrowing
- Future household commitments
A suitable adviser can consider these costs alongside lender affordability rather than looking at the property price alone.
For a broader look at the county, read Why Move to Suffolk.
Start Your Search for a Mortgage Broker in Suffolk
Finding a mortgage broker in Suffolk should start with your circumstances, not just your postcode.
Connect Experts lets you compare advisers who cover Suffolk by location, mortgage expertise, and other search preferences.
Education and Mortgage Planning
Education can factor into long-term household affordability.
Suffolk has established independent education options in and around Ipswich, Woodbridge and Bury St Edmunds. Woodbridge School, for example, operates as an independent day and boarding school in the county. Woodbridge School
For households already paying school fees, or planning for future independent education, those costs can affect disposable income and mortgage affordability.
Depending on individual circumstances, homeowners may also want to understand whether education finance could form part of their wider financial planning.
Possible routes may include remortgaging, further borrowing or other secured finance. Borrowing against a home will not suit every household, so consider the cost, term, and effect on wider finances carefully.
Finance and Affordability
Affordability is about more than salary.
Lenders may assess regular expenditure, credit commitments, dependants, deposit size, loan-to-value, property type, and how income is earned.
Two households buying similarly priced Suffolk properties may therefore receive different lending outcomes.
The objective of advice is to understand which lender criteria fit the actual case rather than making assumptions from income or postcode alone.
High-Net-Worth Mortgage Requirements in Suffolk
Some Suffolk mortgage requirements sit outside standard affordability models.
Higher-value property purchases, larger loans or clients receiving bonuses, dividends, retained company profits, investment income or overseas earnings may require a more detailed assessment.
A high-net-worth mortgage broker can consider how income, assets, liabilities and the proposed property work together.
This should not be interpreted as describing Suffolk as a high-net-worth market overall. It is relevant where the individual borrower, property value or financial structure requires specialist underwriting.
Clients with substantial borrowing, business interests or wider family responsibilities may also wish to consider whether their existing arrangements provide suitable financial protection. Connect Experts provides access to advisers who can discuss High-Net-Worth Protection Services where relevant.
Mortgage Protection and Your Wider Plans
Taking a mortgage creates a long-term financial commitment.
Alongside arranging the borrowing itself, some households may want to consider how mortgage repayments or wider family finances would be affected by death, serious illness or loss of income.
Protection needs vary by household, mortgage and existing cover. They should therefore be considered individually rather than treated as an automatic addition to every mortgage.
Equity Release in Suffolk
For some older homeowners, the mortgage conversation may be different.
A property that has increased in value over many years may form part of later-life financial planning. Eligible homeowners can explore whether a lifetime mortgage or another later-life borrowing route may be appropriate.
Suffolk properties can include rural homes, coastal properties, cottages and homes with land. Those characteristics can affect provider criteria and valuation.
Homeowners considering this route can read the Equity Release Adviser in Suffolk guide.
Equity release is a long-term commitment. It can reduce your estate’s value and may affect entitlement to means-tested benefits.
Find a Mortgage Adviser in Suffolk
A mortgage brings together the borrower, property, deposit, lender criteria and plans for the years ahead.
That makes finding the right expertise more useful than simply choosing the nearest postcode.
Find a Mortgage Adviser through Connect Experts and compare advisers across Suffolk based on the support you need.
Your home may be repossessed if you do not keep up repayments on your mortgage or other loans secured against it.
People Also Browse these Counties
If you are Looking for a Mortgage Network
“Hi, I’m Liz Syms, Chief Executive Officer and founder of Connect Experts, Connect Mortgages, and Connect for Intermediaries.
If you are a UK mortgage broker based in Suffolk, joining our mortgage network can help you increase your visibility to clients actively searching for trusted, FCA-authorised advice. Brokers featured on our Suffolk mortgage brokers page are matched with clients who value clear communication and professional guidance, including those who prefer advice in a specific language.
Our platform is designed to support compliant, client-focused advisers and help you connect with the right audience across Suffolk.”
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us
Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.