
Mortgage Broker in Biddenham Turn searches often begin with a property, but the real decision usually involves much more than its asking price.
On this particular road, that distinction matters.
Biddenham Turn sits between Biddenham’s established village character and the western edge of Bedford. Bedford Borough Council describes this approach as having large detached houses set within generous plots, with trees, hedging and grass verges forming part of its character.
Recent transactions also show why mortgage advice here can require a different approach from the wider Bedford market. Individual properties on Biddenham Turn have changed hands for more than £1 million.
For buyers, existing owners and families considering their next move, the question is therefore not simply whether a lender offers a competitive rate. It is whether that lender is comfortable with the loan size, property, deposit and applicant’s overall financial position.
Biddenham Turn Is Not the Typical Bedford Property Market
The wider Bedford market provides useful context.
According to the Office for National Statistics housing data for Bedford, the average Bedford house price was approximately £330,000 in June 2026. First-time buyers paid an average of about £272,000, while mortgage-funded purchases averaged around £327,000.
Biddenham Turn operates at a noticeably different level.
Land Registry-derived transaction data records:
- 21 Biddenham Turn: £1,200,000 in May 2025
- 29 Biddenham Turn: £1,380,000 in February 2025
- 30 Biddenham Turn: £1,025,000 in February 2024
- 28 Biddenham Turn: £1,265,000 in July 2022
The available transaction record predominantly relates to detached property.
These figures should not be treated as a valuation for another home. Individual properties can vary substantially by plot, condition, size, specification and exact position.
However, they show why someone seeking mortgage advice in Biddenham Turn may need an adviser comfortable with larger mortgages and higher-value property.
For comparison, sold properties across Biddenham as a whole averaged approximately £410,000 to £444,000 in recent datasets, although methodologies and reporting periods differ.
What Could Affect a Mortgage in Biddenham Turn?
A valuable house doesn’t automatically mean a complicated mortgage.
Equally, a straightforward-looking purchase can become more complex when income, borrowing requirements or property characteristics enter the underwriting process.
An adviser may need to consider several factors.
Loan size
A larger mortgage can reduce the number of available lenders or products.
Individual lenders may apply:
- maximum loan limits;
- lower loan-to-value thresholds at higher borrowing levels;
- enhanced underwriting;
- different affordability calculations;
- restrictions on interest-only borrowing;
- minimum income requirements for particular products.
This makes the application structure as important as the headline rate.
Deposit and existing equity
Someone moving from an existing home may bring substantial equity into the purchase.
A lower loan-to-value can strengthen some applications, but lender criteria still matter. Large deposits do not automatically overcome affordability or property concerns.
Complex income
Higher-value property owners are not necessarily conventional salaried applicants.
Income could include:
- salary and bonuses;
- company dividends;
- retained company profit;
- partnership drawings;
- investment income;
- rental income;
- overseas earnings;
- several separate income sources.
Different lenders may calculate these sources differently.
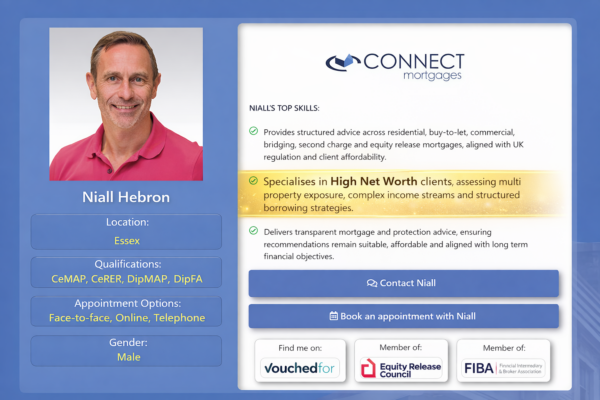
Applicants with significant assets or complex earnings can therefore consider an adviser experienced with High Net Worth Mortgage Brokers rather than assuming a standard affordability calculator tells the whole story.
The property itself
Biddenham Turn includes established detached homes and larger plots.
The Biddenham Conservation Area Appraisal notes the area’s transition from Biddenham Turn into the historic settlement. It describes the road’s larger homes, trees, hedges and spacious plots as part of the local character.
The conservation area does not mean every Biddenham Turn property faces identical restrictions.
However, where an older, altered, or unusual home is involved, buyers should establish whether planning, title, valuation, or construction matters warrant further investigation.
A lender’s valuer is assessing the property as security for the mortgage, rather than conducting a detailed building survey for the buyer.
Why Higher-Value Mortgages Can Need Different Underwriting
A £1 million property does not necessarily require a £1 million mortgage.
That distinction is important.
Someone purchasing for £1.2 million with substantial equity may require considerably less borrowing. Another buyer could need a much larger loan despite purchasing at a similar price.
Lenders may therefore assess:
The loan-to-value:
How much is being borrowed compared with the property’s valuation?
Income composition:
Is income fixed, variable, company-based or derived from investments?
Overall commitments:
Loans, school fees, credit agreements, maintenance and other regular expenditure can affect affordability.
Repayment strategy:
Capital repayment and interest-only arrangements can have different eligibility requirements.
Assets and liquidity:
Some lenders may consider wider wealth, although treatment differs substantially between lenders.
Age and mortgage term:
The proposed term and expected retirement income can become relevant where borrowing continues later in life.
The benefit of finding a suitably experienced adviser is not simply access to more lenders. It is understanding which lenders’ criteria are more likely to fit the actual case.
Finding the Right Mortgage Adviser in Biddenham Turn
Finding a mortgage adviser should begin with the circumstances, not just the postcode.
Connect Experts allows you to search for a mortgage adviser by expertise and compare advisers whose permissions and experience correspond with your requirements.
For a Biddenham Turn property, useful questions could include:
- Does the adviser regularly handle larger mortgage balances?
- Can they assess bonus, dividend or retained-profit income?
- Do they understand interest-only criteria where relevant?
- Can they explain how different lenders treat significant assets?
- Have they dealt with established or unusual higher-value homes?
- Can they explain lender fees and mortgage costs clearly?
- Can they provide the appointment type you prefer?
Connect Experts is a directory and adviser-matching service. Mortgage advice is provided by the adviser or firm selected.
You can also explore Mortgage Brokers in Bedfordshire when you want to compare advisers covering the wider county.
Moving Home to Biddenham Turn
Buying a more valuable home often creates a chain of connected financial decisions.
An existing mortgage may need to be redeemed, ported or replaced.
Porting does not mean approval is automatic. Even where an existing mortgage product can technically move, the lender can reassess:
- affordability;
- income;
- credit history;
- the new property;
- additional borrowing;
- the proposed mortgage term.
The lender may also have to value the Biddenham Turn property before confirming that it is acceptable security.
Someone moving from another Bedford property may therefore find that their existing mortgage is only one possible route.
A comparison should consider the complete cost of staying with the current lender against changing lender, including fees and any early repayment charge.
Independent Schools and Household Affordability
Biddenham Turn also sits close to Bedford, where families have access to several established independent schools, including Bedford School, Bedford Modern School and Bedford Girls’ School.
That does not make school fees a mortgage product. However, regular education costs can form part of household expenditure and therefore affect mortgage affordability.
For families balancing substantial housing and education commitments, it can be useful to assess both together before setting a property budget.
Where appropriate, separate Education Finance options may also be considered as part of broader financial planning.
Mortgage borrowing and education funding should each be assessed on their own suitability, costs and risks.
Remortgaging a Higher-Value Biddenham Turn Home
Existing homeowners may have a different challenge.
A property originally purchased many years ago may now have substantial equity, but refinancing still depends on current circumstances.
A remortgage assessment can involve:
- the current property value;
- outstanding mortgage balance;
- remaining mortgage term;
- early repayment charges;
- income changes;
- additional borrowing requirements;
- current lender product-transfer options;
- alternative lenders.
Higher property equity can reduce loan-to-value, but it does not remove affordability or underwriting requirements.
Owners should therefore compare the full cost of refinancing rather than making a decision solely from the lowest advertised rate.
Protecting a Larger Mortgage and Household Commitments
The larger the financial commitment, the more important it can be to consider what happens if household circumstances change.
Mortgage advice can therefore sit alongside discussions about life cover, critical illness protection, income protection or other suitable arrangements.
For households with significant mortgages, complex earnings or substantial ongoing financial commitments, High Net Worth Protection Services may be relevant.
Protection needs remain individual. The appropriate type and amount of cover depends on income, dependants, existing arrangements, savings, mortgage commitments and other circumstances.
Biddenham Turn, Biddenham and the Importance of Property Context
Biddenham Turn is particularly useful as an example of why postcode-level information should not always be treated as sufficient.
The wider Bedford average can be around £330,000 while individual homes on this road have recorded seven-figure transactions.
Even the wider Biddenham average is substantially below some Biddenham Turn transactions.
This difference can affect:
- likely deposit requirements;
- mortgage size;
- valuation considerations;
- lender selection;
- affordability;
- underwriting;
- product availability.
It also reinforces why automated online affordability figures should be treated as an initial indication rather than a mortgage approval.
The right lender is the one whose criteria fit both the borrower and the property.
Find a Mortgage Adviser in Biddenham Turn
A home in Biddenham Turn can represent considerably more than a standard Bedford property purchase.
Property value, equity, income structure, borrowing size and future commitments can each influence which lenders may be suitable.
Connect Experts lets you find mortgage advisers and compare professionals by location, expertise, language and other preferences.
Review adviser profiles, consider their relevant experience and choose who you want to contact.




