
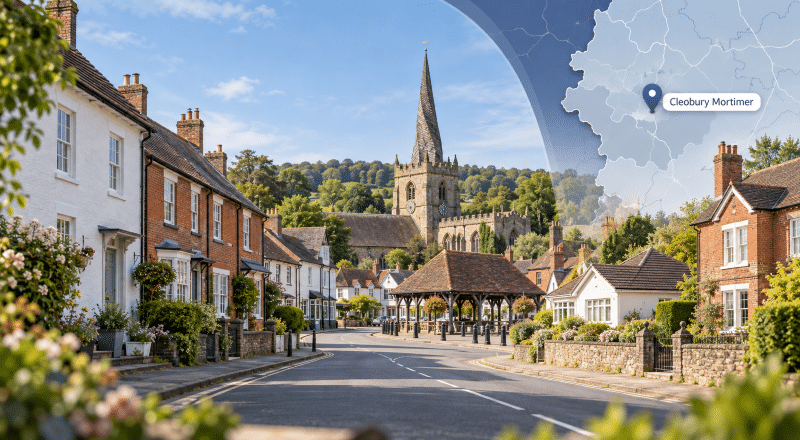
A Mortgage Broker in Cleobury Mortimer searches can begin with a simple question about borrowing, yet the answer may depend as much on the home being financed as the amount being borrowed.
Cleobury Mortimer illustrates that particularly well.
Its historic core includes a Conservation Area and listed buildings, while the town’s adopted neighbourhood plan also makes provision for new housing. Someone buying an older High Street home can therefore face different mortgage considerations from somebody purchasing a newer property elsewhere in the town.
Connect Experts helps users search for mortgage advisers by location and mortgage requirement. You can compare profiles and decide who you would like to contact. Mortgage advice is provided by the adviser or firm you select, not by Connect Experts itself.
At a glance: Mortgage Broker in Cleobury Mortimer
Cleobury Mortimer combines historic homes, a Conservation Area and planned new housing, so mortgage requirements can vary considerably by property and borrower. Older construction, valuation, deposit size, affordability and new-build lender criteria may all matter. Connect Experts helps you compare mortgage advisers covering Cleobury Mortimer and choose someone whose experience fits the mortgage circumstances you need to discuss.
Older homes and new development create different mortgage questions
Cleobury Mortimer has developed as a small market town on the A4117 between Ludlow and Kidderminster.
Its adopted neighbourhood plan identifies much of the town centre as a Conservation Area. The plan also records numerous listed buildings and historic features around High Street and Church Street.
That history can matter to a mortgage application.
An older or listed home may require a lender and valuer to consider construction, alterations, condition and future marketability. A lender’s mortgage valuation assesses the property as security for the loan. It is not the same as commissioning a structural or building survey.
At the other end of the housing spectrum, Cleobury Mortimer’s development plan allocates 5.2 hectares between Catherton Road and Ludlow Road for up to 120 homes, together with open space and supporting infrastructure.
A new-build mortgage can raise different issues, including:
- maximum loan-to-value;
- deposit requirements;
- developer incentives;
- acceptable warranties;
- mortgage-offer validity;
- lender rules for newly constructed homes.
The question is therefore not whether an older or newer home is inherently easier to mortgage.
It is whether the borrower and the particular property fit a lender’s criteria.
What do Shropshire prices tell a Cleobury Mortimer buyer?
Official house-price data are available for Shropshire rather than as a current ONS series specifically for Cleobury Mortimer.
The ONS recorded a provisional average Shropshire house price of £275,000 in July 2026. First-time buyers paid an average of £223,000, while homes purchased using a mortgage averaged £274,000.
Property type also made a substantial difference across the county:
- detached homes averaged £414,000;
- semi-detached homes averaged £258,000;
- terraced homes averaged £206,000;
- flats and maisonettes averaged £134,000.
These are county averages, not valuations for individual Cleobury Mortimer properties.
You can review the latest ONS housing data for Shropshire for the current official figures.
For somebody arranging a mortgage, price provides only the starting point.
Affordability can also depend on income, deposit, existing borrowing, dependants, household expenditure, mortgage term and the lender’s own affordability assessment.
Two buyers considering homes at the same asking price may therefore receive very different borrowing outcomes.
First-time buying in a changing Cleobury Mortimer
The adopted neighbourhood plan aims to increase local housing supply while maintaining a mixture of property types and tenures. Its housing policy says new development should demonstrate how the proposed housing mix helps meet identified local needs.
For first-time buyers, more housing types do not remove the need to understand the mortgage numbers carefully.
Before committing to a purchase, it can help to consider:
- how much deposit is available;
- whether funds are savings or a gifted deposit;
- likely monthly repayments;
- existing credit commitments;
- survey and legal costs;
- whether the home is established or newly built;
- how much money should remain after completion.
First-time buyers can use Connect Experts to find a first-time buyer mortgage adviser.
An adviser can assess affordability and lender criteria before a buyer treats an asking price as a realistic borrowing limit.
Moving between established and newer homes
Moving home can create a different calculation.
An existing Cleobury Mortimer homeowner may have equity tied up in their current property, an outstanding mortgage and potentially an early repayment charge.
They may then be comparing that position with the cost of another home.
That can involve establishing:
- expected sale proceeds;
- remaining mortgage balance;
- available equity;
- whether the current mortgage can be ported;
- whether additional borrowing is required;
- the affordability of the replacement mortgage.
The property’s characteristics still matter.
Moving from a newer home into an older property within the Conservation Area could introduce different valuation or construction considerations. Moving in the opposite direction could mean assessing new-build lender criteria instead.
Those preparing to move can search for a moving-home mortgage adviser through Connect Experts.
Cleobury Mortimer’s rural setting can affect the mortgage details
Cleobury Mortimer is surrounded by a rural South Shropshire landscape, while the River Rea, smaller watercourses and open countryside influence the settlement’s physical setting. Shropshire Council’s green-infrastructure work also identifies listed buildings, landscape sensitivity and localised flood-risk considerations around parts of the study area.
This does not mean rural or older homes are unsuitable for mortgage lending.
It does mean the detail deserves attention.
Depending on the property, a lender may need to consider matters such as:
- construction type;
- private drainage;
- access arrangements;
- acreage or additional land;
- outbuildings;
- flood information;
- listed status;
- previous alterations.
These issues are property-specific.
You should not assume them simply because a home has a rural postcode.
A mortgage adviser can determine whether a particular feature is likely to narrow the range of lenders before you submit an application.
When your existing mortgage rate is ending
A Cleobury Mortimer homeowner may not be buying anything at all.
If an existing fixed, tracker, or discounted deal is nearing its end, the key decision may be whether to stay with the current lender or remortgage elsewhere.
That review can include:
- remaining mortgage balance;
- current property value;
- loan-to-value;
- present income;
- mortgage term;
- early repayment charges;
- product fees;
- future moving plans.
A lower advertised interest rate doesn’t necessarily mean a lower overall cost once you factor in fees and other conditions.
Connect Experts provides a dedicated search for mortgage rate-ending advisers.
Reviewing the position before the current deal expires can give you more time to understand your options.
Protection belongs within the borrowing conversation
The mortgage application asks whether borrowing is affordable today.
Longer-term planning asks what could happen if household circumstances later change.
Illness, injury, loss of earnings or death can affect the ability to maintain mortgage payments. The relevance of protection depends on the household, not the postcode.
An adviser may consider matters including:
- mortgage balance;
- household income;
- dependants;
- existing life cover;
- employer benefits;
- savings;
- monthly commitments.
Life insurance, critical illness cover, and income protection serve different functions, so assess cover against individual needs rather than treating it as an automatic mortgage extra.
Connect Experts also allows users to compare protection mortgage brokers.
Later-life borrowing and equity release in Shropshire
Cleobury Mortimer also sits within a county where later-life borrowing may involve older, listed or rural property.
That makes the property itself important when assessing lifetime mortgage eligibility.
An equity release provider may consider:
- the homeowner’s age;
- current property value;
- existing secured borrowing;
- construction and condition;
- access or land;
- the amount required;
- plans to move;
- the purpose of the borrowing.
Connect Lifetime has a dedicated guide for Equity Release Advisers in Shropshire. The guide explains how local property type, later-life plans and lender criteria can interact.
Equity release is not simply a question of how much equity exists.
It can reduce an estate’s value and may affect entitlement to means-tested benefits. Consider alternatives before deciding whether it is appropriate.
People looking at mainstream mortgage borrowing later in life can also compare mortgage advisers for older borrowers.
Questions about mortgages in Cleobury Mortimer
Does an older Cleobury Mortimer property make getting a mortgage harder?
Not automatically.
However, a lender may consider construction, condition, listed status, alterations and marketability. Some properties may fit standard lender criteria, while others could require a lender comfortable with a particular building type.
Is a lender’s mortgage valuation the same as a building survey?
No.
The lender’s valuation primarily helps establish whether the property is suitable security for the mortgage. Buyers may wish to arrange a separate survey appropriate to the property’s age and condition.
Can I get a mortgage for a new-build home in Cleobury Mortimer?
Potentially, yes.
Lenders can have specific criteria for new-build homes, including maximum loan-to-value, acceptable warranties and developer incentives. The borrower’s affordability and deposit still need to meet the lender’s requirements.
Should I wait until my fixed mortgage rate ends before seeking advice?
Not necessarily.
Reviewing the mortgage before the current deal ends can provide time to compare the current lender’s options with alternatives, subject to any early repayment charges and lender criteria.
Find mortgage advice for Cleobury Mortimer
Cleobury Mortimer presents more than one type of mortgage case.
A buyer could be considering a historic town-centre home, an established family house, or a future new development. An existing homeowner may instead need to move, remortgage or consider borrowing later in life.
The useful starting point is therefore your own combination of income, deposit or equity, borrowing requirement and property type.
Connect Experts lets you compare advisers by mortgage requirement, location and other preferences. You can review profiles and choose who you want to approach.
Search for a Mortgage Adviser for Cleobury Mortimer




