
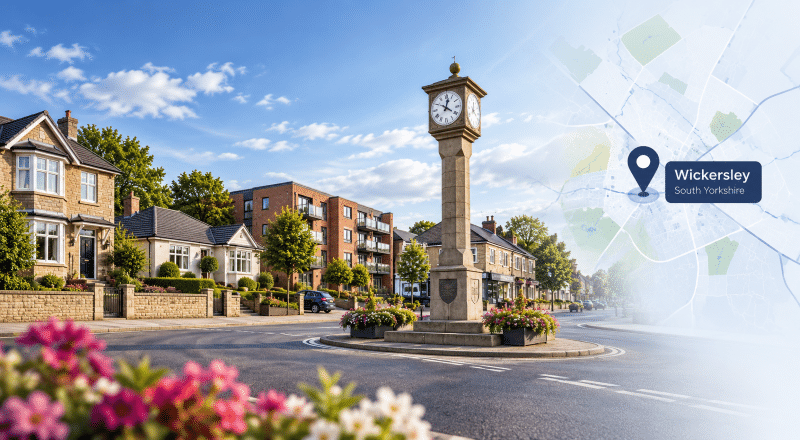
A Mortgage Broker in Wickersley can connect the property you want with how lenders assess your income, deposit, commitments, and the home itself.
Wickersley makes that distinction particularly relevant. Its housing is not dominated by one age or style. Official local planning documents identify detached homes, extensive semi-detached estates, bungalows, stone properties, apartments and newer development across distinct parts of the parish.
At a glance: Mortgage Broker in Wickersley
Wickersley has a varied housing mix, from 1920s and 1930s semi-detached homes to bungalows, larger detached houses, apartments and newer development. Its adopted Neighbourhood Plan also places specific emphasis on housing mix and design. A Mortgage Broker in Wickersley can help you compare lender criteria when property type, affordability or future plans need closer attention.
Wickersley’s Housing Mix Can Change the Mortgage Questions
Wickersley has six housing character areas within its adopted Design Code.
The differences between them are substantial.
One area contains larger detached homes around Bawtry Road, including traditional and modern properties on comparatively generous plots. Another consists predominantly of semi-detached homes dating from the 1920s and early 1930s.
Elsewhere, the housing ranges from post-war semi-detached homes to bungalows, larger detached houses, historic stone buildings and apartments.
For mortgage purposes, this matters because the lender assesses both the borrower and the property offered as security.
Depending on the home, lender criteria may consider:
- construction type;
- property age;
- condition and marketability;
- valuation;
- alterations or extensions;
- lease terms for apartments;
- whether a property is newly built;
- unusual features or materials.
A mortgage valuation is primarily for the lender. Don’t confuse it with a structural survey.
This is especially important when considering an older or less conventional property.
Local Planning Gives Wickersley a Different Housing Story
Wickersley’s Neighbourhood Plan was formally adopted by Rotherham Metropolitan Borough Council on 25 May 2022. It now forms part of Rotherham’s statutory development plan and is considered when relevant planning applications are decided.
The plan is more detailed than a general statement about building new homes.
Its policies cover housing type and mix, locally listed buildings, the conservation area, sustainable homes, green infrastructure, parking and design. The accompanying Design Code is intended to ensure development responds to Wickersley’s different local character areas.
Local housing evidence also identified a need for smaller properties for older people wishing to downsize, younger people and smaller families. For developments of ten or more homes, the neighbourhood policy seeks a mix of property sizes rather than concentrating entirely on larger houses.
That creates different mortgage circumstances within one village.
Someone purchasing an established bungalow may have very different priorities from a family buying a larger detached home or a first-time buyer considering a smaller property.
What Current Rotherham House Prices Tell Us
The strongest current official benchmark is the ONS data for the wider Rotherham local authority.
In July 2026, the provisional average house price in Rotherham was £191,000.
The ONS also reported:
- £172,000 average price for first-time buyers;
- £219,000 average price for home movers;
- £296,000 average price for detached homes;
- £188,000 for semi-detached homes;
- £151,000 for terraced homes;
- £101,000 for flats and maisonettes.
These figures apply to Rotherham as a whole, not specifically to Wickersley.
They should therefore provide context rather than being presented as Wickersley property values.
For current official figures, readers can view ONS housing prices for Rotherham.
The mortgage itself will be based on the actual property price and the applicant’s circumstances.
A lender may assess:
- salary and other acceptable income;
- deposit;
- loan-to-value;
- existing credit;
- childcare and dependants;
- regular expenditure;
- mortgage term;
- credit history;
- property type.
This is why two people purchasing homes at the same price can receive different affordability outcomes.
First-Time Buyers and Wickersley’s Smaller Housing Need
The local planning evidence gives first-time buyer content a genuine reason to appear on this page.
Wickersley’s housing assessment identified younger people and small families among the groups for whom smaller homes were under-provided.
For a first purchase, affordability should ideally be considered before the search becomes fixed on one property.
A buyer may need to establish:
- how much deposit is available;
- whether part of the deposit is gifted;
- what funds should remain for fees and moving costs;
- the likely borrowing range;
- an affordable monthly payment;
- how loan-to-value could affect lender choice.
The ONS reported that first-time buyers across Rotherham paid an average of £172,000 in July 2026, although an individual Wickersley purchase may be substantially above or below that figure.
Connect Experts lets users search for a first-time buyer mortgage adviser and compare adviser profiles based on their requirements. The directory does not itself provide the mortgage advice.
Moving Home: From One Property Type to Another
A move within Wickersley can involve more than changing address.
Its official Design Code shows how quickly housing character can change between different parts of the parish. One move could involve changing from a semi-detached property to a detached house, from a larger home to a bungalow, or from an established property to newer development.
Homeowners may therefore need to consider:
- equity in their existing property;
- the outstanding mortgage;
- additional borrowing;
- early repayment charges;
- whether the existing deal can be ported;
- affordability at the new borrowing level;
- lender acceptance of the new property.
Porting does not automatically transfer a mortgage to another home.
The borrower normally has to meet the lender’s current requirements, and the new property must also be acceptable.
The Moving Home Mortgage Guide explains porting, equity, affordability and the alternatives to keeping an existing mortgage.
Bawtry Road and the Shape of Wickersley
Bawtry Road is not simply a road through the village. It also helps define Wickersley’s physical character.
The adopted Design Code notes that the A631 runs through the Wickersley West character area. Housing on either side developed at different times, while the wider area includes generous plots, bungalows, two-storey homes and development dating from the 1930s onwards.
This illustrates why mortgage searches based only on postcode can miss an important point.
Even within the same postcode district, the property being financed can have different characteristics.
Local planning documents can be useful when researching how an area is expected to develop. Readers can view the adopted Wickersley Neighbourhood Plan documents.
Later-Life Borrowing and Downsizing in Wickersley
Later-life mortgage planning is particularly relevant here because Wickersley’s own housing evidence identifies older residents wishing to downsize as one of the groups requiring smaller homes.
An older homeowner might be considering:
- moving to a smaller property;
- repaying an existing mortgage;
- borrowing beyond retirement;
- a retirement interest-only mortgage;
- using some housing equity.
These are different financial decisions.
Age alone does not decide which option is available. Income, property value, mortgage term, existing borrowing and the lender’s criteria can all matter.
Connect Experts provides a dedicated search for mortgage advisers for older borrowers.
Where equity release is being considered, advice is especially important because a lifetime mortgage is a long-term loan secured against the home. It can reduce an estate’s value and may affect entitlement to means-tested benefits.
For the wider county journey, the South Yorkshire equity-release page is the relevant geographical route rather than forcing a separate town-specific link.
Protecting a Mortgage Beyond Completion
A mortgage can continue for decades. Household circumstances may change much sooner.
For that reason, mortgage planning can include considering what would happen if illness, injury, death or a prolonged reduction in income affected the ability to meet repayments.
Depending on individual circumstances, possible protection may include:
- life insurance;
- critical illness cover;
- income protection;
- mortgage-related protection.
The purpose is not to insure every imaginable risk.
It is to identify events that could seriously affect the household’s finances and decide whether appropriate cover is available.
Users can find protection mortgage brokers through Connect Experts.
Cover, premiums, definitions and exclusions vary between insurers.
How Can I Find a Mortgage Broker in Wickersley?
Connect Experts is a mortgage adviser directory and matching platform. It does not provide mortgage advice itself. The adviser or regulated firm the user selects provides the advice.
Users can compare advisers by factors such as:
- location;
- mortgage requirement;
- company;
- language;
- gender preference.
That means adviser selection can reflect the mortgage circumstances rather than simply choosing whoever appears geographically closest.
Frequently Asked Questions
Can property type affect a mortgage in Wickersley?
Yes. Lenders can have different criteria for particular construction methods, apartments, unusual properties and some older homes. The lender will also consider whether the property is suitable security for the mortgage.
What is the average house price in Wickersley?
The ONS does not publish its current headline UK House Price Index figure specifically for Wickersley. Its July 2026 provisional average for the wider Rotherham local authority was £191,000. A Wickersley property should therefore be assessed using its own asking price, valuation and comparable evidence rather than treating the Rotherham average as a village price.
Is Wickersley suitable for first-time buyer mortgage content?
Yes. Wickersley’s Neighbourhood Plan evidence specifically identified a need for smaller homes for younger people and small families, giving the topic genuine local relevance rather than adding first-time buyer.
Can I port my mortgage when moving to Wickersley?
Possibly. A portable mortgage may let you move an existing deal to another property, but the lender normally reassesses the borrower and the new home. Porting is therefore subject to approval.
Find a Mortgage Broker in Wickersley
Wickersley combines early twentieth-century housing, post-war estates, bungalows, larger detached homes, historic properties and newer development. That variation gives property type a genuine place in the mortgage conversation.
Your income, deposit, credit position and future plans remain central, but the home itself can also affect lender choice.
Use Connect Experts to compare advisers covering Wickersley and choose someone whose experience reflects the mortgage you need.
Search the Connect Experts Mortgage Adviser Directory




