
At a glance: Mortgage Broker in Sandbanks
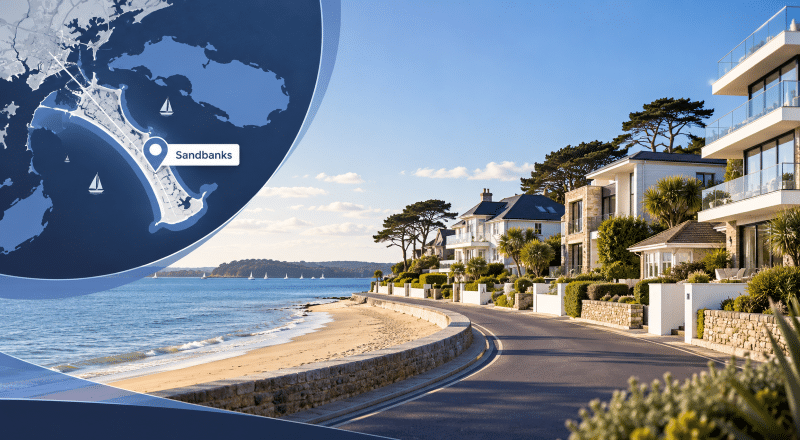
- Sandbanks is a coastal peninsula in Poole, Dorset, within the BH13 postcode area.
- Housing includes luxury detached homes, waterfront residences, and high-value apartments.
- Some purchases may involve substantial deposits, larger loans or complex income arrangements.
- Coastal exposure, flood assessments and building insurance can affect mortgage suitability.
- Leasehold terms, service charges and building documentation deserve attention when buying apartments.
- Sandbanks has access to independent schools across Poole, Bournemouth and Wimborne.
- Mortgage suitability depends on the borrower’s finances and the individual property, not simply its asking price.
Mortgage Advice in Sandbanks: Look Beyond the Purchase Price
Sandbanks is recognised for its coastal setting, proximity to Poole Harbour and distinctive residential market. However, securing mortgage finance in this part of Dorset requires more than establishing a property’s value.
A Mortgage Broker in Sandbanks can help buyers assess how their income, deposit, existing commitments and proposed property may influence borrowing options.
A substantial purchase price does not automatically mean a straightforward mortgage application.
Some buyers receive income from company dividends, bonuses, investments, or multiple business interests. Others may be purchasing a second residence or moving from an existing high-value property.
These circumstances can affect how lenders assess affordability and the supporting documents they require.
Connect Experts helps you find a mortgage adviser whose expertise reflects your financial circumstances.
The objective is not simply to borrow more. It is to understand what level of borrowing remains suitable over time.
High-Value Mortgages in Sandbanks: When Income Needs a Closer Look
High-value property transactions can involve borrowing requirements that fall outside standard mortgage applications.
For example, a company director may have substantial business assets but receive a relatively modest salary. Another applicant may earn income through annual bonuses, investments or international employment.
A Mortgage Broker in Sandbanks with relevant high-net-worth experience can explore how different lenders assess these circumstances.
Mortgage considerations may include:
- Larger loan amounts and individual lender exposure limits.
- Salary, dividends, retained profits and fluctuating earnings.
- Interest-only mortgages and acceptable repayment strategies.
- Income from several companies or investment sources.
- Applicants with substantial assets but limited regular income.
- Deposit sources, liquidity and supporting financial documentation.
Some lenders offer specialist underwriting or private banking arrangements. However, eligibility depends on individual circumstances and lender criteria.
For more information, explore high-net-worth mortgage options through Connect Mortgages.
A valuable mortgage recommendation should consider the structure of the borrowing, not simply the size of the loan.
Coastal Homes in Sandbanks: Mortgage and Insurance Considerations
Sandbanks sits in an unusual position between Poole Harbour and the English Channel.
That location creates specific questions for buyers, particularly when purchasing waterfront homes or properties exposed to coastal conditions.
A lender may require a satisfactory valuation, appropriate buildings insurance and additional supporting information.
Buyers should consider:
Flood exposure: Check the property’s specific location using the Environment Agency’s long-term flood risk service. This provides area-level information rather than a definitive assessment of an individual building.
Insurance: Obtain buildings insurance quotations early. Cover availability, premiums, exclusions and excesses may affect overall affordability.
Construction: Unusual materials, extensive glazing, specialist designs or substantial alterations can influence lender valuation requirements.
Apartments: Review lease length, service charges, ground rent where applicable and building-related documentation.
Previous alterations: Extensions and major structural changes may require planning, building regulation or other supporting evidence.
These checks do not mean coastal properties are automatically difficult to mortgage. They help identify issues before the buyer commits financially.
The Bournemouth, Christchurch and Poole Council website provides local planning and property-related information.
Remortgaging a Sandbanks Home: Protecting Your Next Decision
Owning a valuable property doesn’t remove the need to review its mortgage.
An existing deal approaching expiry can present an opportunity to assess the outstanding balance, current property valuation and available lender options.
A Mortgage Broker in Sandbanks can review whether retaining the existing lender or considering an alternative would better suit your circumstances.
This may involve reviewing:
- Fixed-rate and variable-rate options.
- Existing early repayment charges.
- Outstanding mortgage balance and available equity.
- Changes in employment or business income.
- Mortgage term and monthly repayment requirements.
- Additional borrowing for eligible purposes.
Homeowners approaching the end of a mortgage deal can compare mortgage rate-ending advisers.
A lower interest rate does not always mean a lower overall cost. Fees, repayment structure and the mortgage term also matter.
Buying a Second Home or Investment Property in Sandbanks
Sandbanks attracts buyers looking for a coastal residence, an additional home, or a property intended to generate rental income.
However, the purpose of the purchase is important.
A main residence, second home, holiday let and conventional buy-to-let property may require different mortgage arrangements.
A Mortgage Broker in Sandbanks can help borrowers identify advisers who understand the intended property use and relevant lender criteria.
For investors, useful specialist searches include:
- First-time landlord mortgage advisers for buyers entering the rental market.
- Portfolio landlord mortgage advisers for experienced landlords managing several properties.
- Limited company buy-to-let advisers where a property is purchased through a company.
- Non-UK resident buy-to-let advisers for overseas applicants considering UK rental property.
If a property needs refurbishment or requires alternative funding, short-term bridging finance advisers may also be relevant.
For anyone considering a holiday let, lenders may assess projected rental income, occupancy assumptions and any restrictions affecting the property.
A property suitable for holiday accommodation does not automatically meet every lender’s holiday-let mortgage criteria.
Education Finance for Families Moving to Sandbanks
For some families, moving to Sandbanks involves more than choosing a property.
Education, family commitments and long-term affordability can influence the financial decision.
Sandbanks offers access to independent education across the wider Poole, Bournemouth and Wimborne areas.
Examples include:
- Canford School, an independent day and boarding school near Wimborne.
- Bournemouth Collegiate School, which provides independent education across its local sites.
- Talbot Heath School, an independent school in Bournemouth.
The Independent Schools Council also provides information about independent schools in Bournemouth.
Consider School Fees Alongside Mortgage Affordability
A household may have sufficient income to support a substantial mortgage but also face significant ongoing education costs.
School fees, transport, extracurricular activities and other family commitments should form part of the broader affordability discussion.
Families exploring private education funding can also review the education finance information available through Connect Mortgages.
A mortgage decision should account for financial commitments that continue after the purchase.
Protection Advice: Safeguarding a Sandbanks Mortgage
A mortgage may be one of a household’s largest financial commitments, particularly when buying a high-value home.
However, being able to afford repayments today does not guarantee circumstances will remain unchanged.
Illness, injury, death or an unexpected reduction in income may affect the ability to maintain those payments.
Suitable protection advice can help borrowers consider:
- Life insurance: Financial protection for beneficiaries if the insured person dies during the policy term.
- Critical illness cover: A potential lump-sum payment following diagnosis of a condition covered by the policy.
- Income protection: Regular benefits if illness or injury prevents the insured person from working, subject to policy conditions.
- Existing insurance: Whether current arrangements remain appropriate after changing mortgage commitments.
Business owners and self-employed applicants may have additional considerations where their income depends on continued business activity.
Connect Experts lets clients find protection mortgage brokers to discuss suitable options.
The right protection arrangements depend on individual needs, affordability, eligibility, exclusions and policy conditions.
Financial confidence is not only about securing a mortgage. It is also about considering how that commitment could be maintained if circumstances change.
Equity Release and Later-Life Lending in Dorset
Homeowners approaching retirement may consider how their existing property wealth fits into their future financial plans.
In Sandbanks, a property may represent a significant asset, but its value alone does not determine which later-life borrowing options are appropriate.
A homeowner might want to:
- Repay an existing mortgage.
- Release capital for a specific purpose.
- Support retirement spending.
- Consider downsizing rather than borrowing.
Understand the effect of borrowing on inheritance and remaining equity.
Later-life mortgage options can include retirement interest-only mortgages and lifetime mortgages, depending on eligibility and individual circumstances.
Connect Lifetime provides information about equity release and lifetime mortgage options.
A lifetime mortgage generally allows interest to roll up, increasing the amount owed over time. It may reduce the estate’s value and affect entitlement to means-tested benefits.
Important: I could not verify a live Connect Lifetime equity release adviser page specifically covering Sandbanks or Dorset. I have therefore linked to the main website rather than inventing a county-specific URL.
Choosing the Right Mortgage Adviser for Sandbanks
A Mortgage Broker in Sandbanks should be selected for relevant expertise, not simply geographical convenience.
An adviser familiar with high-value borrowing may be appropriate for one client. Another borrower may need specialist support with rental properties, self-employed income or remortgaging.
Before choosing an adviser, consider three questions.
Does the adviser understand your borrowing requirements?
Review the adviser’s qualifications, permissions and experience. Look for specialisms that match your circumstances.
Can the adviser explain the costs and limitations?
You should understand mortgage repayments, fees, product restrictions, potential early repayment charges and the reason for any recommendation.
Is the adviser appropriately regulated?
Use the Financial Conduct Authority’s Firm Checker to verify a firm’s regulatory status and permitted activities.
Connect Experts helps clients compare adviser profiles by location, expertise and other relevant preferences.
The directory is a matching platform. It does not provide personalised mortgage advice directly.
Start Your Mortgage Adviser Search in Sandbanks
A suitable mortgage starts with understanding your circumstances.
Whether you are buying a waterfront residence, reviewing an existing mortgage or financing an investment property, the quality of the advice matters.
Use Connect Experts to find a mortgage adviser in Dorset or explore mortgage advisers in Poole.
Compare adviser specialisms, review the available information, and choose who you want to contact.
The aim is not simply to complete a property transaction. It is to make a borrowing decision that still makes sense after the keys change hands.




