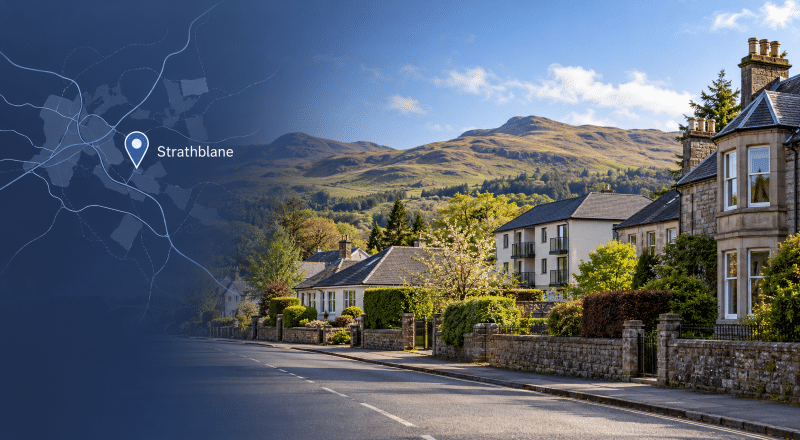
A Mortgage Broker in Strathblane can help you consider what matters beyond the appeal of a beautiful place to live. The Campsie Fells may influence where you want to put down roots. However, the mortgage must support the life you plan to build there.
A home is both a personal choice and a financial commitment. The best mortgage decision considers your income, the property’s condition, borrowing costs, and your future plans.
Strathblane offers a village setting within reach of Glasgow, with neighbouring Blanefield and the surrounding Stirlingshire countryside adding to its appeal.
Whether you are buying your first home, moving from Glasgow or reviewing an existing mortgage, understanding the details early can make the next stage more reassuring.
At a Glance: Mortgage Broker in Strathblane
- Strathblane is a Stirlingshire village within the Stirling Council area.
- Strathblane and neighbouring Blanefield share the G63 postcode district.
- The Campsie Fells provide a distinctive setting, while Glasgow remains within commuting distance.
- Village houses, traditional properties and rural homes may raise different mortgage valuation questions.
- Scottish Home Reports include key information about a property’s valuation, condition, and energy efficiency.
- Buyers offering above the valuation may need additional funds beyond their planned deposit.
- Stirling Council publishes catchment information for Strathblane Primary School.
- Mortgage suitability depends on your financial circumstances and the property, not simply its location.
Village Living With Financial Decisions That Deserve Attention
Strathblane sits at the foot of the Campsie Fells, with Blanefield forming part of the neighbouring community. The area offers countryside access while staying connected to Glasgow via the A81.
This combination may appeal to buyers seeking a different pace of life without moving too far from employment and services.
However, a change of address does not automatically mean a simpler mortgage application.
A Glasgow homeowner moving to Strathblane may need to repay, transfer, or replace an existing mortgage. First-time buyers may need to understand Scotland’s purchasing process before submitting an offer.
For those considering a larger home, the challenge may be balancing mortgage repayments against household spending, transport costs and planned improvements.
Local information also deserves attention.
Stirling Council’s Strathblane Local Place Plan outlines community priorities, including housing and local infrastructure.
It offers useful background for buyers considering the area’s longer-term development, although proposals do not guarantee future changes.
For buyers with children, Strathblane Primary School is another relevant consideration. Families should confirm school catchment boundaries for the individual address rather than relying on the postcode alone.
What Makes a Strathblane Property Suitable for Mortgage Lending?
Two houses can sit close together yet receive different mortgage assessments.
A conventional home in the village may present relatively straightforward questions about value and condition. An older cottage or property on the outskirts could require additional evidence.
Depending on the property, lenders may investigate:
- Construction: Whether the walls, roof and building materials meet their lending criteria.
- Condition: Whether defects or outstanding repairs could affect mortgage security.
- Access: Whether the property has suitable legal access, particularly where private roads are involved.
- Land and outbuildings: Whether additional acreage or buildings introduce lending restrictions.
- Private services: Whether drainage, water or other arrangements require further checks.
- Alterations: Whether extensions and significant building works have appropriate permissions and documentation.
These issues are not automatic problems. They are considerations that may become relevant to a particular property.
An experienced adviser can identify potential lender concerns before a full application. Your solicitor will separately investigate title, access rights and other legal matters.
Why the Scottish Home Report Deserves Attention
Most existing homes marketed for sale in Scotland require a Home Report, subject to certain exceptions.
The Scottish Government’s Home Report guidance explains its three main components:
- Single survey and valuation: The surveyor’s assessment of condition and estimated value.
- Property questionnaire: Information supplied about the property’s history, alterations and other matters.
- Energy report: Details of energy performance and estimated running costs.
The valuation is especially important when considering your deposit.
If you offer more than the lender’s accepted valuation, you may need to fund the difference yourself. This can increase the money required before completion.
Understanding that distinction early helps you establish a realistic purchasing budget.
When a Mortgage Broker in Strathblane Can Help
Mortgage requirements often change as life develops. The right specialist experience depends on what you are trying to achieve.
Buying Your First Home
First-time buyers may need help understanding deposits, affordability checks, credit commitments and the Scottish purchasing process.
An adviser can explain how lenders assess your income and borrowing requirements before you begin making offers.
Moving Home or Reviewing an Existing Mortgage
If you already own a home, you may want to explore whether your existing mortgage can move with you.
Alternatively, your current deal may be approaching its expiry date.
You can compare mortgage rate-ending advisers who can discuss your existing deal, lender criteria and possible next steps.
Reviewing matters early can help you understand arrangement fees, early repayment charges and the total cost of a new deal.
Self-Employed Applicants and Company Directors
Not every borrower receives a predictable monthly salary.
Company directors, contractors and self-employed applicants may receive earnings through profits, dividends or multiple income sources.
Lenders can assess this income differently.
Choosing an adviser who understands your business structure and financial evidence may improve the quality of your initial mortgage application.
Financing a Property You Intend to Let
Some buyers consider rental property alongside their residential plans.
If youare buying your first investment property, a first-time landlord mortgage adviser can explain deposits, rental income assessments, and lender requirements.
If you intend to borrow through a company, limited company buy-to-let advisers can explain the different mortgage criteria.
Borrowers building several rental properties may also benefit from portfolio landlord mortgage advice.
Rental demand should be assessed carefully, and ownership decisions may also require independent tax and legal advice.
Larger Mortgages and Complex Financial Circumstances
A substantial mortgage does not always mean a straightforward application.
Some borrowers have significant assets but receive income through business ownership, investments or several financial arrangements.
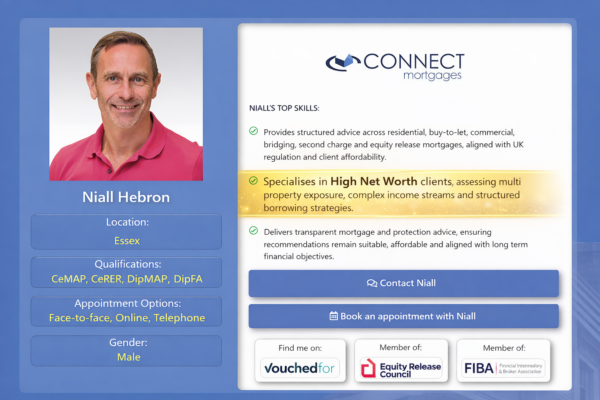
Where these circumstances apply, high net worth mortgage brokers may help identify lenders suited to larger loans or complex financial arrangements.
The need for specialist advice comes from the borrower’s circumstances, not simply the value of the home.
Understanding the Real Cost of Your Next Move
A mortgage rate tells you something about the cost of borrowing. It does not tell you everything about the cost of moving.
Your financial plan should consider the deposit, solicitor’s fees, required surveys, moving expenses, and possible property improvements.
In Scotland, Land and Buildings Transaction Tax may also affect the amount you need.
Speaking with a Mortgage Broker in Strathblane before making a formal offer can help establish a sensible borrowing range.
Your adviser may consider:
- Your deposit and any additional available savings.
- Employment income and existing financial commitments.
- Current mortgage payments and future affordability.
- The difference between initial mortgage rates and longer-term costs.
- Arrangement fees, incentives and possible early repayment charges.
- Whether fixed or variable borrowing would suit your circumstances.
The cheapest initial rate is not necessarily the most suitable mortgage.
A useful comparison considers the deal’s full cost, its flexibility, and what may happen when the initial rate ends.
Mortgage Protection: Preparing for the Unexpected
Buying a home is often about creating greater stability.
Yet a mortgage is usually one of a household’s largest financial commitments. It deserves protection against events that could affect the ability to repay.
A Mortgage Broker in Strathblane should help you decide whether protection advice is appropriate and confirm who can provide it.
Depending on your circumstances, relevant cover may include:
- Life insurance: Providing financial support for loved ones if you die during the policy term.
- Critical illness cover: Potentially paying a lump sum following a diagnosis covered by the policy.
- Income protection: Replacing part of your income if illness or injury prevents you from working.
- Buildings and contents insurance: Helping protect your property and belongings against specified risks.
These policies have different terms, limits, exclusions and eligibility requirements.
You can search for protection mortgage brokers with the appropriate knowledge and permissions to discuss your circumstances.
Protection does not remove life’s uncertainty. Suitable cover can, however, provide valuable financial reassurance when circumstances change.
Later-Life Mortgage Advice and Equity Release in Stirlingshire
Mortgage decisions don’t end when someone retires.
Some Strathblane homeowners may want to review an existing mortgage, fund improvements or consider ways to access wealth tied up in their home.
Options can include conventional remortgaging, retirement interest-only mortgages and equity release, depending on eligibility and personal circumstances.
A lifetime mortgage is one form of equity release. It allows eligible homeowners to borrow against their property while retaining ownership.
However, it is a long-term financial commitment.
Interest may be added to the loan, increasing the balance over time. This can reduce the equity remaining in the property and the value of any inheritance.
Property construction, condition, location and valuation can also affect whether an equity release provider will accept the home.
For specialist support, read about Equity Release Advisers in Stirlingshire and Later-Life Mortgage Advice through Connect Lifetime.
A suitably qualified adviser can assess your options, explain key risks, and consider whether an alternative may be more appropriate.
Choosing an Adviser Who Understands Your Mortgage Needs
The nearest adviser is not necessarily the most suitable adviser.
You may need someone experienced in Scottish property purchases, self-employed income, specialist lending, or an existing mortgage that needs careful restructuring.
Before choosing an adviser, consider the following questions:
- Does the adviser have experience with your type of mortgage?
- Can they explain which lenders may consider your circumstances?
- Do they understand the Scottish purchasing process?
- Can they identify potential property or valuation concerns?
- What fees could apply, and when would they become payable?
- Can they explain the reasons behind their recommendations?
- Do they hold the relevant regulatory permissions?
Connect Experts allows you to compare adviser profiles and search by location, language and personal preferences.
The aim is to identify someone whose knowledge matches your needs and who can explain your options clearly.
Mortgage Questions for Buyers and Homeowners in Strathblane
Can I transfer my existing Glasgow mortgage when moving to Strathblane?
Possibly. Some mortgages allow you to transfer your existing deal to another property through a process called porting.
However, your lender must assess the new home and your financial circumstances.
You may need additional borrowing if the new property costs more. Different rates or terms could apply to that extra borrowing.
Porting is subject to lender approval and should not be treated as an automatic right.
What happens if I buy a Strathblane home before selling my current property?
Your lender may need evidence that you can afford both properties during the period of overlapping ownership.
The purchase could also trigger Scotland’s Additional Dwelling Supplement, depending on your circumstances.
Some buyers who subsequently sell their previous main residence may qualify for a repayment under the applicable rules.
Revenue Scotland’s Additional Dwelling Supplement guidance explains when the charge applies and the conditions for a potential repayment.
Your solicitor or tax adviser should confirm the position before you commit to the purchase.
Can I use a family gift towards a mortgage deposit in Strathblane?
Many lenders accept gifted deposits, but their requirements differ.
They may request confirmation of the donor’s identity, the source of the funds and whether repayment is expected.
An adviser can explain the relevant lender criteria before your application.
Your solicitor will also need to complete the appropriate source-of-funds and legal checks.
Strathblane Mortgage Advice: Take the Next Step With Clarity
Finding a home that feels right is important. Finding a mortgage that stays suitable is just as important.
Choose a Mortgage Broker in Strathblane for the experience they bring to your circumstances, not simply for convenience.
Whether you are buying your first home, moving to the area, reviewing your mortgage or planning for later life, informed decisions start with the right questions.
Use Find a Mortgage Adviser through Connect Experts to explore advisers serving Strathblane, Blanefield and the wider Stirlingshire area.