A Mortgage Broker in Larbert may begin with your income and deposit, but a sound mortgage decision considers the life those figures must support.
A household can have a reliable income without receiving exactly the same amount every month. Equally, a home may look affordable until the deposit, legal costs and mortgage valuation are considered together.
That distinction matters in Larbert.
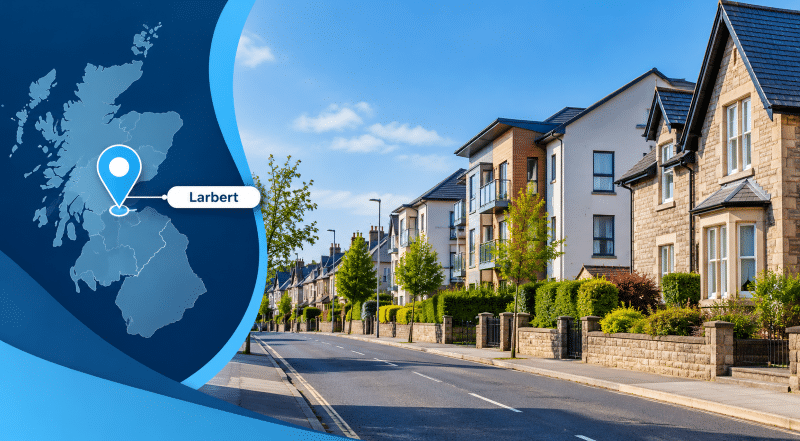
Home to Forth Valley Royal Hospital, the town also has established residential streets, modern housing around Kinnaird Village and rail connections across central Scotland.
Whether you are buying your first home, moving with your family, remortgaging or investing in property, the right mortgage adviser can help you understand what lenders are likely to assess.
Connect Experts helps you find advisers based on location, mortgage experience, language and your borrowing requirements.
At a glance: Mortgage Broker in Larbert
- Location: Larbert is in the FK5 postcode district, within Falkirk Council and the historic county of Stirlingshire.
- Local employment: Forth Valley Royal Hospital is based on Stirling Road. NHS shift allowances, overtime and bank work can require individual lender assessment.
- Housing: Kinnaird Village includes flats, terraced houses, semi-detached properties and larger detached homes.
- Property prices: The average property price in the Falkirk council area was £173,000 in July 2026, according to provisional ONS figures.
- First-time buyers: Buyers purchasing their first home across Falkirk paid £144,000 on average during the same month.
- Scottish buying process: Home Report valuations, deposit requirements and offers above valuation can affect the money needed to complete.
- Transport: Larbert railway station provides connections towards Stirling, Falkirk, Glasgow and Edinburgh.
- Education: Larbert High School serves several feeder primary schools. Check the catchment for the exact property address.
- Mortgage advice: An adviser’s experience with your income, property and mortgage type can matter more than their physical distance.
See the latest Falkirk house price figures from the Office for National Statistics.
The figures cover Falkirk Council rather than Larbert alone. They provide useful context but don’t establish the value of an individual property.
Larbert Homes: Different Properties, Different Mortgage Checks
Larbert offers buyers a choice between established neighbourhoods and more recent residential developments.
Around Kinnaird Village, buyers may encounter modern flats, townhouses and detached family homes. Elsewhere, older homes can raise questions about construction, maintenance, and previous alterations.
A Mortgage Broker in Larbert can help you understand how these differences may affect lender requirements.
Buying in Kinnaird Village
The Kinnaird Village development has significantly expanded housing in northern Larbert.
When considering a flat or house within the development, you may need to establish:
- Whether the property has any shared maintenance or factoring arrangements.
- Whether a newly built home has appropriate warranty or certification documents.
- Whether the lender accepts the construction type and property valuation.
- How the purchase price compares with the lender’s assessment of value.
A newer home does not automatically create a simpler mortgage application. Lenders still consider affordability, the deposit, the property and the applicant’s circumstances.
Established Homes and Property Condition
Older properties can also attract buyers who value established streets, larger gardens, or traditional features.
However, an adviser may need to consider the mortgage implications of non-standard construction, structural alterations or repair requirements.
For Scottish resale properties, the Home Report provides a useful starting point.
It normally includes a survey and valuation, a property questionnaire and an energy report. Some properties, including certain new-build homes, are exempt from the Home Report requirement.
The lender may still require its own valuation or further evidence before approving a mortgage.
NHS Income and Mortgage Affordability in Larbert
Forth Valley Royal Hospital creates a particularly relevant mortgage consideration for local healthcare workers.
A mortgage lender does not always treat all parts of an NHS employee’s earnings the same way.
For example, a nurse, healthcare assistant, doctor or other hospital employee may receive basic salary alongside additional payments.
These can include:
- Regular unsocial-hours enhancements.
- Overtime payments.
- Bank shifts.
- Contractual allowances.
- Additional income from another employment arrangement.
Some lenders may consider qualifying additional income when assessing affordability. Others may require a longer payment history or restrict variable earnings.
An adviser should therefore establish which income sources are acceptable before estimating borrowing capacity.
When Your Earnings Change Each Month
A healthcare professional might earn £3,000 one month and £3,500 the next, depending on working patterns.
That does not mean every lender will assess the higher figure.
Some lenders may average eligible variable earnings over a specified period. Others may use a different method or exclude certain payments.
Depending on your employment circumstances, an adviser may request payslips, bank statements, a P60, employment contracts or evidence of consistent additional earnings.
Locum doctors, agency workers and self-employed professionals can require a different assessment.
The important question is not simply what you earn. It is how much of that income a particular lender is prepared to recognise.
For further local employment context, see NHS Forth Valley’s information about Forth Valley Royal Hospital.
Buying in Larbert: Understand the Valuation Before You Offer
The Scottish property buying process introduces financial considerations that buyers moving from England or Wales may not expect.
A property’s advertised price is not necessarily its Home Report valuation.
For example, imagine a property with a Home Report valuation of £200,000.
If you agree to pay £215,000, the lender may calculate its loan using the £200,000 valuation rather than the higher agreed price.
You could therefore need additional savings to cover the difference, as well as the required mortgage deposit.
This is especially important when properties attract competing offers.
Before instructing your solicitor to submit an offer, establish your available deposit, potential mortgage borrowing and the funds needed for a higher purchase price.
You should also budget for legal costs and any applicable Scottish Land and Buildings Transaction Tax.
Your solicitor can explain the legal process, including when missives become binding. Mortgage advice and legal advice serve different purposes, but both are important before you commit.
First Homes, Family Moves and Mortgage Renewals
Mortgage requirements change as your circumstances change.
A first-time buyer may be concerned about saving enough money. Someone moving to a larger house may need to understand the costs of replacing an existing mortgage.
A homeowner nearing the end of a fixed-rate deal may have another set of questions.
A Mortgage Broker in Larbert can help you compare the borrowing options relevant to your stage of life.
First-Time Buyers in FK5
First-time buyers should consider more than the largest mortgage a lender might offer.
Monthly repayments, deposit size, existing debts, mortgage fees and the cost of maintaining the property all affect affordability.
An agreement in principle can indicate potential borrowing, but it is not a guaranteed mortgage offer.
The lender’s final decision depends on its assessment of your circumstances and the property.
Moving to a Larger Home
For families moving within Larbert, perhaps from a smaller property to a larger home around Kinnaird, an existing mortgage can influence the next purchase.
You may be able to transfer your existing mortgage product to another property, subject to your lender’s requirements.
However, additional borrowing, early repayment charges and the availability of suitable products should all be considered.
A comparison should focus on total borrowing cost rather than just the new interest rate.
When Your Mortgage Rate Is Ending
If your current fixed or tracker deal is nearing its end, it may be worth reviewing your options before the expiry date.
You may be able to transfer your product with your existing lender or remortgage elsewhere.
The best option depends on your remaining mortgage balance, equity, income, fees, and future plans.
Use our Mortgage Rate Ending Adviser Search to find advisers experienced in reviewing mortgage renewals.
Buy-to-Let and Property Investment Around Larbert
Larbert’s residential housing also offers prospective landlords different property types to assess.
However, proximity to a hospital, railway station or employment centre does not guarantee rental demand or mortgage suitability.
A buy-to-let lender may consider expected rental income, the property’s value, your deposit, existing borrowing and your landlord experience.
The type of letting arrangement also matters.
If youare buying your first investment property, our First-Time Landlord Adviser Search can help you find advisers familiar with rental property finance.
Those already managing several properties may benefit from speaking with a Portfolio Landlord Mortgage Adviser.
Other specialist requirements include:
Limited company property investment: Buying through a company may involve different lending criteria, documentation and ownership considerations. Search for Limited Company Buy-to-Let Advisers.
Shared rental accommodation: If you intend to let a property as a House in Multiple Occupation, check lender requirements and licensing rules. Our HMO Mortgage Adviser Search can help you find relevant expertise.
Scottish private landlord registration requirements and any applicable HMO licensing should be checked with Falkirk Council before committing to a letting arrangement.
For investors, mortgage borrowing is only one part of the calculation. Maintenance, insurance, tax, void periods and management costs can affect the property’s financial position.
Protection Advice: Consider the Household Behind the Mortgage
A mortgage creates a financial commitment that may last for many years.
Yet household income can change unexpectedly.
For families in Larbert, protection advice should consider how mortgage payments and essential expenses might be managed if illness, injury or death affected the household.
This is particularly relevant when income relies heavily on one person’s employment or variable shifts.
Protection options may include life insurance, critical illness cover and income protection.
For healthcare workers, an adviser may also consider existing NHS employment benefits, such as sick pay or death-in-service provisions, where applicable.
These benefits should be reviewed against your individual circumstances rather than assumed to provide complete cover.
Our Protection Mortgage Brokers directory helps you find advisers who can discuss appropriate insurance options.
An adviser should explain the policy’s cost, eligibility, exclusions and limitations before making a recommendation.
Protection advice must be provided by an adviser or firm with the appropriate permissions.
Later-Life Mortgage and Equity Release Advice in Stirlingshire
For some established Larbert homeowners, the question is no longer how to buy a property.
It is how to decide what to do with the home they already own.
Retirement plans, outstanding mortgages, family circumstances and future living costs may influence whether later-life borrowing is worth considering.
Options can include conventional mortgages, retirement interest-only arrangements, downsizing or equity release, depending on eligibility.
A lifetime mortgage allows eligible homeowners to borrow against their property while retaining ownership. Interest may be added to the loan and compound over time.
However, equity release is not suitable for everyone. It can reduce your estate’s value and affect eligibility for means-tested benefits.
Specialist advice should examine the costs, risks and reasonable alternatives.
For further information, visit Connect Lifetime’s Equity Release Advisers in Stirlingshire.
Choosing an Adviser Who Understands Your Circumstances
A nearby adviser can be convenient, especially if you prefer face-to-face meetings.
However, distance should not be the deciding factor.
Your Mortgage Broker in Larbert should have the appropriate permissions and relevant experience for your mortgage requirements.
For example, an adviser familiar with standard salaried applicants may not have the same specialist experience as someone regularly handling variable NHS earnings or complex buy-to-let applications.
Before deciding who to contact, consider asking:
- Do you have experience with my income and employment circumstances?
- Can you explain which lenders may consider my property and deposit?
- What lenders can you access, and are there any restrictions?
- What fees will I pay, and when?
- Are you authorised to advise on the mortgage or protection product I need?
You can check a firm’s regulatory details using the FCA Financial Services Register.
Connect Experts lets you compare advisers by location, mortgage expertise, language, and other preferences.
You can also read Why Move to Stirlingshire for broader information about the region.
Your Next Mortgage Decision Deserves the Right Questions
A mortgage should reflect both your present circumstances and your future responsibilities.
For a first-time buyer, that may mean understanding the deposit before making an offer.
For an NHS worker, it may mean establishing which income a lender will accept.
For a homeowner, it may mean reviewing an expiring rate before committing to another long-term deal.
Connect Experts helps you identify advisers whose experience matches those requirements.
Begin your search for a Mortgage Broker in Larbert through our Find a Mortgage Adviser directory.
The aim isn’t simply to find someone close to home, but someone who can help you make a well-informed mortgage decision.
Important Information
Connect Experts is a mortgage adviser directory and matching platform. It does not provide mortgage advice directly. Advice is provided by the adviser or firm you select.
Adviser permissions, lender access and fees should be confirmed before proceeding. Some forms of buy-to-let and commercial finance are not regulated by the Financial Conduct Authority.