A Mortgage Broker in Fintry can help you plan beyond the day you collect your keys. The greater question is whether today’s mortgage decision will still suit your life tomorrow.
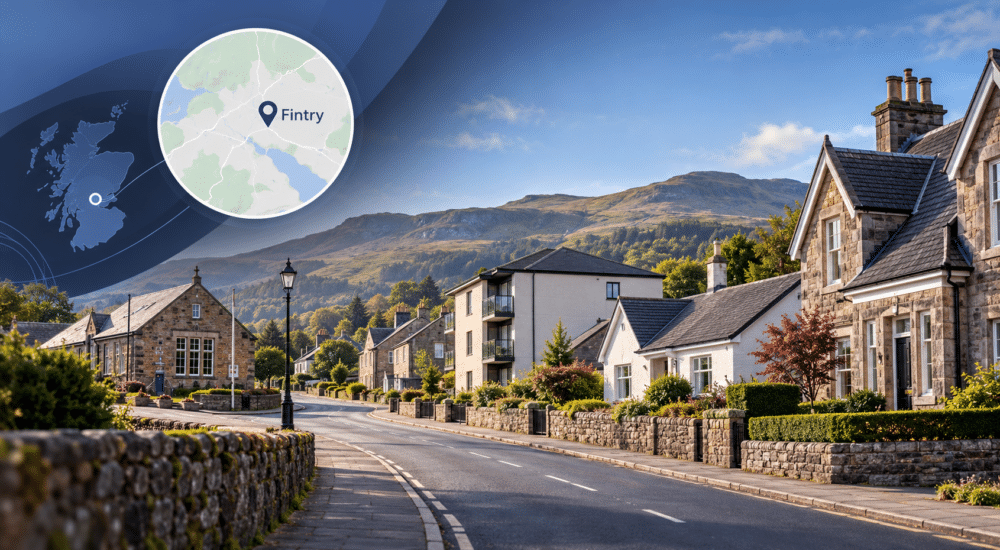
Fintry sits beneath the Campsie Fells, surrounded by Stirlingshire countryside. Its traditional cottages, village properties, and rural homes present different considerations than those in larger towns.
However, an attractive location does not automatically mean straightforward mortgage lending.
Property construction, condition, income, deposit size and lender criteria all influence what may be possible.
Connect Experts helps you find mortgage advisers covering Fintry and the G63 postcode area. Compare advisers by experience, specialisms, and personal preferences before making contact.
At a glance: Mortgage Broker in Fintry
- Location: Fintry is a rural village in Stirlingshire, within the Stirling Council area and G63 postcode district.
- Local character: The village sits near the Endrick Water, beneath the Campsie Fells, with traditional stone cottages and countryside properties.
- Conservation considerations: Parts of Fintry fall within a designated conservation area. Proposed alterations may require additional checks or consent.
- Local housing figures: Stirling Council’s average house price was £236,541 in August 2026, according to the UK House Price Index. This is a council-wide figure, not an average for Fintry village.
- Property condition: Older homes may require closer examination of construction, roofing, heating systems and maintenance.
- Scottish buying process: Home Reports provide important information about valuation, condition and energy efficiency.
- Mortgage advice: Adviser experience with rural homes and lender property criteria may matter more than office location.
Why Fintry’s Traditional Homes Need Careful Mortgage Planning
A property can look perfectly suited to your future while presenting questions for a mortgage lender.
That distinction matters in Fintry, where older village homes and rural properties shape the local housing character.
A Mortgage Broker in Fintry should consider whether a lender’s requirements match both your financial circumstances and the property itself.
Depending on the home, important considerations may include:
- Traditional stone construction or significant alterations.
- Roof condition, damp and essential repairs.
- Private drainage or water supplies, where applicable.
- Heating arrangements and energy efficiency.
- Shared access, private roads or unusual title conditions.
- Whether a lender requires additional valuation evidence.
These factors do not necessarily prevent borrowing. However, they may influence lender choice, valuation requirements or the amount available.
Conservation Areas and Property Alterations
Stirling Council has designated a conservation area in Fintry.
If you are considering an older property, investigate any restrictions before committing to substantial improvements.
Changes to windows, external appearance or extensions may require particular attention.
Review Stirling Council’s conservation area information before making decisions.
For homes near watercourses, the Scottish Environment Protection Agency flood maps provide useful information about wider area flood risk. They do not establish the risk to an individual property.
Buying Your First Home or Moving to Fintry
A quieter village may offer a different way of life, but mortgage affordability still depends on financial evidence.
A Mortgage Broker in Fintry can help first-time buyers and existing homeowners understand how lenders may assess their application.
This includes income, regular commitments, credit history, deposit size and the intended property.
For self-employed applicants, lenders may also examine trading accounts, tax calculations and income consistency.
Understanding the Scottish Home Report
Before offering on a property, review its Home Report.
In Scotland, this normally includes:
- A single survey and property valuation.
- A property questionnaire.
- An energy report.
The valuation does not guarantee mortgage approval. A lender may require its own assessment, and an offer above valuation can increase the cash deposit needed.
The Scottish Government’s Home Report guidance explains what buyers should examine.
Also consider the wider costs of buying, including legal fees, Land and Buildings Transaction Tax where applicable, moving expenses and future maintenance.
When Your Existing Mortgage Rate Is Ending
The end of a mortgage deal creates an opportunity to review more than the next interest rate.
Your household income may have changed. You may have reduced your mortgage balance or developed different financial priorities.
A Mortgage Broker in Fintry can help you explore whether a new product with your current lender or a remortgage elsewhere may suit your circumstances.
Before deciding, consider:
- The initial interest rate and total product costs.
- Arrangement fees and any early repayment charges.
- The remaining mortgage term.
- Fixed-rate, tracker and variable-rate options.
- Whether your property’s current valuation affects available deals.
You can search for an adviser specialising in mortgages with rates ending.
For additional guidance, use the UK Mortgage Rates comparison information from Connect Mortgages. Comparing overall costs can be more valuable than focusing on the lowest advertised rate.
Letting or Refurbishing Property Around Fintry
Not every mortgage enquiry concerns a home someone intends to occupy.
Some buyers may want to purchase a rental property, while others may want to improve a home before letting it.
The purpose of borrowing changes how lenders assess an application.
For example, a first-time landlord may need guidance on rental income calculations, deposit requirements and buy-to-let lending criteria.
Connect Experts provides a dedicated First-Time Landlord Adviser Search for these enquiries.
If a property needs substantial work before it’s suitable for longer-term borrowing, specialist finance may be relevant.
A Buy-to-Let Bridging Loan Adviser can explain potential short-term funding arrangements, repayment strategies and associated risks.
Bridging finance can be expensive. A credible repayment plan is essential, and availability depends on the proposed project.
Protecting Your Mortgage and Your Financial Future
Securing a mortgage is one decision. Protecting your ability to keep up repayments is another.
Illness, injury, or the loss of household income can affect financial security, no matter where someone lives.
For Fintry homeowners, protection advice should reflect personal commitments, dependants, existing cover and long-term responsibilities.
Depending on individual circumstances, suitable protection may include:
- Life insurance.
- Critical illness cover.
- Income protection.
- Mortgage payment protection.
These policies serve different purposes, and exclusions or qualifying conditions may apply.
Connect Experts helps clients find advisers offering mortgage protection advice.
Always confirm that your selected adviser has the relevant permissions to discuss and recommend protection products.
Later-Life Mortgage and Equity Release Advice in Stirlingshire
For some established homeowners, the priority is no longer purchasing another property.
It may be reviewing retirement finances, supporting family members or remaining in a familiar home.
Equity release could be one option for eligible homeowners, generally aged 55 or over for lifetime mortgages.
However, suitability depends on more than age and property value.
A specialist adviser must consider existing borrowing, property condition, future plans, available alternatives and long-term financial consequences.
Homeowners can explore Equity Release Advisers in Stirlingshire through Connect Lifetime Mortgages.
Lifetime mortgages can roll up interest over time. Equity release can reduce an estate’s value and affect entitlement to means-tested benefits. Independent legal advice and a full understanding of the risks are important.
Choose Mortgage Advice That Fits Your Fintry Plans
Choosing a Mortgage Broker in Fintry means looking beyond the nearest office.
An adviser should understand your mortgage needs, the evidence a lender may request, and any unusual features of the property.
Before choosing, consider:
- Experience with residential or specialist mortgage cases.
- Knowledge of rural or older property lending where relevant.
- Appropriate qualifications and regulatory permissions.
- Adviser fees and the lenders available through their service.
- Communication preferences and appointment availability.
You can use Connect Experts to compare advisers by location, language, gender and expertise.
Find a Mortgage Adviser and begin your search for advice that fits your circumstances.
The right decision isn’t always the quickest. It is the decision you understand, can afford and feel prepared to live with.