A Mortgage Broker in Cambusbarron can help you recognise that buying a home is about more than finding somewhere you want to live. It is also about understanding the commitment you are making and whether it will remain suitable as life changes.
Every property has a story, but lenders must look beyond its appearance. Construction, condition, valuation, affordability and the applicant’s financial circumstances all influence a mortgage decision.
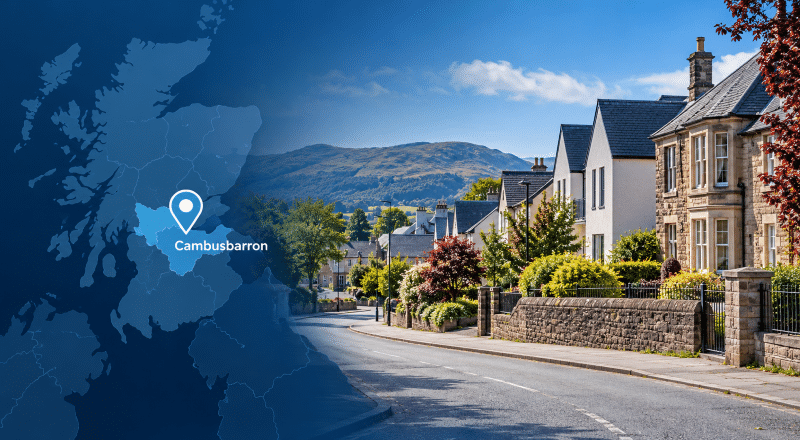
Cambusbarron, situated southwest of Stirling, combines traditional village character with access to the city and the surrounding countryside. Its older cottages, established family homes and former industrial buildings create different considerations for buyers.
Through Connect Experts, you can search for mortgage advisers with experience relevant to your circumstances, whether you are buying, moving, remortgaging or financing an investment property.
At a glance: Mortgage Broker in Cambusbarron
- Location: Cambusbarron is a village southwest of Stirling, within the FK7 postcode district.
- Housing: The village includes traditional stone cottages, established family houses, modern homes and converted industrial buildings.
- Conservation: Parts of Cambusbarron fall within a designated conservation area, which can influence alterations to certain properties.
- Historic buildings: The former Hayford Mills complex includes Category A listed buildings converted into residential accommodation.
- Local surroundings: Gillies Hill provides access to community woodland and countryside close to the village.
- Average house price: The Stirling local authority average was £239,000 in July 2026.
- First-time buyers: Across Stirling, first-time buyers paid £184,000 on average during July 2026.
- Mortgage considerations: Property condition, construction, lender valuation and affordability can affect borrowing options.
The figures are provisional Office for National Statistics data for the wider Stirling local authority area, not Cambusbarron village alone.
Understanding Cambusbarron’s Distinctive Housing
Property character can add appeal, but it can also introduce responsibilities that buyers should understand before committing.
Cambusbarron has an interesting combination of established village housing and converted former industrial properties.
For example, the historic Hayford Mills complex was once a significant woollen manufacturing site. Parts were converted into homes around 2003.
Properties within historic developments may require additional consideration because lenders can assess construction, alterations, ongoing maintenance and future saleability differently.
A Mortgage Broker in Cambusbarron can help you understand how a lender may assess:
- Traditional stone construction and roof condition.
- Converted buildings and their residential use.
- Listed buildings and restrictions affecting alterations.
- Flats with shared maintenance or factoring arrangements.
- Property valuation and any survey concerns.
- Buildings insurance requirements for unusual properties.
Not every older property creates a mortgage difficulty. However, establishing potential concerns early can prevent unexpected complications.
Buyers considering property within the village’s designated conservation area should consult Stirling Council’s conservation area information.
You can also examine the official Historic Environment Scotland record for Hayford Mills.
These resources can help establish whether particular heritage considerations need further investigation.
Buying Your First Home in Cambusbarron
A first home often represents independence. However, excitement should never replace an understanding of affordability.
Cambusbarron may appeal to people seeking village surroundings while remaining close to Stirling’s employment opportunities, shops and transport connections.
Before viewing properties, prospective buyers should establish how much they could borrow and what deposit they may need.
An adviser can assess income, regular expenditure, existing commitments and credit history before explaining relevant lender requirements.
Scotland’s property-buying process also has its own considerations.
Most properties marketed for sale require a Home Report, subject to exceptions. This normally includes a survey, valuation, property questionnaire, and energy report.
The Home Report valuation deserves particular attention when a property is advertised at an offers-over price.
If a buyer agrees to pay more than the valuation accepted by their mortgage lender, they may need additional funds to cover the difference.
A mortgage adviser can explain how the lender’s valuation and the amount borrowed affect the deposit required.
Buyers should also budget for solicitor fees, Land and Buildings Transaction Tax (where applicable), moving expenses, and essential repairs.
Moving Home: Consider What Your Next Property Requires
Moving home can mean gaining an extra bedroom, finding outdoor space or choosing somewhere closer to family.
Yet a larger home does not necessarily mean a better financial outcome.
Households moving into Cambusbarron should assess how their mortgage commitments could change alongside their wider living costs.
An adviser may help you consider:
- Whether to retain or replace an existing mortgage product.
- Early repayment charges and product portability.
- The deposit or equity available from selling your current home.
- How a longer or shorter mortgage term changes repayments.
- Affordability where income or household circumstances have changed.
For buyers moving into an older property, include anticipated maintenance in the overall budget.
The aim is to secure a home that supports your plans without placing unnecessary pressure on your finances.
For wider information about the county, explore Why Move to Stirlingshire.
Remortgaging in Cambusbarron: Plan Before Your Rate Ends
Mortgage commitments change over time. Your circumstances today may be very different from when you took out your original mortgage.
Speaking with a Mortgage Broker in Cambusbarron before your current deal ends can help you understand the available options.
Your adviser may review your outstanding balance, property value, remaining mortgage term and present financial position.
They can also consider whether staying with your existing lender or switching to another may suit you better.
When comparing products, remember that the lowest initial interest rate does not always mean the lowest overall cost.
Arrangement fees, early repayment charges, incentives and the length of the initial deal can influence the decision.
Homeowners can use Connect Mortgages’ UK Mortgage Rates comparison tool to explore indicative mortgage products and costs.
If your existing mortgage deal is approaching expiry, you can also find advisers specialising in mortgages with rates ending.
Comparison results are not mortgage offers. Eligibility remains subject to lender criteria, affordability, valuation and application checks.
Buy-to-Let and Landlord Mortgage Advice
Some property owners buy homes to rent out rather than live in them.
For landlords considering Cambusbarron or the wider Stirling area, a mortgage decision must account for more than the expected rental income.
Lenders may assess the proposed rent, deposit, property type, existing borrowing and the applicant’s experience.
The property’s condition, ongoing maintenance costs and Scottish landlord obligations should also be considered.
Connect Experts provides specialist adviser searches for different circumstances.
Buying your first rental property
A First-Time Landlord Mortgage Adviser can explain buy-to-let lending requirements, rental affordability assessments and typical deposit expectations.
Buying through a company
A Limited Company Buy-to-Let Mortgage Adviser can discuss how lenders assess company structures, directors, rental income and borrowing requirements.
Landlords expanding an existing investment portfolio may also benefit from speaking with a Portfolio Landlord Mortgage Adviser.
The best adviser depends on how you plan to own and use the property.
Mortgage Protection: Consider the Commitment Beyond Completion
A mortgage can help a household build its future.
However, you remain responsible for repayments long after completion.
Consider how those payments would be managed if illness, injury, loss of earnings, or death affected the household.
Protection advice may include:
- Life insurance: Providing financial support to beneficiaries following a policyholder’s death.
- Critical illness cover: Potentially paying a lump sum following diagnosis of a specified serious illness, subject to policy conditions.
- Income protection: Providing replacement income when illness or injury prevents the policyholder from working, subject to the cover selected.
The right approach depends on your employment, financial commitments, dependants, existing arrangements and budget.
You can find Protection Mortgage Brokers with the expertise to discuss your requirements.
Protection is not simply about taking out another policy. It is about understanding which financial risks already have sufficient cover and which may leave your household exposed.
Equity Release and Later-Life Mortgage Choices in Stirlingshire
For some established Cambusbarron homeowners, the next mortgage decision may concern retirement rather than moving home.
Property equity can become an important financial consideration when income, borrowing commitments or household requirements change.
Eligible homeowners aged 55 or over may consider a lifetime mortgage, although other later-life lending options may be more appropriate.
Equity release requires specialist advice because borrowing can affect inheritance, future housing choices and entitlement to means-tested benefits.
Interest may be added to the balance and compound over time where repayments are not made.
Homeowners should therefore consider the longer-term cost, available safeguards and reasonable alternatives before making a decision.
Connect Lifetime Mortgages provides further information through its Equity Release Advisers in Stirlingshire page.
A specialist adviser can assess eligibility, property suitability, borrowing requirements, and the potential impact on future finances.
Choosing an Adviser Who Understands Your Circumstances
Choosing a Mortgage Broker in Cambusbarron should involve more than simply finding the nearest professional.
Local knowledge can help, particularly for borrowers buying traditional properties or homes with unusual characteristics.
However, an adviser’s knowledge of your specific mortgage requirements may matter just as much.
Connect Experts lets you compare advisers by location, expertise, language, and other preferences.
Before selecting an adviser, consider whether they:
- Have experience with the mortgage type you require.
- Understand any unusual property or income circumstances.
- Hold the relevant permissions for the advice needed.
- Explain their services and fees clearly.
- Offer an appointment method that suits you.
The right adviser should help you understand both the opportunities and the limitations of your mortgage options.
Start Your Cambusbarron Mortgage Adviser Search
An important financial decision deserves more than a quick comparison.
Whether youare buying a traditional village home, reviewing an existing mortgage, or planning a property investment, informed advice can help you understand what comes next.
Search for a Mortgage Broker in Cambusbarron using the Connect Experts directory.
Find a Mortgage Adviser and compare professionals according to your mortgage requirements.