A Mortgage Broker in Bridge of Allan can help you distinguish between the home you want today and the financial commitment you can sustain tomorrow.
A property may capture your imagination through its character, location or history. Yet the real measure of a successful purchase is whether the mortgage continues to suit your circumstances long after you receive the keys.
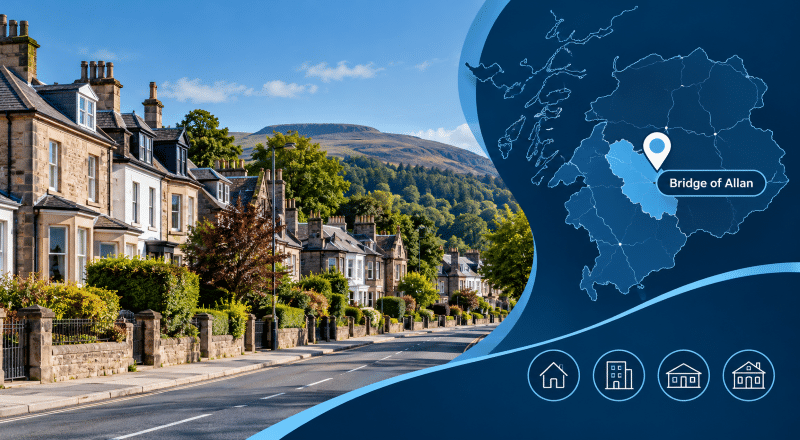
Bridge of Allan offers a distinctive setting within Stirlingshire. Its Victorian architecture, established residential streets and proximity to Stirling create different opportunities for buyers, homeowners and investors.
Connect Experts helps you find a mortgage adviser who understands your requirements. Search by location, mortgage expertise, language and personal preferences before deciding who to contact.
At a glance: Mortgage Broker in Bridge of Allan
- Location: Bridge of Allan lies north of Stirling, within the FK9 postcode district.
- Housing: The town includes Victorian villas, traditional sandstone properties, flats and newer residential developments.
- Property values: Rightmove’s rolling sold-price figures indicated an average of approximately £383,000 in Bridge of Allan in October 2026.
- Wider market: The provisional average house price across the Stirling council area was £239,000 in July 2026. This is not a Bridge of Allan-specific average.
- Conservation: Parts of the town fall within a designated conservation area. Building condition and proposed alterations may require additional checks.
- Flood considerations: Allan Water has prompted investment in local flood protection. Buyers should check individual property risks.
- Mortgage decisions: Scottish purchasing costs, lender criteria and specialist adviser experience can matter as much as the advertised interest rate.
Bridge of Allan Homes: Character, Condition and Mortgage Criteria
Bridge of Allan developed as a Victorian spa town, and its architectural history remains part of its appeal.
The Upper Town is particularly associated with substantial period villas and established gardens. Around Henderson Street and the surrounding residential streets, buyers may also encounter traditional stone buildings, converted properties and smaller homes.
That variety matters when arranging mortgage finance.
An experienced Mortgage Broker in Bridge of Allan may help identify lenders whose criteria suit the property and the applicant’s circumstances.
Lenders may consider:
- Construction materials, structural condition and the property’s age.
- Survey findings and any significant repair requirements.
- Whether a converted property meets lending criteria.
- The valuation compared with the proposed purchase price.
- Property alterations, extensions and relevant planning permissions.
- Deposit size and the resulting loan-to-value ratio.
Buyers should also review the Scottish Home Report, which normally includes a single survey and valuation, a property questionnaire and an energy report.
The Scottish Government’s Home Report guidance explains what purchasers should examine before proceeding.
Conservation Areas and Mortgage Valuations
Stirling Council identifies Bridge of Allan as having a designated conservation area.
Conservation status does not automatically prevent mortgage lending. However, restrictions on alterations, repairs, or redevelopment may affect your property plans.
Before committing to substantial renovation work, check planning requirements and obtain independent professional advice.
Review Stirling Council’s conservation area information when considering an older or architecturally distinctive home.
Understanding Flood Risk Near Allan Water
Location-specific checks are particularly important around waterways.
Stirling Council announced a £16 million programme to improve Bridge of Allan’s flood-protection infrastructure, with works scheduled from July 2026 through winter 2027.
The improvements are intended to protect properties and roads affected by the Allan Water.
This does not mean every property in Bridge of Allan faces the same flood exposure.
Before purchasing, investigate the property’s individual circumstances using the Scottish Environment Protection Agency’s flood maps.
Where relevant, also establish whether suitable buildings insurance is available and affordable.
What Bridge of Allan Property Prices Mean for Mortgage Buyers
Property averages can help establish a starting budget. However, they cannot tell you whether a particular mortgage is affordable.
Rightmove’s rolling sold-price information, reviewed in October 2026, indicated:
| Bridge of Allan property type | Average sold price |
|---|---|
| Detached houses | £632,882 |
| Semi-detached houses | £326,116 |
| Flats | £237,771 |
| Overall average | £382,853 |
These figures cover completed sales over the preceding year and may change as further transactions are recorded.
For wider context, the Office for National Statistics’ Stirling housing data reported:
- Average Stirling house price: £239,000 in July 2026.
- Average price paid by first-time buyers: £184,000.
- Average price paid by home movers: £304,000.
All three ONS figures relate to the wider Stirling local authority area, not Bridge of Allan alone.
The distinction matters. A period villa on a substantial plot can create very different borrowing requirements from a smaller flat.
Your adviser should therefore concentrate on your intended property, available deposit, income and financial commitments rather than a town-wide average.
Scottish Mortgage Costs: Plan Beyond the Deposit
Buying a home in Bridge of Allan involves costs that differ from those in England.
In Scotland, eligible property purchases may attract Land and Buildings Transaction Tax (LBTT), rather than Stamp Duty Land Tax.
First-time buyers who meet the relevant conditions may benefit from LBTT relief.
Revenue Scotland’s LBTT guidance explains the applicable rules, thresholds, and calculations.
Also consider mortgage arrangement fees, valuation requirements, solicitor costs, and moving expenses.
Before deciding on a product, you can compare current UK mortgage rates through Connect Mortgages.
A lower initial rate does not automatically mean a lower overall cost. Product fees, incentives, repayment terms and early repayment charges can change the comparison.
Mortgage Advice for Different Stages of Life
A Mortgage Broker in Bridge of Allan should consider your borrowing purpose before reviewing potential lenders.
Buying Your First Home
First-time buyers may need guidance on affordability, deposit sources, credit history and mortgage terms.
A suitable adviser can explain how lenders assess income and expenditure, and what information is required before making an application.
Moving Home or Reviewing Your Mortgage
If your existing mortgage rate is approaching its end date, reviewing your options early can give you more time to consider your next arrangement.
Your choices may include transferring your product with your existing lender or remortgaging elsewhere, subject to eligibility and suitability.
You can search for advisers who specialise in advice on mortgage rate endings.
Larger Mortgages and Complex Income
Bridge of Allan’s larger period properties can involve substantial purchase prices and borrowing requirements.
Some applicants may also have income from businesses, investments, company dividends or several sources.
Where these circumstances create a specialist lending requirement, High Net Worth Mortgage Brokers may help identify advisers experienced in significant borrowing and complex financial arrangements.
A high property value alone does not establish whether someone meets a lender’s high-net-worth criteria.
Independent School Fees and Family Mortgage Planning
Education costs may be a significant part of a family’s long-term household budget.
Although Fairview International School in Bridge of Allan closed to pupils in June 2026, other independent education options remain accessible from the town.
For example, Dollar Academy’s school transport network includes Bridge of Allan.
Families managing school fees alongside mortgage repayments may benefit from understanding how these commitments affect affordability.
Connect Mortgages provides information on education finance for independent school fees, including considerations when assessing suitable funding arrangements.
Buy-to-Let Mortgages Near the University of Stirling
The University of Stirling is accessible from Bridge of Allan and strengthens the area’s connection to higher education.
This may interest landlords considering rental property, although the university’s proximity does not guarantee tenant demand or rental returns.
For a rental purchase, a Mortgage Broker in Bridge of Allan can help assess whether standard buy-to-let borrowing or a more specialist mortgage arrangement may be appropriate.
Different property strategies require different checks.
For first-time investors: A First-Time Landlord Mortgage Adviser can explain deposit requirements, rental calculations, and lender expectations.
For shared accommodation: An HMO Mortgage Adviser can help landlords understand the lending considerations associated with houses in multiple occupation.
For established investors: Portfolio Landlord Mortgage Advisers can assist with more complex borrowing arrangements involving several rental properties.
For company ownership: A Limited Company Buy-to-Let Adviser may help assess lending options where a property is purchased or held through a company.
HMO Licensing in Bridge of Allan
Stirling Council requires an HMO licence where a property meets the Scottish licensing definition, including accommodation occupied as a principal residence by three or more unrelated people.
The council also operates an HMO overprovision policy affecting the Dunblane and Bridge of Allan ward.
Landlords should therefore investigate licensing, planning, property standards and any relevant restrictions before purchasing.
Consult Stirling Council’s HMO licensing requirements before proceeding.
Additional residential property purchases in Scotland may also attract the Additional Dwelling Supplement, depending on the circumstances.
Protection Advice: Safeguarding More Than Your Mortgage
A mortgage is usually based on your current income. Yet financial responsibilities often continue when personal circumstances change.
Illness, injury or the loss of a household income can make repayments difficult to maintain.
Protection advice should therefore be part of a wider conversation about financial resilience.
A qualified protection adviser can discuss:
- Life insurance to provide financial support following death.
- Critical illness cover for qualifying medical conditions.
- Income protection if illness or injury prevents you from working.
- Existing policies and whether they remain appropriate.
- Premiums, exclusions, waiting periods and cover limits.
You can find advisers who offer Mortgage Protection Advice through Connect Experts.
Protection products are subject to eligibility, policy terms and exclusions. An appropriate adviser should explain these before recommending cover.
Later-Life Mortgage Choices for Bridge of Allan Homeowners
Some homeowners may have spent decades building equity in their property.
Later in life, they might want to fund home improvements, support family members or review borrowing as retirement approaches.
However, accessing housing wealth requires careful consideration.
Equity release isn’t simply about how much a property is worth. The long-term cost, suitability and alternatives matter.
Homeowners can explore Equity Release Advisers in Stirlingshire through Connect Lifetime Mortgages.
An appropriately qualified adviser can explain lifetime mortgages, eligibility, potential alternatives and the implications for future plans.
Interest may accumulate on a lifetime mortgage, increasing the amount owed. Equity release can also reduce your estate’s value and affect means-tested benefits.
A suitable decision should consider your needs today and the consequences over time.
Choose a Mortgage Adviser Who Understands Your Priorities
Before choosing a Mortgage Broker in Bridge of Allan, consider what you need the adviser to understand.
The closest adviser may be convenient, but specialist experience, appropriate permissions, and clear communication matter just as much.
Ask whether the adviser:
- Has experience with your particular mortgage circumstances.
- Can explain lender criteria and the costs of different products.
- Understands relevant Scottish property-purchase requirements.
- Can support complex cases or refer you to an appropriate specialist.
- Explains their fees, regulatory status and communication process before you proceed.
Connect Experts lets you compare mortgage adviser profiles by location, expertise, language, and other available preferences.
Find a Mortgage Adviser Through Connect Experts
A good financial decision doesn’t start with the lowest number on a screen. It begins with understanding what that number means for the life you intend to build.