
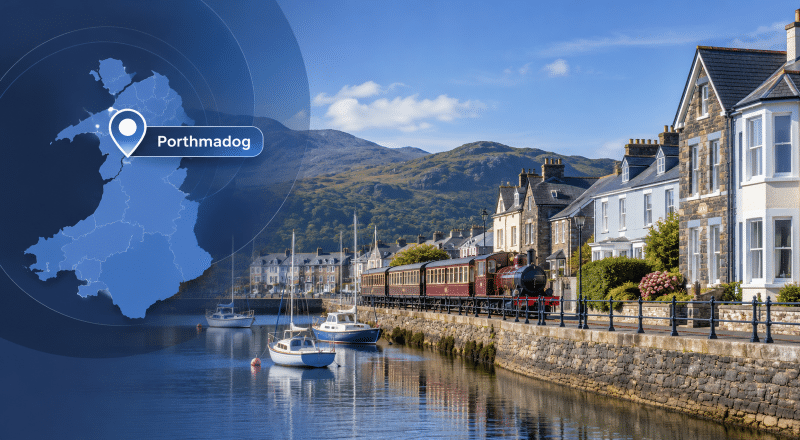
A Mortgage Broker in Porthmadog can help you separate the excitement of finding a home from the responsibility of financing it. A harbour view may capture your imagination, but mortgage terms, lender criteria and long-term costs shape what happens after you collect the keys.
Porthmadog sits beside the Glaslyn estuary, with connections to the coast, neighbouring villages and the mountains of Eryri. Its character attracts people with different intentions. Some want to settle permanently, while others may be considering a second home or rental investment.
Those intentions matter because lenders assess more than your income and deposit. Property condition, location and how you plan to use the home can influence the mortgage options available.
At a glance: Mortgage Broker in Porthmadog
- Location: Porthmadog is a harbour town in Gwynedd, North Wales, within the LL49 postcode district.
- Surrounding communities: Tremadog, Borth-y-Gest and Morfa Bychan form part of the wider Porthmadog area.
- Average house price: The average property price across Gwynedd was £204,000 in August 2026, according to provisional Office for National Statistics data.
- First-time buyers: Gwynedd’s average first-time buyer price was £176,000 in August 2026. These are county figures, not specific Porthmadog valuations.
- Property considerations: Older buildings, mixed-use premises, coastal locations and unusual access arrangements can require additional lender checks.
- Flood risk: Assess properties near rivers or coastal areas individually, rather than assuming every address has the same risk.
- Second homes: Gwynedd applies a 150% council tax premium to qualifying second homes for 2026/27, subject to exemptions.
- Language: Welsh is an important part of local life. Adviser language availability should be confirmed before arranging an appointment.
Why Porthmadog Properties Deserve a Closer Look
The strongest mortgage application starts with an accurate description of the property.
Porthmadog’s historic harbour and commercial past sit alongside established residential streets, village properties and homes closer to the coastline. These differences can affect what information a lender needs.
For example, a flat above commercial premises may be assessed differently from a conventional terraced house. An older property might require further information about its construction, condition or previous alterations.
Before applying, consider whether the property has:
- Non-standard construction or evidence of significant structural alterations.
- Shared access, unusual rights of way or complicated title arrangements.
- Commercial premises attached to or beneath the residential accommodation.
- Planning conditions or restrictions affecting residential use.
- A history of flooding or other issues relevant to insurance.
Properties near the Glaslyn estuary and coastal locations should also receive appropriate flood-risk checks.
The Natural Resources Wales flood-risk map provides an initial way to investigate a location. However, its results do not replace property-specific enquiries, surveys or insurance checks.
A Mortgage Broker in Porthmadog with relevant property-lending experience can help you understand which details lenders may request and when specialist input could be necessary.
Buying Your First Home or Moving Within Gwynedd
A mortgage needs to fit your household finances, not just the property’s asking price.
First-time buyers should consider how much they can comfortably repay, the deposit available and the additional costs of purchasing a home.
These may include legal fees, surveys, removals and Land Transaction Tax where applicable. Wales uses Land Transaction Tax rather than Stamp Duty Land Tax.
For home movers, the questions may differ.
You may have equity in your existing property, an early repayment charge on your current mortgage, or a mortgage that your lender might allow you to transfer to another home.
The best approach depends on your borrowing needs, lender criteria, and plans.
Reviewing a Mortgage Before Its Rate Ends
An approaching mortgage expiry date is an opportunity to review the full cost of your borrowing.
You can explore Mortgage Rate Ending Advisers who can help you assess remortgaging, staying with your current lender, or changing your borrowing structure.
The UK Mortgage Rates comparison tool also offers a useful starting point for comparing mortgage products, estimated repayments and fees.
A lower initial rate does not automatically mean a lower overall cost. Product fees, incentives, early repayment charges and the intended mortgage term all deserve attention.
Displayed rates do not guarantee mortgage eligibility or lender approval.
Holiday Lets, Second Homes and Property Investment
Porthmadog’s relationship with tourism creates borrowing questions that may differ from those involved in purchasing a permanent home.
A property intended for occasional personal use may require different mortgage arrangements from one intended to generate holiday rental income.
Similarly, a conventional buy-to-let mortgage may not permit short-term holiday letting.
You can explore Holiday Let Mortgage Brokers or use the First-Time Landlord Adviser Search where appropriate.
More experienced investors may need specialist advice about Portfolio Landlord Mortgages or Limited Company Buy-to-Let Mortgages.
Speaking with a Mortgage Broker in Porthmadog who understands the proposed property use can help you assess lender requirements before committing to a purchase.
Understand Gwynedd’s Second-Home Rules
The costs of owning a second property extend beyond mortgage repayments.
For 2026/27, Cyngor Gwynedd has retained a 150% council tax premium on qualifying second homes, with specific exceptions.
You can review the current position through Cyngor Gwynedd’s second-home council tax guidance.
Planning requirements also need checking.
Cyngor Gwynedd’s Article 4 Direction concerning second homes and holiday lets was quashed and is no longer in force within its local planning authority area. However, Eryri National Park has separate Article 4 controls in its own planning area.
Check the applicable planning authority, existing permissions, occupancy restrictions and tax treatment before proceeding.
For local business owners purchasing premises they intend to trade from, an Owner-Occupied Commercial Mortgage Adviser may be more appropriate than a residential mortgage specialist.
Protecting Your Mortgage and Your Household
Getting a mortgage approved is one decision. Considering how that financial commitment would be managed if your circumstances changed is another.
Illness, injury, loss of earnings or death can create significant financial difficulties for a household.
That is why mortgage planning should also include a conversation about suitable protection.
Through Connect Experts, you can search for Protection Mortgage Brokers who can discuss:
- Life insurance: Cover designed to provide financial support if an insured person dies during the policy term.
- Critical illness cover: A potential lump-sum payment following diagnosis of a specified condition covered by the policy.
- Income protection: Regular payments that may replace part of your income if illness or injury prevents you from working.
- Existing cover: Whether workplace benefits or policies you already hold provide suitable protection.
Personal protection is not automatically a condition of mortgage approval. The appropriate cover depends on your circumstances, budget, needs and policy terms.
Equity Release and Later-Life Mortgage Options in Gwynedd
For some homeowners, mortgage decisions change as retirement approaches.
You may want to clear an existing mortgage, make home improvements, help family members, or understand whether you can stay in your current home in retirement.
Equity release may be an option for eligible homeowners aged 55 or over, but it may not suit everyone.
Connect Lifetime provides a dedicated guide to Equity Release Advisers in Gwynedd.
The guidance explains how property value, construction, condition and location may influence lifetime mortgage lending. It also considers the importance of comparing other later-life borrowing arrangements.
A lifetime mortgage is secured against your home. Interest may accumulate, reducing your estate’s value. Equity release can also affect entitlement to means-tested benefits.
Specialist regulated advice should explain these consequences and reasonable alternatives before a decision is made.
Choosing a Mortgage Broker in Porthmadog
The adviser closest to your property isn’t necessarily the best fit for your mortgage.
Local knowledge can be valuable, particularly when a property has unusual characteristics. However, specialist experience, lender access and communication are equally important.
Before choosing an adviser, consider:
- Relevant experience: Does the adviser regularly deal with your type of mortgage or property?
- Lender access: Which lenders and mortgage products can they consider?
- Mortgage costs: What fees will you pay, and when?
- Communication: Are telephone, online or face-to-face appointments available?
- Language: Can the adviser explain the mortgage process in your preferred language?
- Regulatory permissions: Is the adviser or firm appropriately authorised for the services you require?
If you would prefer to discuss your finances in Welsh or another language, explore Bilingual Mortgage Brokers and confirm the individual adviser’s availability.
You can also check the adviser or firm’s regulatory status through the FCA Financial Services Register.
Choosing an adviser should involve more than finding someone who can obtain a mortgage illustration. The important question is whether they have the right knowledge and permissions to help you understand your options.
Speak to a Mortgage Broker in Porthmadog
Every mortgage decision balances what is possible today with what remains manageable tomorrow.
Whether youare buying your first property, reviewing a mortgage deal, moving to Gwynedd, or arranging finance for a rental property, the right conversation can help you identify your next steps.
Use Find a Mortgage Adviser to compare suitable advisers by location, expertise, language and personal preference.




