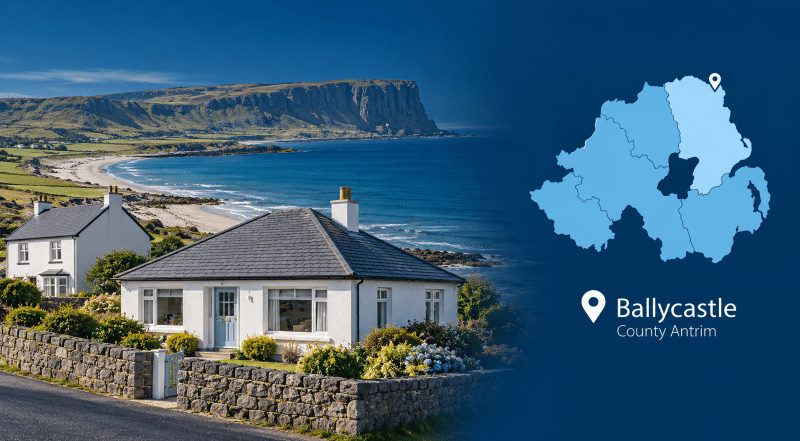
A Mortgage Broker in Ballycastle can help you make one of life’s biggest commitments with perspective, because choosing a home is rarely only about the property; it is also about the life you expect to build around it.
Ballycastle rewards that wider view. The town combines a working harbour, established streets, coastal homes and a rural hinterland, while the wider Causeway Coast and Glens area has a strong visitor economy. That variety means two properties only a short distance apart can raise very different questions for a lender.
The aim is not simply to find a mortgage. It is to understand how your income, deposit, property, intended use and future plans fit together before you commit.
At a glance: Mortgage advice in Ballycastle
- Postcode area: BT54.
- Ballycastle is a coastal town within the Causeway Coast and Glens Borough.
- Buyers may encounter traditional town-centre homes, modern housing, apartments, detached homes and more rural property outside the centre.
- Parts of Ballycastle’s historic core fall within a conservation area, so some properties may require closer attention for alterations, condition, and valuation.
- The standardised house price for Causeway Coast and Glens was £218,871 in Q2 2026, up 9.6% year on year; this is a district-level market measure, not a valuation for a Ballycastle home.
- Northern Ireland’s overall standardised house price was £202,487 in Q2 2026.
- A coastal location does not automatically mean a property is at flood risk, but buyers can check the official Northern Ireland flood maps to see whether a particular home’s location makes this relevant.
- Ballycastle’s position within a significant visitor area can make holiday letting or short-term accommodation part of some buyers’ plans, but the intended use must match the mortgage and lender criteria.
Why the property matters as much as the borrower
A Mortgage Broker in Ballycastle should look beyond the purchase price and ask what the lender will actually be asked to accept as security.
For a straightforward modern house, the property side of the application may be relatively simple. Older homes, converted buildings, properties near commercial use, homes in or around a conservation area, or rural properties with land and outbuildings may require more detailed information.
Useful questions can include:
- What is the property built from, and does it meet mainstream lending construction standards?
- Is it freehold or leasehold?
- Are there shared access arrangements or private roads?
- Does the property rely on private drainage or another non-standard service?
- Is there land, an annexe, workshop or outbuilding?
- Will any part of the property be used for business?
- Is the property intended only as your home, or will you let any part?
- Are there planning, conservation or condition issues that may affect valuation?
- Does the location or survey identify a flood, coastal or structural consideration that needs further investigation?
A mortgage valuation is carried out for the lender. It is not the same as a survey for the buyer, so you may also want independent survey advice where the age, condition or location of the property justifies it.
Buying a home in Ballycastle
For an owner-occupier, a Mortgage Broker in Ballycastle can help you work through affordability before you become emotionally committed to a particular property.
Lenders can assess salary, overtime, bonuses, self-employed income, debts, childcare costs, credit commitments and other expenditure differently. Your deposit size matters, but so does the sustainability of the monthly payment after the initial mortgage deal ends.
If you are buying your first home, it can help to establish:
- your available deposit and its source;
- an affordable price range rather than the maximum theoretical loan;
- the documents a lender is likely to request;
- whether your credit file contains anything that should be addressed before an application;
- the likely property costs beyond the deposit, including legal work, surveys, insurance and Northern Ireland domestic rates. Property rates are an ongoing ownership cost in Northern Ireland.
If you already own a home, the same planning applies when moving. The timing of a sale and purchase, any early repayment charge on your existing mortgage and whether your current mortgage can be ported may all influence the route you take.
If your current deal is nearing its end, use the Mortgage Rate Ending adviser search to find an adviser who can help you compare a product transfer with a remortgage.
A property you plan to let
Ballycastle’s location on the Causeway Coast means some buyers may consider a property for rental or short-term visitor accommodation. The key is to decide the intended use before arranging finance.
A residential mortgage is generally not designed for a property that will be run as a rental business. Standard buy-to-let and short-term letting can also be assessed differently, particularly where income is seasonal or the owner wants occasional personal use.
Depending on your plans, useful adviser searches include:
- First-Time Landlord if this will be your first rental property.
- Portfolio Landlord if the property will form part of a wider portfolio.
- Limited Company BTL if you are considering company ownership.
- Short-Term BTL Bridge Loans where a short-term funding requirement genuinely fits the transaction.
Tax treatment, licensing, planning, insurance and local letting rules are separate from the mortgage decision, so specialist legal and tax advice may also be appropriate.
Compare mortgage rates, but compare the whole deal
A Mortgage Broker in Ballycastle can help you distinguish between a rate that looks attractive and a mortgage that is suitable when the full cost is considered.
You can review current products using the UK Mortgage Rates comparison page. A lower headline rate can still cost more over the period you expect to keep the mortgage if it comes with a higher product fee, valuation cost, legal cost or restrictive early repayment charge.
When comparing options, consider:
- the initial rate;
- monthly repayments;
- product and arrangement fees;
- valuation and legal costs;
- cashback or incentives;
- early repayment charges;
- overpayment rules;
- the rate or product you may move to when the initial deal ends;
- whether the mortgage still fits if your plans change.
The best comparison is therefore not “Which rate is lowest?” but “Which overall arrangement works for the way I expect to live and borrow?”
Protection advice: planning beyond completion
A mortgage can last for decades, while life rarely follows a fixed timetable. A Mortgage Broker in Ballycastle can therefore join a wider conversation about what happens if illness, injury, loss of income, or death affects the household.
Through Protection Mortgage Brokers, clients can find advisers who can discuss protection needs alongside the mortgage. Depending on the circumstances, this may include life insurance, critical illness cover, income protection or other relevant cover.
Protection should be based on the people, income and commitments involved rather than treated as an automatic add-on. Existing workplace benefits and policies should also be considered before new cover is recommended.
Later-life borrowing and equity release in County Antrim
For homeowners approaching or already in later life, the right question may not be whether a conventional mortgage can be arranged, but which form of borrowing best supports the next stage of life.
The dedicated Equity Release Advisers in County Antrim page on Connect Lifetime explains how property type, value, existing borrowing and long-term plans can affect equity release and lifetime mortgage advice. The County Antrim page is live and specifically addresses these property and later-life considerations.
Equity release can reduce an estate’s value and may affect entitlement to means-tested benefits. Interest can also build over time. Regulated advice should therefore consider alternatives, future needs and the effect on the homeowner and family before any recommendation is made.
Choosing an adviser: local understanding without limiting your choice
The nearest adviser is not automatically the right adviser.
A Mortgage Broker in Ballycastle may be valuable because they understand the questions that can arise around coastal, rural or tourism-related property. Yet specialist experience, lender access, communication and the ability to handle your particular circumstances may matter just as much as physical distance.
Before choosing an adviser, consider:
- whether they regularly deal with your type of mortgage;
- whether they understand the type of property you want to finance;
- which lenders and products they can consider;
- how their fees work and when those fees become payable;
- whether they offer telephone, online or face-to-face appointments;
- whether the adviser and firm hold the permissions required for the advice you need.
Connect Experts helps you compare advisers by location, expertise, and personal preference, so you can choose the person whose experience best matches the decision in front of you.