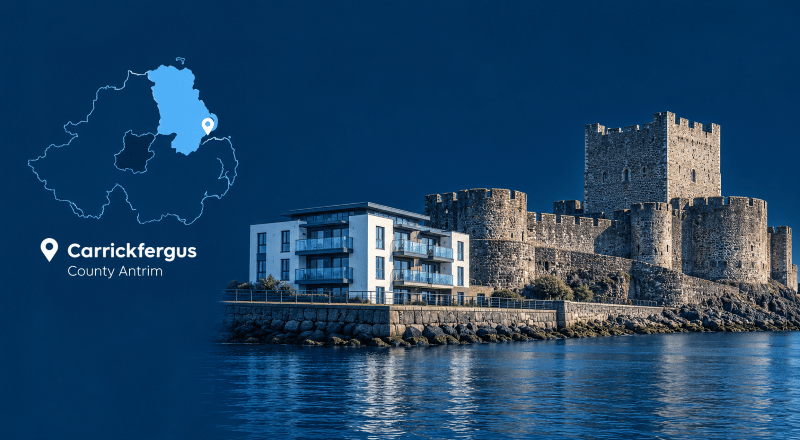
A Mortgage Broker in Carrickfergus can help turn a property search into a more deliberate financial decision. Carrickfergus has spent centuries looking outward across Belfast Lough, yet buying a home here still comes down to a simple principle: the strongest plans are built by understanding both the property in front of you and the life you want it to support.
The town combines a historic core, established residential neighbourhoods, flats, family homes and newer development. That variety matters because lenders do not assess a postcode in isolation. They assess the applicant, the property, the valuation, the deposit and the purpose of the borrowing together.
At a glance: Carrickfergus mortgage planning
- Carrickfergus sits on the north shore of Belfast Lough in County Antrim.
- Carrickfergus addresses are primarily within the BT38 postcode district.
- The historic core, castle and harbour form part of the Carrickfergus Conservation Area.
- Mid and East Antrim’s standardised average house price was £177,450 in Q2 2026.
- Rail services connect Carrickfergus with Belfast and other destinations along the line towards Whitehead and Larne.
- Buyers may encounter older town-centre homes, conventional suburban properties, flats, and ongoing residential development.
- Local knowledge helps, but your adviser’s experience with your income, mortgage type, and property may matter just as much.
A town where the property can change the mortgage questions
Carrickfergus is not one uniform housing market.
A home close to the historic centre may raise different questions from a modern property on a newer development or a flat closer to Belfast Lough. Carrickfergus’s conservation area includes its historic core, castle and harbour, reflecting a built environment that has developed over centuries.
For an older property, a lender’s valuer may pay particular attention to condition, construction, signs of structural movement, roof condition, damp, previous alterations or anything that could affect future marketability.
A property within or close to a conservation area may also require extra care when you consider alterations or future renovation work.
A newer home can create a different checklist. Depending on the property and lender, questions may include the build stage, warranty arrangements, developer incentives, and whether you’re buying before completion.
Flats and apartments can raise additional questions about tenure, management arrangements, service charges, and the remaining lease term, where applicable.
This is where a Mortgage Broker in Carrickfergus can be useful: not because every Carrickfergus home is unusual, but because the lender needs to be comfortable with both the borrower and the property being offered as security.
Match the property to the questions
| Property or plan | Questions worth raising early |
|---|---|
| Older or historic home | What is the construction? Have major alterations been completed? Could condition influence valuation? |
| Flat or apartment | What is the tenure? Are there service charges or management arrangements? What lease terms apply? |
| Newer development | Is an acceptable warranty available? Are developer incentives involved? When will the property be completed? |
| Home needing substantial work | Is the property currently mortgageable, or might renovation finance be more appropriate? |
| Property being let | What rent is expected, and will it meet the lender’s rental calculation requirements? |
| Commercial or development project | Is a standard mortgage appropriate, or does the project need specialist property finance? |
What should you prepare before speaking to an adviser?
A well-prepared conversation can save time later.
Before an adviser recommends a lender or mortgage route, expect questions about:
- your income and employment status;
- deposit and source of funds;
- existing credit commitments;
- credit history;
- the property’s value and purchase price;
- whether you are buying, remortgaging or letting the property;
- your expected mortgage term;
- monthly expenditure and future plans;
- any unusual features of the property.
If you are employed, recent payslips and bank statements may be required. If you are self-employed, lenders can request accounts, tax calculations or other evidence of income. Requirements differ between lenders and can also depend on how your income is structured.
The aim should not simply be to discover the largest mortgage available.
The aim is to establish what is affordable, sustainable, and suitable for the move you are actually making.
Carrickfergus house prices: use the right geography
Property statistics are only useful when the geography behind them is understood.
Northern Ireland’s official house-price statistics are largely published by local government district, rather than by historic county or every individual town.
For April to June 2026, the latest official figures available at the time of writing recorded a standardised average property price of £177,450 in Mid and East Antrim. The Northern Ireland average was £202,487.
Those figures provide market context. They are not a valuation of an individual Carrickfergus property.
A lender will still rely on its own valuation and underwriting process. Two homes a short distance apart can produce different outcomes because of condition, construction, tenure, demand, comparable sales or other property-specific factors.
A Mortgage Broker in Carrickfergus should use local price data as context, not a shortcut, for predicting how a lender will value your chosen home.
First-time buyers: start with affordability, not the asking price
For a first-time buyer, the most useful early question is rarely “What is the maximum I can borrow?”
A better question is:
“What level of borrowing still leaves room for the rest of my life?”
Alongside your deposit, consider legal costs, mortgage or valuation fees, survey costs, moving expenses, Stamp Duty Land Tax where applicable and the cost of Northern Ireland domestic rates.
Northern Ireland buyers become responsible for domestic rates when they own their home, and Land & Property Services should be informed when ownership changes.
You can also compare first-time buyer mortgage advisers and discuss how affordability, deposit size, income structure and credit history may influence the lenders available before making an offer.
Moving home or remortgaging in Carrickfergus
A move may be driven by the need for more space, better transport access, a change in work, family circumstances, or simply because the current home no longer fits the next chapter.
If you already have a mortgage, establish:
- whether your existing mortgage can potentially be ported;
- whether early repayment charges apply;
- whether you require additional borrowing;
- whether your current lender will reassess affordability;
- whether the new property meets the lender’s criteria.
Porting does not automatically guarantee approval for the new property. Your circumstances and the new security usually need to meet the lender’s requirements.
If your current mortgage deal is ending, compare the cost of remaining with your existing lender against a full remortgage.
The lowest headline rate is not automatically the cheapest solution after product fees, valuation costs, legal work, incentives and early repayment charges are considered.
Landlords approaching the end of a buy-to-let deal can also search for a mortgage rate ending adviser.
Buying a property to let out
Carrickfergus may appeal to different types of landlords, but you should assess a rental property on its own numbers rather than on general assumptions about the location.
Buy-to-let lenders commonly consider:
- expected monthly rent;
- deposit or equity;
- property type;
- borrower profile;
- credit history;
- landlord experience;
- ownership structure;
- the lender’s rental stress calculation.
Depending on your circumstances, useful searches include:
- first-time landlord mortgage advisers if this will be your first rental property;
- portfolio landlord mortgage advisers when several properties already form part of the portfolio;
- limited company buy-to-let advisers where you are considering purchasing through a company structure.
Mortgage advice should not replace tax or legal advice. Ownership structure, taxation and landlord responsibilities may need to be discussed with the relevant professional before committing to the purchase.
Compare the mortgage, not simply the interest rate
A rate can catch your attention.
The total deal deserves your attention.
When comparing mortgages, consider:
- the initial interest rate;
- arrangement or product fees;
- valuation and legal incentives;
- cashback;
- early repayment charges;
- how long the initial deal lasts;
- what happens when that deal ends;
- the overall mortgage term;
- permitted overpayments;
- whether the mortgage provides the flexibility you may need later.
You can review UK mortgage rates as a starting point. The comparison results are illustrative, not confirmation that you qualify, because lender underwriting and property checks still apply.
A Mortgage Broker in Carrickfergus can help compare the cost and suitability of a mortgage rather than treating the lowest visible percentage as the automatic winner.
Protection should sit beside the mortgage conversation
A mortgage may last for decades.
That makes it worth considering not only whether the payment is affordable today, but how the household would cope if income or health changed before the mortgage ended.
Protection advice for mortgage clients can include discussions about:
- life insurance;
- critical illness cover;
- income protection;
- mortgage-related protection;
- existing workplace benefits;
- existing insurance arrangements.
The right combination depends on your mortgage balance, income, dependants, savings, employment arrangements, existing cover, and budget.
Protection isn’t about assuming something will go wrong.
It is about deciding which financial risks you are comfortable carrying yourself and which you would prefer to insure.
When comparing a Mortgage Broker in Carrickfergus, ask whether protection can be reviewed alongside your mortgage so that the borrowing and the financial safety net are considered together.
Later-life property decisions in County Antrim
Later in life, the property question can change.
Instead of asking how to buy the home, homeowners may be considering how to repay an existing mortgage, release capital, fund improvements, support family members or reorganise their finances for retirement.
Homeowners exploring this area can read more about equity release advisers in County Antrim.
Equity release is not suitable for everyone. It can reduce an estate’s value, affect future financial choices, and potentially affect entitlement to means-tested benefits. Alternatives should therefore be considered before a recommendation is made.
The value of a home is only one part of that decision. Age, existing borrowing, property suitability, long-term plans and the reason money is needed can all matter.
When the property plan needs specialist finance
Not every Carrickfergus property transaction belongs inside a conventional residential mortgage.
Someone buying land or a property for substantial redevelopment may face very different lender questions than someone buying an ordinary home.
For suitable projects, you can search for development finance advisers.
If the property will house your business rather than serve as your residence, an owner-occupied commercial mortgage adviser may be more relevant.
Specialist lenders can examine areas such as:
- current property value;
- expected value after works;
- loan-to-value;
- project costs;
- borrower or developer experience;
- planning position;
- proposed property use;
- repayment or refinance strategy.
The type of finance should follow the property’s purpose, rather than forcing the project into a mortgage category that doesn’t fit.
Does your adviser need to be based in Carrickfergus?
Not necessarily.
Local knowledge can be valuable, particularly when the property has characteristics that benefit from understanding the surrounding market. A local adviser may also offer face-to-face appointments.
But the closest adviser isn’t automatically the most suitable.
Before choosing whom to contact, consider:
- Mortgage experience: Do they regularly advise on the borrowing you need?
- Property knowledge: Are they comfortable discussing your type of property?
- Lender access: Which lenders and mortgage products can they consider?
- Fees: What will you pay and at what stage?
- Communication: Can you work by telephone, video or face-to-face?
- Regulation: Does the firm have the permissions required for the advice you need?
The FCA recommends checking a financial-services firm’s authorisation and permissions before buying a financial product or service.
Use the FCA Financial Services Register to check regulatory information.
Telephone and video appointments also mean your search does not have to stop at the edge of BT38. Specialist experience may sometimes be more valuable than physical distance.
Make the next decision clearer
Property decisions rarely become better simply because we make them faster.
Clarity usually comes from asking better questions before committing.
Use Connect Experts to find a Mortgage Broker in Carrickfergus, compare adviser profiles and choose someone whose experience matches your property, borrowing requirements and preferred way of communicating.
The right adviser cannot remove every uncertainty from buying, refinancing or investing in property.
They can help make sure the important uncertainties are understood before they become expensive surprises.