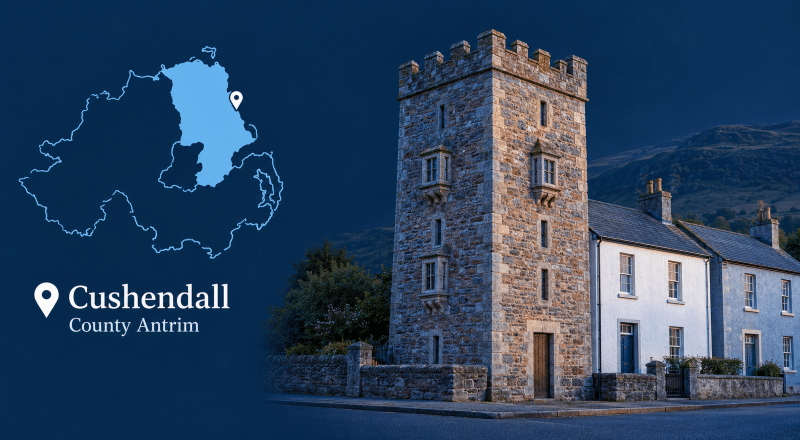
A Mortgage Broker in Cushendall can help you look beyond the rate and ask a more important question: does the mortgage fit the property, your finances and the life you want to build in BT44?
Cushendall rewards careful decisions. The village sits between the Antrim Glens and the coast, where historic streets, established homes and a remarkable landscape create a property market that cannot always be understood from a postcode and purchase price alone.
For some buyers, the property will be straightforward. For others, age, condition, construction, access, surrounding land or proposed use may influence which lenders are comfortable with the application.
Good mortgage advice should bring those details into the conversation before a product is chosen.
At a glance: mortgage advice in Cushendall
- Cushendall is within the BT44 postcode district in County Antrim.
- Causeway Coast and Glens Borough Council describes Cushendall as a hub of the eastern Glens.
- The Cushendall Conservation Area was designated in 1975 and includes its historic core and older parts of Kilnadore Road and Coast Road.
- Cushendall lies within the Antrim Coast and Glens Area of Outstanding Natural Beauty.
- NISRA reported Northern Ireland’s standardised average house price was £202,487 in Q2 2026.
- Older, altered, rural or unusually situated properties may require more detailed lender and valuation checks.
- Adviser experience with the borrower and property can matter more than physical distance.
Why Cushendall property needs more than a rate search
A beautiful setting does not make a mortgage complicated. The details of an individual property can.
Cushendall includes traditional village housing, period property, later residential development and homes on the approaches to the surrounding Glens.
A lender may want to understand construction, condition, access, title, occupancy and future marketability before confirming that a property meets its criteria.
The historic core also sits within the Cushendall Conservation Area.
Conservation status does not prevent mortgage lending. However, buyers planning alterations should understand the planning position and whether restrictions could affect proposed work.
Properties outside the centre may raise different questions.
A larger plot, private access, outbuildings, surrounding land, non-standard services or combined residential and business use can require a lender with suitable criteria.
The wider landscape also matters. The Antrim Coast and Glens AONB covers a distinctive mix of coastline, valleys, farmland and upland terrain.
What should a Mortgage Broker in Cushendall understand?
The right starting point is not simply:
“What can I borrow?”
A better question is:
“What am I buying, how will I use it, and which lenders are comfortable with that combination?”
Your adviser may need to consider:
- your income and employment structure;
- your deposit size and source;
- existing credit commitments;
- the property’s age and construction;
- whether land or outbuildings are included;
- property access and services;
- whether part of the property will be used for business;
- whether the property will be your home or let to tenants;
- your intended mortgage term;
- how long you expect to keep the initial mortgage deal.
That information can narrow the lender search before an unsuitable application creates unnecessary credit checks, valuation costs or delay.
Compare the mortgage, not just the headline rate
A low interest rate can attract attention. It does not automatically make a mortgage the lowest-cost option.
Product fees, valuation charges, cashback, incentives, early repayment charges, and how long you intend to keep the deal can all affect the comparison.
A fixed rate may provide payment certainty for a defined period. Tracker and other variable-rate products behave differently when their underlying rate changes.
You can use the UK mortgage rates comparison page as a starting point to view current products, estimated repayments, and lender fees.
The results do not confirm eligibility. Lender affordability, credit and property criteria still apply.
A Mortgage Broker in Cushendall can help compare mortgage costs alongside the lender’s criteria, rather than treating the interest rate as the whole decision.
Buying your first home in Cushendall
First-time buyers often focus on saving for a deposit.
The stronger approach is to prepare the complete application.
That may include:
- evidence of income;
- recent bank statements;
- existing credit commitments;
- proof of deposit;
- identification;
- address evidence;
- details of any gifted deposit;
- information about the property.
Before viewing seriously, establish a realistic borrowing range.
Then leave enough financial flexibility for legal costs, surveys, insurance, moving expenses and repairs that may be required after completion.
An older home may also justify a more detailed survey than a buyer initially expected.
The aim is not simply to reach completion. It is to arrive there knowing what you have bought and what it will cost to own.
When your current mortgage rate is ending
Start a remortgage from the date your current deal ends, not the day it actually expires.
Reviewing your position earlier gives you time to compare a new lender with any product-transfer options available from your existing lender.
It can also reveal:
- early repayment charges;
- affordability changes;
- changes in income;
- increased property value;
- additional borrowing requirements;
- lender criteria that have changed since your previous application.
If your current fixed or discounted period is approaching its end, use the Mortgage Rate Ending adviser search to find an adviser experienced in remortgage planning.
A cheaper-looking rate is only useful when the mortgage remains suitable for what comes next.
If the Cushendall property will be let
The finance route depends heavily on how the property will be owned and occupied.
Someone becoming a landlord for the first time may face different lender criteria from an experienced investor.
You can search specifically for a First Time Landlord mortgage adviser.
Landlords with several properties may benefit from an adviser experienced with Portfolio Landlord mortgages, because a lender may review the wider portfolio as well as the property being financed.
Buying through a company can introduce another layer of underwriting. Where appropriate, search for a Limited Company buy-to-let adviser.
For properties genuinely being operated as houses in multiple occupation, an adviser experienced with HMO property mortgages may be more appropriate.
Cushendall’s position within a popular coastal and Glens destination may also lead some buyers to consider short-stay use.
That should not be assumed to fit an ordinary residential or conventional buy-to-let mortgage.
Tell your adviser exactly how you intend to use the property before choosing the finance.
Renovation, development and specialist property finance
Sometimes the property means an ordinary mortgage isn’t the right starting point.
A property requiring substantial work may not initially satisfy mainstream mortgage criteria.
Depending on the project, a short-term bridging loan adviser may consider whether temporary finance is appropriate. A clear repayment or refinancing strategy would normally form an important part of that assessment.
More extensive building projects can require specialist development finance advice instead.
The distinction matters.
Refurbishing an existing home and undertaking a development project are not necessarily financed in the same way.
When the property has a commercial purpose
Cushendall’s village centre combines residential life with shops, hospitality and other local businesses.
A property used by your own trading business may require owner-occupied commercial mortgage advice rather than residential borrowing.
For a commercial building being purchased to generate rental income, an investment property commercial adviser may need to consider:
- the property type;
- proposed tenant;
- lease terms;
- rental income;
- applicant experience;
- deposit;
- the strength of the investment proposition.
The same building can require a very different finance solution depending on who occupies it and why.
Protection should be discussed alongside the mortgage
A mortgage helps finance the property.
Protection planning asks what happens to that mortgage if life changes unexpectedly.
Suitable advice might include:
- life cover;
- critical illness cover;
- income protection;
- other protection arranged around household liabilities and financial commitments.
The right cover depends on your circumstances, workplace benefits, savings, dependants, and budget.
A mortgage adviser may provide protection advice where appropriately authorised or introduce a suitable specialist.
You can search Connect Experts for Protection Mortgage Brokers.
Protection is not about buying every policy available.
It is about identifying the risks your household would find difficult to absorb without financial support.
Choosing an adviser: local knowledge or specialist experience?
The nearest adviser is not necessarily the best match.
Local familiarity can help when a property has unusual features.
However, specialist experience, lender access, communication and regulatory permissions can be equally important.
Before proceeding, consider asking:
- Does the adviser regularly arrange your type of mortgage?
- Have they dealt with properties similar to yours?
- Can they explain how the property may affect lender selection?
- Which lenders and products can they consider?
- What adviser fees will you pay?
- When are those fees payable?
- How will they communicate with you?
- Who handles the case after application?
- Is the adviser or firm appropriately authorised or registered?
The Financial Conduct Authority recommends checking a financial firm before purchasing a regulated financial product.
You can use the FCA Firm Checker and the Financial Services Register to confirm a firm’s regulatory status and relevant permissions.
Your adviser does not need to be on the same street
Telephone and video appointments mean your adviser search can extend beyond Cushendall.
That may be particularly useful where your application needs expertise in areas such as:
- self-employed income;
- unusual property construction;
- complex income;
- buy-to-let;
- portfolio lending;
- commercial mortgages;
- bridging;
- development finance;
- historic credit problems.
A Mortgage Broker in Cushendall should still understand the property information that matters locally, even when the adviser is based elsewhere.
The goal is not to find the shortest distance between you and an adviser.
It is to find the shortest route to a properly prepared application.
Prepare before the lender asks
Good preparation can remove avoidable delays later.
Depending on your circumstances, useful documents can include:
- recent payslips;
- accounts;
- SA302s and tax year overviews where required;
- bank statements;
- identification;
- address evidence;
- deposit evidence;
- details of outstanding credit;
- property particulars;
- information about land or outbuildings;
- tenancy information for a let property;
- company or business information for commercial borrowing.
For an unusual property, provide accurate information from the beginning.
A detail that appears minor to the buyer may be significant to the lender or valuer.
That does not mean the property cannot be financed.
It means the right lender needs the right information.
Make the Cushendall move with the whole picture in view
Property decisions often begin with emotion.
Mortgage decisions work best when that emotion is supported by evidence.
Cushendall offers something genuinely distinctive: historic character, the Glens, the coast and a community surrounded by one of Northern Ireland’s recognised landscapes.
Yet the fundamentals of borrowing remain practical.
Affordability matters.
Property suitability matters.
Lender criteria matter.
The total cost matters.
And how comfortably the mortgage fits tomorrow matters just as much as whether it works today.
A Mortgage Broker in Cushendall can help bring those pieces together before you commit to a mortgage product or application.
Find a mortgage adviser through Connect Experts and search by expertise and location.