A Mortgage Broker in Newtownabbey can help turn a property decision into a clearer financial plan, because the right mortgage is rarely just about borrowing the maximum amount. It is about understanding the home, the applicant and the years that come after completion.
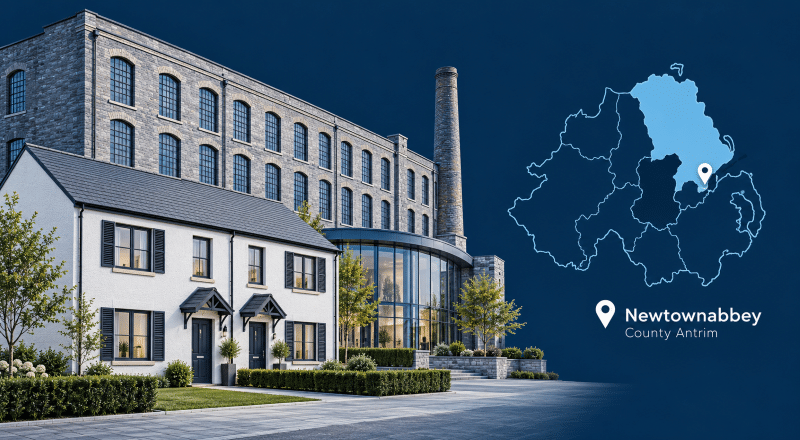
Newtownabbey sits immediately north of Belfast and combines established residential neighbourhoods, commuter routes, Belfast Lough frontage and important employment and commercial areas. That mix means the mortgage questions raised by one property can differ sharply from those raised just a few miles away.
At a glance: buying and borrowing in Newtownabbey
- Newtownabbey is mainly covered by the BT36 and BT37 postcode districts, including Glengormley, Carnmoney, Mossley, Whiteabbey, Jordanstown, Monkstown and Rathcoole.
- The M2 and M5 form part of the borough’s major transport network, while the A2 follows the Belfast Lough side of Newtownabbey towards Jordanstown and Carrickfergus.
- The average house price in Antrim and Newtownabbey was £206,000 between April and June 2026, up 8.8% from the same period in 2025.
- Some properties may require closer checks on construction type, tenure, valuation or insurance before a lender will proceed.
- Landlords and business owners may need specialist advice where the property or borrowing purpose falls outside standard residential lending.
- Adviser experience, lender access and understanding of the property can matter more than choosing the closest adviser.
Newtownabbey is not one type of property market
A Mortgage Broker in Newtownabbey should first understand what you are buying rather than treating the postcode as a complete description of the case.
A conventional semi-detached home around Glengormley or Carnmoney may fit mainstream lender criteria very differently from an apartment or house closer to Belfast Lough. Homes around Jordanstown and Whiteabbey may have different valuation, location, and insurance considerations than properties further inland around Mossley or Carnmoney.
There is also a useful technical point for buyers.
The Northern Ireland Housing Executive publishes information identifying some Newtownabbey addresses within its non-standard housing records. That does not mean every property in the surrounding area is affected or that a mortgage is unavailable. It means the construction of the individual property should be established early where there is any doubt. Lender appetite, valuation requirements and available loan-to-value can differ for non-standard construction.
That small piece of research before an application can prevent a much bigger problem later.
What the local property data tells buyers
The Office for National Statistics reported an average house price of £206,000 in Antrim and Newtownabbey for April to June 2026, compared with £189,000 a year earlier. The figure is provisional and covers the wider local authority, not Newtownabbey alone, so it provides market context rather than a valuation for an individual property.
The same ONS data shows average advertised private rent of £796 per month in the Lough Neagh Upper broad rental market area in July 2026. Again, this is a wider rental-market figure, not a Newtownabbey-specific rent.
For authoritative market context, see ONS housing prices in Antrim and Newtownabbey.
A Mortgage Broker in Newtownabbey can put those figures alongside the lender’s actual affordability rules, your deposit and the valuation of the property you want to buy.
Market averages show what’s happening around you.
A mortgage application still depends on your situation and the property you’re buying.
Buying, moving or reviewing an existing mortgage
Where you are in the property cycle should influence the advice.
For a purchase, an adviser may need to consider deposit evidence, income, employment structure, existing commitments, credit history and the proposed property before recommending a lender.
If your existing mortgage deal is approaching its end, use the mortgage rate ending adviser search to find advisers who can compare a potential product transfer with remortgaging to another lender.
Starting the review before your existing deal expires gives you more time to consider early repayment charges, valuation requirements, affordability, and product availability.
You can also compare current UK mortgage rates as a starting point.
A headline interest rate should never be viewed alone. Product fees, cashback, loan-to-value, mortgage term, early repayment charges, and lender criteria can change a deal’s overall value.
A Mortgage Broker in Newtownabbey should therefore explain not only which rates are available, but also why a particular mortgage fits your circumstances.
Newtownabbey landlords need the right lending route
Newtownabbey’s relationship with Belfast, its transport links and its established residential communities can make the area relevant to landlords. However, the mortgage structure should follow the property and investment strategy, not the other way around.
Someone buying their first rental property can search for a first-time landlord mortgage adviser who can explain deposit requirements, rental stress testing and lender criteria.
Investors considering a company structure can instead explore limited company buy-to-let mortgage advice.
Experienced landlords may also need an adviser who understands portfolio assessment, existing borrowing, rental coverage and lender exposure limits.
The important question is not simply whether a property could be rented.
It is whether the expected rent, property type, borrower, ownership structure and intended tenancy meet the lender’s requirements.
Commercial borrowing around Newtownabbey and Mallusk
Newtownabbey also has a commercial side that shouldn’t be lost on a residential mortgage page.
Mallusk forms part of the area’s business and employment landscape, so some property enquiries will fall outside ordinary residential mortgage lending.
A business buying premises to trade from may need owner-occupied commercial mortgage advice.
Someone purchasing business premises to let to another company may instead need advice on commercial investment property finance.
Commercial lending can involve different valuation methods, deposits, affordability assessments, leases and lender requirements.
A specialist adviser in Newtownabbey can help establish whether the property and borrowing purpose require residential, buy-to-let, semi-commercial or fully commercial finance before the application reaches a lender.
Protection should sit beside the mortgage conversation
A mortgage is not simply a way to buy a home. It is also a commitment to future payments.
That makes protection part of the financial conversation.
Protection advice can help clients consider how their mortgage and essential household costs might be managed if illness, injury, loss of income or death changes the household’s finances.
Depending on individual circumstances, advice may include:
- life insurance;
- critical illness cover;
- income protection;
- mortgage payment protection.
Clients can search for protection mortgage brokers through Connect Experts.
Working with a Mortgage Broker in Newtownabbey who can also discuss protection helps connect the borrowing decision with the financial resilience needed to support it over the years ahead.
Choosing the right adviser for your Newtownabbey plans
The nearest mortgage adviser is not automatically the best fit.
Before choosing someone, consider their experience with the type of borrowing and property involved.
Ask whether they regularly deal with residential purchases, remortgages, unusual construction, buy-to-let property or commercial lending where relevant. Understand which lenders they can consider, how their fees work and when those fees become payable.
You should also establish whether appointments are available by telephone, video or face-to-face and whether the adviser or firm has the appropriate regulatory permissions for the advice you need.
The best advice should clarify the decision before it speeds up the application.
A Mortgage Broker in Newtownabbey should help you understand the lender, the property, the costs and the risks before you commit.
The mortgage completes on one day.
The decision behind it may shape your finances for years.