
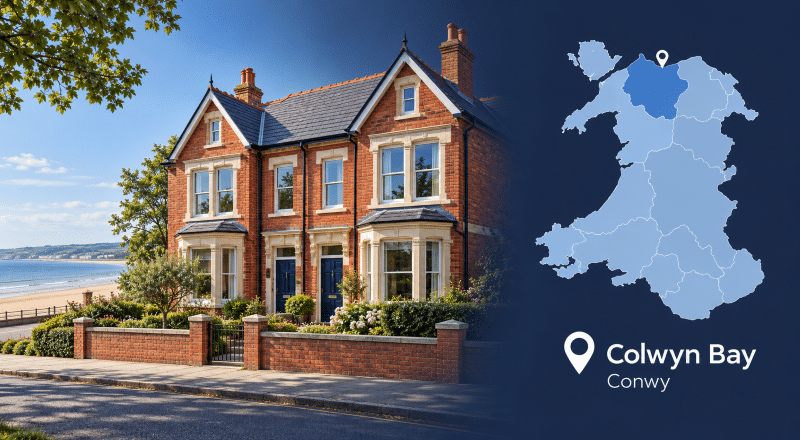
A Mortgage Broker in Colwyn Bay can help you consider something a postcode alone cannot explain: whether your finances, the property and the lender are genuinely suited to each other.
Buying beside the North Wales coast can involve very different properties within a relatively small area. Victorian and Edwardian homes sit alongside flats, modern developments, hillside houses and properties close to the waterfront.
That variety matters.
A mortgage decision should therefore begin with understanding what you are buying and how you intend to finance it, rather than simply asking which lender advertises the lowest rate.
At a glance: Colwyn Bay mortgage considerations
- Colwyn Bay is a coastal town within Conwy County Borough.
- The main postcode district for Colwyn Bay is LL29.
- Conwy’s average house price was £218,000 in August 2026.
- First-time buyers in Conwy paid £190,000 on average.
- Mortgage-funded purchases averaged £223,000.
- Colwyn Bay Town Centre and nearby Pwllycrochan are designated conservation areas.
- Old Colwyn and Rhos-on-Sea also have designated conservation areas.
- Rydal Penrhos is an independent school based in Colwyn Bay.
- Coastal position, property age and construction can influence lender assessment.
- The most appropriate adviser may not necessarily be the geographically closest one.
ONS figures are provisional and can change as transactions are recorded.
Colwyn Bay Property Is More Varied Than the Address Suggests
Two homes a few streets apart can present very different mortgage questions.
One applicant may be buying a conventional semi-detached property away from the waterfront. Another may be considering an older apartment, converted building or substantial period property.
A third buyer may choose a home with elevated coastal views where access, retaining walls, construction or exposure deserve closer examination.
That is why working with a Mortgage Broker in Colwyn Bay should involve more than establishing the purchase price.
An adviser may need to understand:
- the property’s age and construction;
- whether it has been significantly altered;
- whether it is freehold or leasehold;
- remaining lease length where relevant;
- service charges and ground rent;
- proximity to commercial premises;
- any unusual access arrangements;
- outbuildings, land or annexes;
- the intended use of the property;
- valuation comments raised by the lender.
The lender ultimately decides whether the property provides acceptable security.
Conservation Areas: Character Can Come With Questions
Part of Colwyn Bay’s appeal comes from established streets and buildings that give different parts of the town their character.
Conwy County Borough Council lists Colwyn Bay Town Centre Conservation Area and Pwllycrochan Conservation Area. Nearby Old Colwyn and Rhos-on-Sea also have designated conservation areas.
Being within a conservation area does not automatically make a property difficult to mortgage.
However, buyers should establish whether previous alterations had the necessary permission and whether proposed changes may face additional planning controls.
Your solicitor can investigate the legal position.
The lender’s valuer will consider whether the property represents suitable mortgage security.
Those are separate questions, and both matter.
What Do Current Conwy House Prices Tell Buyers?
Price statistics provide context. They do not tell a lender what one particular property is worth.
The Office for National Statistics reported an average Conwy house price of £218,000 in August 2026, up 3.0% year on year.
Average prices by property type were:
- Detached: £322,000
- Semi-detached: £225,000
- Terraced: £176,000
- Flats and maisonettes: £128,000
First-time buyers paid an average of £190,000, while properties bought with mortgages averaged £223,000.
These figures help you understand the wider market.
They should never replace a valuation of the actual property.
A lender is financing one address, not the Conwy average.
Compare the Mortgage, Not Just the Rate
A low interest rate can attract attention. Yet the lowest advertised rate doesn’t always mean the lowest overall borrowing cost.
Before choosing a mortgage, consider:
- initial interest rate;
- product fee;
- valuation fee;
- legal costs;
- cashback;
- early repayment charges;
- loan-to-value;
- mortgage term;
- repayment basis;
- lender criteria;
- total cost over the relevant period.
You can review current UK mortgage rates before discussing your circumstances with an adviser.
This can provide useful market context around current mortgage rates UK borrowers may encounter, including fixed mortgage rates, remortgage rates and different loan-to-value bands.
However, availability depends on your circumstances and lender criteria.
Buying Your First Home in Colwyn Bay
For a first-time buyer, the mortgage is only one part of becoming a homeowner.
Deposit evidence, affordability, legal costs and ongoing household expenditure also matter.
The ONS reported that first-time buyers across Conwy paid an average of £190,000 in August 2026.
That figure doesn’t tell you what you should spend.
A Mortgage Broker in Colwyn Bay can assess affordability against your income, commitments, deposit and intended property.
Before viewing homes seriously, it can help to establish:
- your available deposit;
- likely borrowing range;
- monthly payment comfort;
- credit position;
- documentation required;
- whether an agreement in principle is appropriate.
Knowing the boundaries before making an offer can reduce avoidable uncertainty later.
Moving Home Along the North Wales Coast
A home move often creates two financial decisions at once.
You are selling one property while arranging finance for another.
Your existing mortgage may be portable, but portability does not guarantee that the lender will approve the new borrowing.
The lender may reassess:
- income;
- expenditure;
- credit commitments;
- mortgage term;
- loan-to-value;
- the new property.
There may also be early repayment charges if the existing mortgage is repaid.
Ask the adviser to compare porting with taking a completely new mortgage rather than assuming one route will be cheaper.
When Your Current Mortgage Rate Is Ending
The end of a fixed or discounted period creates a useful review point.
Do not compare rates in isolation.
If your existing deal is approaching expiry, a mortgage rate ending adviser can help you consider your existing lender’s options alongside other available mortgages.
A remortgage may involve valuation, legal work, fees or early repayment charges.
Remaining with the same lender can sometimes be simpler.
The right decision depends on the numbers, not habit.
Buying a Property to Let in Colwyn Bay
A coastal location can attract landlords for different reasons, but investment decisions should begin with numbers rather than assumptions about demand.
A lender may consider the expected rental income, property type, loan-to-value and your wider landlord position.
Your route can also differ according to how you own and operate the property.
Relevant specialist searches include:
- first-time landlord mortgage advice when purchasing your first rental property;
- portfolio landlord mortgage advice where you already own several mortgaged rental properties;
- limited company buy-to-let advice when considering company ownership;
- HMO mortgage advice for properties intended for multiple occupation.
Tax treatment can differ between ownership structures, so obtain appropriate tax advice where required.
A mortgage adviser should not replace your accountant or tax adviser.
When Short-Term Property Finance Enters the Discussion
Some purchases do not fit neatly into a conventional residential or buy-to-let mortgage timetable.
A property may require substantial work before it becomes suitable for longer-term finance.
An investor may also need to complete quickly before selling or refinancing another asset.
In those circumstances, short-term buy-to-let bridging finance may be worth discussing.
Bridging finance is normally more expensive than standard mortgage borrowing.
The proposed exit strategy therefore matters from the beginning.
Buying first and deciding how to refinance later can create avoidable risk.
Independent Education Is Part of Colwyn Bay’s Financial Geography
Colwyn Bay has a genuine independent-school connection through Rydal Penrhos, a coeducational independent day school on Pwllycrochan Avenue. The Independent Schools Council lists the school for pupils from age 2 to 18.
For families choosing a home partly because of education, consider mortgage affordability and school costs together.
Independent education can create a long-term household commitment.
Families considering property-backed borrowing to meet planned education costs can read the Education Finance guide.
Possible routes can include a further advance, remortgage or second-charge arrangement, subject to affordability and lender criteria.
Borrowing against the home is not automatically the correct way to fund school fees.
The wider household position should come first.
Larger Homes and More Complex Income
Property value alone does not make a mortgage complicated.
The applicant often does.
Company directors, business owners, investors and clients receiving bonuses or several income streams may find that standard affordability calculations do not reflect their full financial position.
A Mortgage Broker in Colwyn Bay with suitable specialist experience can consider which lenders are prepared to assess the income structure involved.
Where circumstances justify it, high-net-worth mortgage advice may also be relevant for substantial assets, complex remuneration or larger borrowing requirements.
The aim should not be to make the case appear simple.
It should be to present the case accurately to a lender capable of understanding it.
Protecting the Mortgage and the Household Behind It
A mortgage helps finance the property.
Protection planning considers what could happen to the household if circumstances change.
Suitable mortgage protection advice may include discussions around life cover, critical illness cover or income protection where appropriate.
Needs differ between households.
A couple with children, a single borrower, a landlord and a self-employed business owner may each require a different discussion.
Insurance should therefore be based on actual needs, budget and existing arrangements rather than added automatically to the mortgage.
Later-Life Borrowing Requires a Different Conversation
As borrowers grow older, mortgage planning can shift from reaching the next property to how housing supports later life.
Someone may want to:
- remain in their existing home;
- repay an interest-only mortgage;
- provide a family gift;
- fund home improvements;
- move closer to relatives;
- reduce monthly commitments.
These objectives can involve very different solutions.
Standard mortgages, retirement interest-only mortgages and lifetime mortgages do not work in the same way.
If you’re considering equity release, specialist later-life advice matters because releasing equity can reduce your estate’s value and may affect entitlement to means-tested benefits.
Is the Nearest Adviser Automatically the Right Adviser?
Not necessarily.
Local knowledge can be useful.
Relevant expertise can be more important.
When choosing a Mortgage Broker in Colwyn Bay, consider whether the adviser regularly deals with circumstances like yours.
Ask about:
- mortgage experience;
- relevant specialist knowledge;
- lender access;
- fees;
- appointment options;
- communication;
- regulatory status.
Telephone and video appointments also mean you do not have to restrict your search to somebody whose office happens to be closest.
A directory helps you compare advisers before making contact.
The Property Tells Only Half the Story
A home can look straightforward from the pavement.
The mortgage application may tell another story.
Income structure, credit history, deposit source, property construction and future plans can all affect lender choice.
That is why choosing a Mortgage Broker in Colwyn Bay should start with fit, not proximity.
A good mortgage decision joins together three things: the borrower, the property and the lender.
When those three make sense together, the rate becomes part of the answer, not the entire question.




