
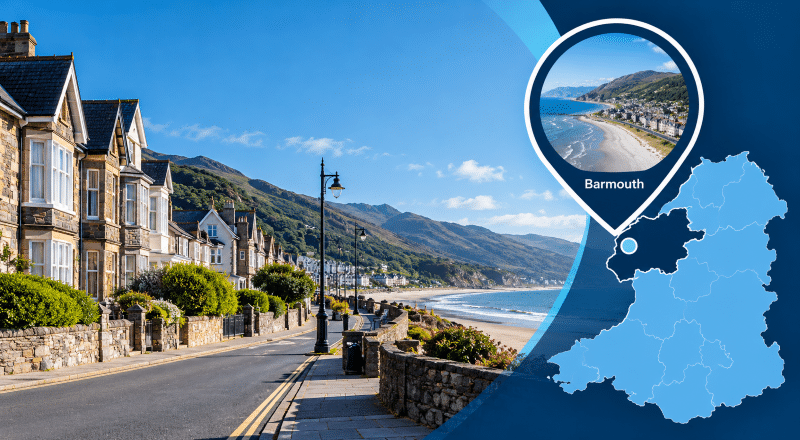
A Mortgage Broker in Barmouth can help turn the attraction of coastal living into a carefully considered financial decision. A beautiful location may influence where you want to live, but understanding what you can afford determines how comfortably you can stay.
Barmouth, known in Welsh as Abermaw, sits where the Mawddach Estuary meets Cardigan Bay. Its sandy coastline, historic streets, and surrounding hills create a distinctive setting for a property.
However, a house near the harbour may raise different mortgage questions than a hillside property overlooking the estuary.
Whether you are buying your first home, moving within Gwynedd, remortgaging or considering a property investment, the right adviser can help you understand lender criteria and potential costs.
At a Glance: Mortgage Broker in Barmouth
- Location: Barmouth (Abermaw), Gwynedd, North Wales.
- Postcode: LL42 covers Barmouth and its immediate locality.
- Property character: Older terraces, town-centre flats, coastal homes and properties on rising ground create varied mortgage considerations.
- Coastal position: Exposure to weather, property condition and flood risk may influence insurance and lending decisions.
- Transport: Barmouth railway station is on the Cambrian Coast Line, connecting the town with other coastal communities.
- Average house price: Gwynedd’s average was £204,000 in August 2026, according to the Office for National Statistics.
- First-time buyers: The average price paid across Gwynedd was £176,000 in August 2026.
- Holiday properties: Intended occupancy, letting arrangements and applicable planning rules should be checked before borrowing.
- Mortgage advice: Property experience and relevant lender knowledge can matter more than an adviser’s physical distance.
The house-price figures represent Gwynedd as a whole, not Barmouth alone. They are provisional and may be revised.
What Makes a Barmouth Property Different to Mortgage?
A property can appear perfectly suitable for everyday living but still require additional consideration from a lender.
Barmouth’s coastal position and changing terrain make individual property details especially important.
For example:
Homes close to the harbour or seafront
Lenders may consider construction, condition and any identified flood risk. The availability and cost of buildings insurance can also affect the practical affordability of a purchase.
Older town-centre properties
Some homes may contain original construction features, previous alterations or shared structural responsibilities. Flats and properties above commercial premises may require different lender assessments.
Hillside homes and rural properties
Access arrangements, retaining walls, drainage, outbuildings and private services may require further investigation, depending on the property.
Flats and converted buildings
Lease terms, maintenance responsibilities, building condition and management arrangements can affect mortgage eligibility.
A Mortgage Broker in Barmouth can help you identify these questions before you commit financially to a purchase.
If you are considering a coastal property, check the address through Natural Resources Wales’ Flood Risk Assessment Map.
The map provides area-based information about potential flooding from rivers, the sea and surface water. It does not replace a property survey or individual insurance assessment.
Buying in Barmouth: The Figures Behind the Decision
A property’s asking price is only the beginning of the financial calculation.
Buyers should consider the deposit, mortgage repayments, conveyancing costs, surveys, insurance and any necessary repairs.
There is also an important distinction between buying a home in Wales and purchasing one in England.
Land Transaction Tax (LTT) applies to qualifying property transactions in Wales instead of Stamp Duty Land Tax. Different rates may apply when purchasing an additional residential property.
You can check the current thresholds through the Welsh Government’s Land Transaction Tax guidance.
A Mortgage Broker in Barmouth can help you consider mortgage affordability alongside these wider financial commitments.
Before selecting a lender, use the UK Mortgage Rates Comparison Tool to explore available products, estimated monthly repayments and associated lender fees.
Remember that an advertised rate does not guarantee acceptance. The lender must still assess your circumstances and the property.
Barmouth Holiday Lets: When Property Use Changes the Mortgage
Barmouth’s visitor economy creates a practical distinction between buying a home and buying accommodation to let.
A residential mortgage is not automatically suitable for a property intended for short-term paying guests.
Lenders may examine:
- Whether the property will be a main residence, second home or commercial holiday let.
- Expected rental income and seasonal occupancy.
- Personal income, deposit requirements and ownership arrangements.
- Restrictions on personal use.
- Property management and specialist insurance requirements.
- Whether planning permission or other consents are required for the proposed use.
If you are considering short-term accommodation, explore Holiday Let Mortgage Advisers.
For other property investment plans, specialist searches include:
- First-Time Landlord Mortgage Advisers for buyers entering the rental market.
- Portfolio Landlord Mortgage Advisers for existing landlords managing several properties.
- Limited Company Buy-to-Let Advisers for property purchases through a company.
Check the Planning Position Before Assuming Holiday Use Is Permitted
Gwynedd has specific planning considerations relating to second homes and short-term holiday accommodation.
As of October 2026, Cyngor Gwynedd’s Article 4 Direction for its own planning authority area has been quashed and is no longer in force.
However, a separate Article 4 Direction remains in force within the Eryri National Park planning authority area.
The distinction matters because the planning position depends on the property’s exact location and existing lawful use.
Before buying, confirm the relevant planning authority, any existing planning conditions and whether your intended use is permitted.
A specialist mortgage adviser can assess the lending arrangements, while your conveyancer and the relevant planning authority can help establish legal and planning requirements.
Remortgaging: A Reason to Review, Not Simply Renew
As your mortgage nears the end of its initial rate period, it’s a good time to review your circumstances.
Your property may have changed in value. Your income, household commitments, or repayment priorities may also have changed.
Before accepting another mortgage product, consider:
- Whether your existing lender offers a suitable product transfer.
- Whether remortgaging to another lender could be appropriate.
- The effect of arrangement fees and early repayment charges.
- Whether changing the mortgage term would improve or increase your overall borrowing costs.
- Whether property improvements or a change of use affect lender requirements.
If your current mortgage deal is approaching expiry, find an adviser through Mortgage Rate Ending Advice.
A lower interest rate does not always mean a lower overall cost. Fees, repayment terms and the total amount payable should also be considered.
Mortgage Protection: Looking After More Than the Property
Buying a home creates a financial responsibility that may continue for many years.
Although property insurance protects the building, it does not necessarily protect your ability to meet the mortgage repayments if your circumstances change.
A Mortgage Broker in Barmouth can help you decide whether to speak with an appropriately authorised protection adviser.
Depending on your circumstances, protection advice may cover:
- Life insurance: Financial support for dependants if you die during the policy term.
- Critical illness cover: A potential lump-sum payment following diagnosis of an illness covered by the policy.
- Income protection: Regular payments if illness or injury prevents you from working, subject to the policy conditions.
Explore Protection Mortgage Brokers to find advisers with relevant protection expertise.
The appropriate level of cover depends on your financial responsibilities, existing policies, employment benefits and personal circumstances.
Later-Life Mortgage Advice for Barmouth Homeowners
Not every later-life property decision involves moving.
Some homeowners want to remain in familiar surroundings while considering home improvements, retirement finances or support for family members.
Equity release may be one option, but it may not suit everyone.
Lifetime mortgage providers assess the applicant’s age, property value, construction, condition and other eligibility criteria. Coastal location, property use and insurance considerations may also form part of the assessment.
For specialist guidance, visit Equity Release Advisers in Gwynedd through Connect Lifetime Mortgages.
An adviser should explain alternatives, potential interest accumulation, early repayment charges and the consequences for inheritance.
Equity release can reduce your estate’s value and affect your entitlement to means-tested benefits. Independent legal advice is also required before proceeding with an equity release plan.
Choosing the Adviser Who Understands Your Property Plans
The nearest adviser is not automatically the most appropriate.
For a typical residential purchase, you may want experience with affordability and the application process.
For an older coastal property, a holiday let or a more unusual building, specialist lender knowledge may be particularly valuable.
Before selecting an adviser, ask:
- Have you arranged mortgages for similar properties?
- Which lenders can you consider for my circumstances?
- What fees will I pay, and when?
- Can you explain any likely property-related lending concerns?
- Do you offer telephone, online or face-to-face appointments?
- Do you hold the appropriate permissions for the advice I require?
You can verify a firm’s regulatory status through the Financial Conduct Authority’s Financial Services Register.
If you would prefer to discuss your mortgage in Welsh or another language, explore Bilingual Mortgage Brokers and confirm the individual adviser’s language availability.
Start Your Barmouth Mortgage Search With Confidence
The right home should suit more than your immediate plans. It should also work with the financial commitments you can reasonably maintain.
Whether youare buying a home near the seafront, refinancing an existing mortgage, or considering a rental property, useful advice starts with understanding your needs.
Choose a Mortgage Broker in Barmouth through Connect Experts and compare advisers by experience, specialist knowledge and the support they offer.




