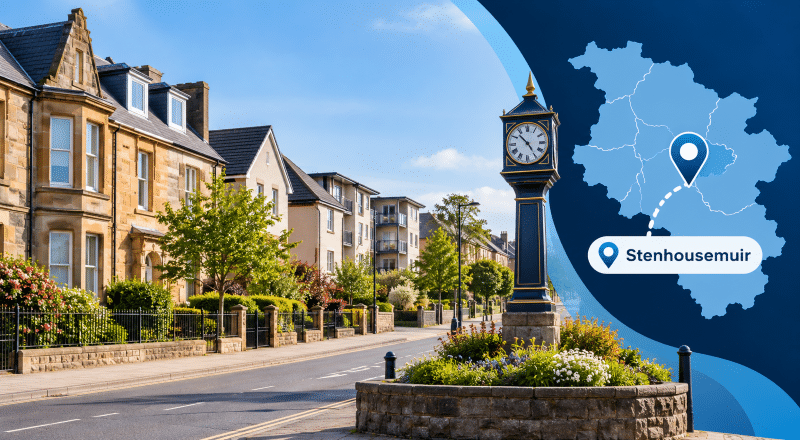
A Mortgage Broker in Stenhousemuir can help you look beyond what a mortgage costs today and consider how it might fit your life tomorrow.
Buying a home involves more than agreeing on a price. Your income, deposit, mortgage term and future commitments all influence what you can comfortably afford.
That distinction matters in Stenhousemuir, where traditional properties sit alongside established family homes and newer developments. Its position beside Larbert also makes it relevant to buyers working across Falkirk, Stirling and the wider Forth Valley.
Whether you are buying, moving, remortgaging or considering a rental property, finding an adviser with relevant experience can help you make a more informed decision.
At a glance: Mortgage Broker in Stenhousemuir
- Stenhousemuir is in the FK5 postcode district, within Falkirk Council and historic Stirlingshire.
- The local housing market includes traditional flats, terraced properties, family houses and newer developments.
- Falkirk’s average house price was £173,000 in July 2026, according to provisional ONS figures.
- First-time buyers across Falkirk paid an average of £144,000 during the same period.
- Nearby Larbert railway station provides connections towards Stirling, Glasgow and Edinburgh.
- Forth Valley Royal Hospital is in neighbouring Larbert, so different NHS employment and income arrangements may apply to some local applicants.
- Scottish Home Reports, lender valuations and Land and Buildings Transaction Tax all deserve attention before a purchase.
The house-price figures represent the Falkirk Council area, not Stenhousemuir alone. Individual property values will vary.
Why the Property Matters as Much as the Borrower
Stenhousemuir offers buyers several types of residential property, but not every home will receive the same mortgage assessment.
A traditional stone-built property near Main Street may raise different questions from a modern family home elsewhere in FK5.
Lenders can consider construction materials, condition, valuation, previous alterations and the property’s suitability as security.
In Scotland, buyers should also examine the Home Report.
The Scottish Government’s Home Report guidance explains that the report includes a single survey and valuation, an energy report and a property questionnaire.
A Mortgage Broker in Stenhousemuir can help you understand how a lender may assess the property and the borrowing required.
This becomes particularly important when the agreed purchase price exceeds the lender’s accepted valuation. The buyer may need additional funds to cover the difference.
The principle is straightforward: the amount someone agrees to pay for a home does not automatically determine how much a lender will advance.
First-Time Buyers: Understand the Scottish Purchase Process
Buying your first home is a significant commitment. However, the best starting point isn’t necessarily the maximum mortgage available.
It is understanding what your financial position can support.
For first-time buyers considering Stenhousemuir, an adviser can assess:
- Deposit size and its effect on available mortgage products.
- Income, employment arrangements and existing financial commitments.
- Monthly repayments at different mortgage terms.
- Lender affordability and credit requirements.
- Mortgage arrangement fees, legal costs and valuation considerations.
- Whether additional funds could be needed above the lender’s valuation.
Scottish buyers must also consider Land and Buildings Transaction Tax (LBTT), rather than Stamp Duty Land Tax.
Eligible first-time buyers may receive relief on purchases up to £175,000, subject to the qualifying conditions. Other purchases may attract LBTT depending on their value.
The Revenue Scotland LBTT calculator can help buyers estimate their potential liability.
Understanding these costs early can make the difference between a property that appears affordable and one that genuinely suits your budget.
Mortgage Advice for NHS Workers and Different Income Patterns
Living near a major employer can introduce mortgage considerations that deserve individual attention.
Forth Valley Royal Hospital is located in Larbert, close to Stenhousemuir.
Some NHS employees receive income through a combination of basic salary, overtime, additional shifts or bank work.
However, lenders do not always treat these earnings identically.
One lender may assess regular overtime differently from another. Bank income may require evidence of consistency, while variable earnings may be averaged over a specified period.
A Mortgage Broker in Stenhousemuir can help applicants understand which lenders may consider their particular income structure.
Similar considerations can apply to contractors, self-employed professionals, business owners and applicants with more than one source of income.
The relevant question is not simply how much you earn. It is how a lender calculates the income available to support your mortgage.
When Your Mortgage Rate Is Coming to an End
When a mortgage deal ends, it’s an opportunity to review more than just the next interest rate.
For homeowners in Stenhousemuir, the right decision may depend on changes since the original mortgage was arranged.
Your outstanding balance could be lower. Your property value may have changed, or your income and household expenditure might now look different.
A Mortgage Broker in Stenhousemuir can help you compare your options before your current arrangement expires.
These may include staying with your existing lender through a product transfer or remortgaging with another provider.
The assessment should consider:
- The remaining mortgage balance and property value.
- Any change in your loan-to-value position.
- Fixed, tracker and variable-rate options.
- Arrangement fees and the total borrowing cost.
- Early repayment charges, where applicable.
- Whether the existing mortgage term remains appropriate.
If your existing deal is approaching its end date, you can find a mortgage rate ending adviser through Connect Experts.
Reviewing your position early can give you more time to understand your options.
Buy-to-Let Mortgages and Small Business Property in FK5
Not every property purchase in Stenhousemuir involves a home the buyer intends to occupy.
Some buyers may be purchasing a flat to rent out, refinancing an investment property or considering premises for their business.
These arrangements require different lending assessments.
Buying Your First Rental Property
A buy-to-let lender will usually consider anticipated rental income, the deposit, property suitability and the applicant’s circumstances.
Landlord experience can also influence which lenders are willing to consider an application.
If you are entering the rental market, explore advisers specialising in first-time landlord mortgages.
Buying Through a Limited Company
A limited company buy-to-let mortgage can involve different ownership, lending and taxation considerations.
Lenders may assess the company structure, directors, rental income and existing financial commitments.
You can search for limited company buy-to-let mortgage advisers with relevant experience.
Tax advice should be obtained separately where appropriate.
Expanding an Existing Property Portfolio
Landlords who already own several rental properties may face more detailed financial assessments.
An adviser experienced in portfolio landlord mortgages can explain how lenders assess existing borrowing, rental income and future purchases.
Financing Business Premises
Stenhousemuir’s local shops and trading premises create another possible borrowing requirement.
A business owner considering purchasing premises for their own company may need an owner-occupied commercial mortgage adviser.
Commercial lenders may assess trading performance, accounts, affordability, and the intended use of the property.
For additional residential property purchases, buyers should also consider Scotland’s Additional Dwelling Supplement rules.
The right finance depends on the property’s purpose, ownership structure, and individual circumstances.
Mortgage Protection: Planning for What You Cannot Predict
A mortgage is a financial commitment built around expectations about future income.
However, circumstances can change.
An illness, injury or unexpected loss of earnings may affect a household’s ability to meet its mortgage payments.
For that reason, protection deserves as much attention as mortgage affordability.
Depending on your circumstances, relevant policies may include:
- Life insurance: Financial support for beneficiaries after the insured person’s death, which may help repay an outstanding mortgage.
- Critical illness cover: A lump sum following diagnosis of a condition covered by the policy, subject to its terms.
- Income protection: A regular benefit replacing part of your income if illness or injury prevents you from working, subject to policy conditions.
- Mortgage payment protection: Cover designed to help with repayments following specified events, depending on the policy.
Not every policy will be suitable for every borrower. Existing employer benefits, savings, household commitments and affordability should all form part of the discussion.
Connect Experts can help you find protection mortgage brokers who can explain the available options and assess your needs.
Protection is not simply about insuring a mortgage. It is about considering how your financial responsibilities could be managed when life takes an unexpected direction.
Equity Release and Later-Life Mortgage Choices in Stirlingshire
A mortgage decision can mean something different later in life.
Some Stenhousemuir homeowners may have substantial equity in their property but a reduced retirement income. Others may be considering home improvements, repaying an existing mortgage, or helping family financially.
Equity release may be one option for eligible homeowners, but it should never be treated as an automatic solution.
A qualified adviser should consider the applicant’s age, property value, existing debts, future income and longer-term plans.
With a lifetime mortgage, interest may be added to the loan, increasing the amount owed over time.
Equity release can also reduce an estate’s value and affect entitlement to means-tested benefits.
Connect Lifetime provides information on equity release and later-life mortgage advice, including key considerations and alternatives.
A suitable decision should reflect not only what a homeowner needs today, but also the financial choices they may wish to preserve for the future.
Choosing a Mortgage Adviser Who Understands Your Needs
The nearest adviser will not always be the most suitable person for your circumstances.
A straightforward first-time purchase, a complex income application and a limited company buy-to-let mortgage all require different experience.
When comparing advisers, consider whether they have:
- Relevant experience with your mortgage requirement.
- The appropriate regulatory permissions.
- Access to lenders suitable for your circumstances.
- Clear explanations of fees and possible charges.
- Appointment options that fit your preferences.
- Experience with Scottish property purchases where relevant.
Connect Experts allows you to search adviser profiles by location, language, gender and mortgage expertise.
This means you can consider advisers covering Stenhousemuir, Larbert, Falkirk and the wider Stirlingshire area before choosing whom to contact.
Find the Right Mortgage Adviser in Stenhousemuir
A good mortgage decision begins with understanding your circumstances, not selecting a product from a list.
Whether youare buying your first property, reviewing an existing mortgage, or planning an investment, choosing the right adviser is an important first step.
Use Connect Experts to find a Mortgage Broker in Stenhousemuir and compare advisers with experience relevant to your circumstances.
The aim is to make a decision that works not only when your mortgage begins, but throughout the years that follow.