
A Mortgage Broker in Stratford-upon-Avon can help turn a property decision into a financial decision based on evidence rather than assumption. A home may be defined by its location, history, or character, but a mortgage is ultimately judged by affordability, income, credit history, deposit, property suitability, and lender criteria.
Stratford-upon-Avon creates an interesting mix. Historic streets sit alongside established residential neighbourhoods and newer developments, while the wider district includes some of the higher property values found in the West Midlands.
Connect Experts helps you search for mortgage advisers by location, mortgage type, language, and other preferences, so you can compare profiles before deciding who to contact.
At a glance: Mortgage Broker in Stratford-upon-Avon
- Stratford-upon-Avon combines historic properties, established residential areas and newer housing.
- The town has a designated conservation area, making property age and previous alterations relevant considerations for some purchases.
- The average Stratford-upon-Avon house price was £397,000 in July 2026.
- First-time buyers in the district paid £307,000 on average in July 2026.
- Homes bought with a mortgage averaged £402,000.
- Stratford-upon-Avon has genuine independent-school connections, including The Croft Preparatory School and Stratford Preparatory School.
- Higher property values can make income structure, deposit size and lender criteria particularly important.
- The most suitable adviser does not necessarily have to be the closest one geographically.
Understanding the Stratford-upon-Avon Mortgage Market
Choosing a Mortgage Broker in Stratford-upon-Avon may be particularly useful when the property or the applicant does not fit a simple lending profile.
According to the Office for National Statistics, the average house price in Stratford-upon-Avon was £397,000 in July 2026, up from £390,000 a year earlier. First-time buyers paid an average of £307,000, while home movers paid £473,000.
Property type also creates substantial differences. The ONS recorded July 2026 averages of £611,000 for detached homes, £370,000 for semi-detached properties, £294,000 for terraced homes and £190,000 for flats and maisonettes.
These figures describe the district rather than the price of an individual Stratford-upon-Avon property, but they give useful context when considering deposits, loan sizes and affordability.
Historic Homes and Mortgage Considerations
Stratford-upon-Avon is a town where a building’s story can sometimes matter to the mortgage as much as its postcode.
The Stratford-on-Avon District Council identifies 75 conservation areas across the district, including Stratford-upon-Avon itself. Conservation status does not prevent a property from being mortgaged, but a building’s characteristics may affect valuation or lender assessment.
A lender or valuer may need to consider construction type, condition, alterations, extensions, listed status and whether supporting permissions are available.
That distinction matters. An attractive historic feature from a buyer’s perspective may still require closer technical consideration from a lender.
What Could Affect a Mortgage Application?
Mortgage affordability is rarely determined by salary alone. Lenders may consider employment type, regular commitments, credit history, deposit or equity, the requested loan size and the property being offered as security.
A first-time buyer purchasing a flat may therefore face very different questions from a company director purchasing a detached home or an existing owner moving to a more expensive property.
For buyers entering the market, the First-Time Buyer Mortgage Adviser search can help identify advisers whose stated experience includes first-time buyer cases.
Self-employed applicants may also want to use the Self-Employed Mortgage Adviser search, as lender treatment of salary, dividends, retained profit, accounts and trading history can vary.
Finding the Right Mortgage Adviser
Finding a Mortgage Broker in Stratford-upon-Avon should not simply mean choosing whichever adviser appears geographically closest.
The more useful question is whether the adviser regularly deals with the type of mortgage you need.
Someone moving home may require help comparing affordability and existing equity. A business owner may need an adviser familiar with more complicated income evidence. Someone whose fixed rate is ending may want to compare a product transfer with remortgaging elsewhere.
If your existing deal is approaching its end date, you can search for Mortgage Rate Ending Advisers and compare advisers before making contact.
The Connect Experts directory also lets you consider location, language and adviser preference alongside relevant mortgage experience.
Higher-Value Mortgages in Stratford-upon-Avon
Stratford-on-Avon’s housing figures make higher-value borrowing relevant to the area rather than an artificial addition to the page. In July 2026, detached properties across the district averaged £611,000, considerably above the wider district average.
A larger mortgage does not automatically make a case complex. Complexity may instead come from how the borrower earns or holds wealth.
Applicants might receive salary, bonuses, dividends, partnership income, investment income or retained company profits. Others may have substantial assets but comparatively modest regular taxable income.
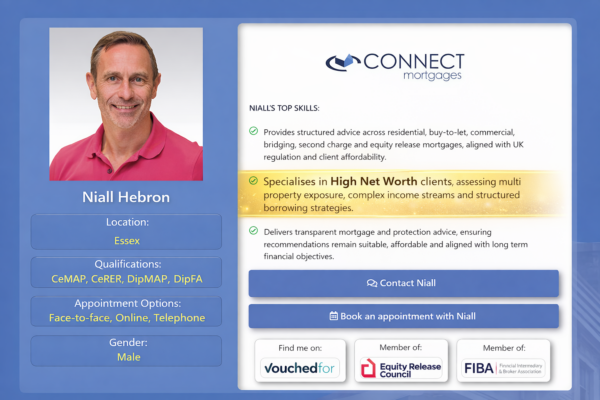
Lender approaches to these circumstances can differ. Someone buying or refinancing a higher-value home may therefore want to work with a High-Net-Worth Mortgage Broker experienced with larger loans and more complex income structures.
The aim is not simply to borrow more. It is to understand how a lender is likely to assess the complete financial position.
Independent Schools and Education Finance
Where people choose to live is sometimes connected to the future they are planning rather than only the house they want today.
Stratford-upon-Avon has genuine independent-school connections. The Croft Preparatory School is located on Loxley Road, while Stratford Preparatory School is based in Old Town.
For some households, school fees therefore become part of the wider financial picture. They may affect mortgage affordability as an ongoing commitment, even when those costs are being comfortably met.
Families considering how education costs interact with property wealth, savings or borrowing can read more about Education Finance.
Options can depend on individual circumstances and may include remortgaging, a further advance, second-charge borrowing or other secured finance. Borrowing against a property increases the amount secured on it and should be considered alongside the cost and repayment implications.
Moving Home Around Stratford-upon-Avon
For home movers, choosing a Mortgage Broker in Stratford-upon-Avon may involve more than securing a mortgage on the next property.
Your existing mortgage could have early repayment charges. It may be portable, although porting does not guarantee that additional borrowing will be approved. Changes in income or financial commitments since you took out the original mortgage can also affect affordability.
Where the new home has a higher purchase price, the deposit size, equity released from the existing property, and additional borrowing required can become closely connected.
This is why reviewing the mortgage before making assumptions about the next purchase can be useful.
Protection and Longer-Term Planning
A mortgage decision creates a long-term financial commitment. It can therefore be sensible to consider what would happen if household income changed because of death, serious illness or an extended period away from work.
Protection needs vary considerably. Existing workplace benefits, savings, dependants, mortgage size and household income can all affect the level and type of cover someone may consider.
Mortgage advice and protection advice should reflect the individual’s circumstances rather than treating insurance as a standard addition to every mortgage.
For higher-value households, larger debts, or more complicated financial arrangements, High-Net-Worth Protection may also be worth exploring with an appropriately qualified adviser.
Local Knowledge or Relevant Mortgage Experience?
A Mortgage Broker in Stratford-upon-Avon may understand the local housing market, but physical distance should not be the only test.
Modern mortgage advice can be provided face-to-face, by telephone or online. This means someone with a complicated income structure, specialist property or particular borrowing requirement can widen their search beyond the nearest adviser.
Local knowledge can still be useful, particularly where older buildings or unusual property characteristics are involved. Yet experience with the mortgage itself may sometimes be more valuable than proximity.
The better question is simple: does the adviser understand both your financial circumstances and the type of mortgage you are trying to arrange?
Find a Mortgage Adviser
Choosing a Mortgage Broker in Stratford-upon-Avon is ultimately about finding someone whose experience fits the decision in front of you.
Connect Experts lets you compare adviser profiles rather than automatically assigning you someone. You can search by mortgage type, location, language, and other preferences before deciding who to approach.
Find a Mortgage Adviser and choose an adviser whose stated experience matches your circumstances.
Connect Experts is a mortgage adviser directory and matching platform. It does not provide mortgage advice directly. Advice is provided by the adviser or firm you choose.




