A Mortgage Broker in Stirling can help you see that a mortgage isn’t just about what you can borrow today. It is also about the financial commitments you can comfortably maintain tomorrow.
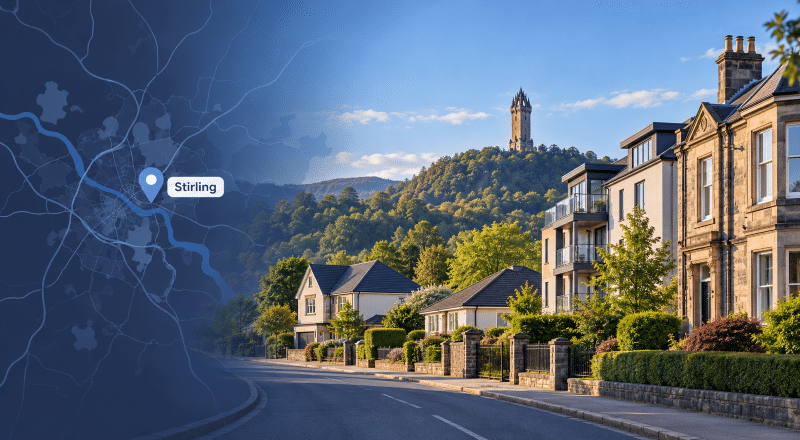
Stirling is a city where centuries of history sit alongside modern residential neighbourhoods. Homes around the Old Town and King’s Park can raise different lending questions from properties in St Ninians, Bannockburn or Cambusbarron.
However, finding a suitable mortgage involves more than understanding the address. Your income, deposit, credit commitments and future plans all influence which lenders may consider your application.
Connect Experts helps you find mortgage advisers in Stirling and the surrounding areas of Stirlingshire. You can compare advisers by location, experience, language and other preferences before deciding who to contact.
At a glance: Mortgage Broker in Stirling
- Location: Stirling includes the FK7 and FK8 postcode districts, with nearby Bridge of Allan in FK9.
- Local housing: The Old Town, King’s Park, Riverside, St Ninians and Cambusbarron offer different property styles and lending considerations.
- Historic properties: Parts of Stirling, including King’s Park and the Old Town, are protected as conservation areas.
- Average house price: £239,000 across the Stirling local authority area in July 2026, according to provisional ONS figures.
- First-time buyers: Paid an average of £184,000 across the same local authority area in July 2026.
- Scottish buying process: A Home Report provides information about a property’s condition, valuation and energy performance.
- Rental property: Stirling Council requires HMO licensing where the relevant occupancy conditions are met.
The Office for National Statistics housing report for Stirling provides further market information. These figures cover the council area rather than Stirling city alone.
Historic Homes, Modern Mortgages and the Details That Matter
Stirling Castle overlooks a city where a property’s age and construction can be as important as its purchase price.
Around King’s Park, established stone-built houses and Victorian properties form an important part of Stirling’s architectural heritage. The Old Town contains buildings with different layouts, histories and maintenance responsibilities.
Meanwhile, buyers in St Ninians, Bannockburn, and other residential neighbourhoods may find more conventional or recently built homes.
A Mortgage Broker in Stirling should help you understand how lenders assess the property you want to finance.
Depending on the property, important considerations may include construction materials, roof condition, alterations, shared maintenance responsibilities and valuation requirements.
Stirling Council’s conservation area information helps identify locations where historic character and planning controls deserve closer attention.
For homes near the River Forth or other potentially vulnerable locations, buyers should also consider insurance availability and flood risk. The Scottish Environment Protection Agency’s flood maps can support an initial area-level assessment.
A property’s appearance may attract you to it. Its condition and a lender’s acceptance will help determine whether the purchase is financially realistic.
Your First Stirling Home: Look Beyond the Asking Price
Buying your first home in Stirling involves several decisions before you receive the keys.
Scotland’s property-buying system places particular importance on the Home Report. It typically includes a survey and valuation, an energy report, and a property questionnaire.
However, the Home Report valuation does not guarantee that a mortgage lender will accept the same figure.
If you offer more than your lender’s valuation, you may need additional funds to cover the difference. Your deposit, mortgage affordability and available savings therefore deserve careful consideration.
Working with a Mortgage Broker in Stirling before making an offer can help you understand your borrowing position and possible lender requirements.
A suitable adviser can explain the difference between an Agreement in Principle and a formal mortgage offer. They can also help you assess how the deposit, interest rate, mortgage term and product fees affect your repayments.
If this is your first purchase, use Connect Experts to find a first-time buyer mortgage adviser.
Remember to budget for legal costs, moving expenses and any applicable Scottish Land and Buildings Transaction Tax.
When Your Income Needs More Than a Standard Assessment
Stirling’s location attracts people working locally and across central Scotland. However, the place you work is not always the most important factor in a mortgage application.
The way you receive your income can make a significant difference.
Someone employed on a fixed salary may have a relatively straightforward application. A university employee with multiple income sources, a contractor, or a business owner may need a more detailed assessment.
Lenders can differ in how they treat overtime, variable earnings, bonuses, self-employed profits, and dividend income.
For company directors, lenders may also examine salary, dividends, accounts and retained profits, depending on their criteria.
If your income doesn’t follow a standard monthly pattern, compare self-employed mortgage brokers with relevant experience.
The aim is to find lending criteria that fit your circumstances rather than assuming every lender will assess your income in the same way.
Stirling Buy-to-Let Mortgages: Understand the Rental Arrangement
Stirling’s university connection makes rental property a relevant consideration for some investors. However, financing a property for one household differs from arranging a mortgage for shared accommodation.
A Mortgage Broker in Stirling with landlord experience can help you examine the proposed rental arrangement, property suitability and lender requirements.
For someone buying their first rental property, a first-time landlord mortgage adviser can explain deposits, rental affordability, and the responsibilities that come with buy-to-let borrowing.
Shared accommodation can introduce additional requirements.
Stirling Council states that an HMO licence is required for a property used as the principal residence of three or more unrelated people. An HMO application may also involve planning considerations, safety requirements and lender restrictions.
Before financing shared accommodation, review the Stirling Council HMO licensing requirements and consider whether you need a specialist HMO mortgage adviser.
Existing landlords may need different support. For example, advisers experienced in portfolio landlord mortgages can assess cases involving several rental properties.
Those considering corporate ownership can also find advisers dealing with limited company buy-to-let mortgages. Separate tax advice is important before deciding on an ownership structure.
Is Your Stirling Mortgage Rate Coming to an End?
When a fixed or tracker mortgage deal approaches its expiry date, reviewing your options can help you prepare for changing repayments.
For homeowners in Stirling, the choice may be to stay with your current lender or explore another lender’s products.
The lowest advertised interest rate isn’t always the cheapest option.
Product fees, early repayment charges, mortgage balance and the remaining term can affect the overall cost.
A mortgage adviser can help assess whether a product transfer or remortgage is appropriate for your circumstances.
If your existing deal is approaching its end date, find a mortgage rate-ending adviser to discuss your options.
Reviewing your position early gives you more time to consider the implications before committing.
Larger Mortgages and Education Costs Around Stirling
Some households in Stirling and nearby Bridge of Allan may have more complex financial requirements.
Higher-value borrowing can involve substantial deposits, multiple income streams, investment income, or assets that don’t produce a regular salary.
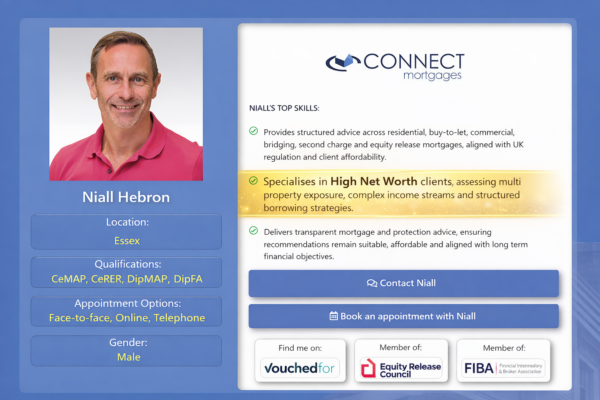
In these circumstances, high-net-worth mortgage brokers may offer relevant specialist experience.
Education costs can also influence household affordability.
Nearby Bridge of Allan is home to Fairview International School, an independent International Baccalaureate school.
For families considering independent education, mortgage affordability should be assessed alongside school fees and other future commitments.
Connect Mortgages provides further information about education finance and funding independent school fees.
Borrowing against a home to fund education requires careful consideration of the cost, repayment obligations and risks.
Protection Advice: Keeping Your Home Financially Secure
A mortgage creates a financial responsibility that may last for many years.
However, circumstances can change. Illness, injury, or the loss of income could make mortgage repayments harder to maintain.
Protection advice can help you consider how those risks might affect your household.
Depending on your needs, relevant policies may include life insurance, critical illness cover and income protection.
Each serves a different purpose.
Life insurance can provide financial support following death, subject to policy terms. Critical illness cover may pay a lump sum following diagnosis of a condition covered by the policy. Income protection can provide income if you cannot work because of illness or injury, subject to the policy conditions.
The appropriate cover depends on your mortgage, existing benefits, savings, household income and dependants.
To explore your options, find protection mortgage brokers who can explain suitable protection arrangements.
A mortgage helps finance the home you want. Suitable protection can help you prepare for circumstances that might otherwise place that home at risk.
Later-Life Mortgage Advice for Stirling Homeowners
For homeowners approaching retirement, mortgage decisions can involve different priorities.
Some may wish to reduce an outstanding mortgage balance. Others may be considering home improvements, financial assistance for family members or additional retirement income.
Equity release is one option, but it isn’t suitable for everyone.
Lifetime mortgages are generally available to eligible homeowners aged 55 or over. Interest may be added to the loan balance, increasing the amount owed over time.
Equity release can also reduce your estate’s value and affect entitlement to means-tested benefits.
A specialist adviser should consider the purpose of borrowing, repayment options, property suitability, alternatives and long-term financial consequences.
For regional guidance, visit Equity Release Advisers in Stirlingshire through Connect Lifetime Mortgages.
Later-life borrowing should start with an assessment of what you need your home to provide now and in the years ahead.
Choosing a Stirling Mortgage Adviser Who Fits Your Circumstances
Finding an adviser should involve more than choosing someone with a nearby office.
Relevant mortgage experience, professional permissions, and communication skills can all affect whether an adviser is suitable.
Connect Experts lets you search adviser profiles by location, mortgage expertise, language and other available preferences.
Before arranging an appointment, consider the adviser’s experience with your type of mortgage, how appointments are conducted, any advice fees and which lenders they can access.
You should also check the relevant firm’s authorisation and the activities it is permitted to undertake.
Some clients may prefer face-to-face appointments in Stirling. Others may find telephone or video appointments more convenient.
The right choice depends on your circumstances.
Find Mortgage Advice in Stirling That Looks Beyond Today
Stirling’s historic streets, established neighbourhoods, and growing residential communities offer different ways to make a home.
Yet the most important mortgage decision is rarely determined by the address alone.
It comes down to understanding the borrowing, recognising the risks and choosing financial commitments that fit your plans.
Use Connect Experts to search for mortgage advisers and compare profiles before selecting a Mortgage Broker in Stirling with the experience you need.