
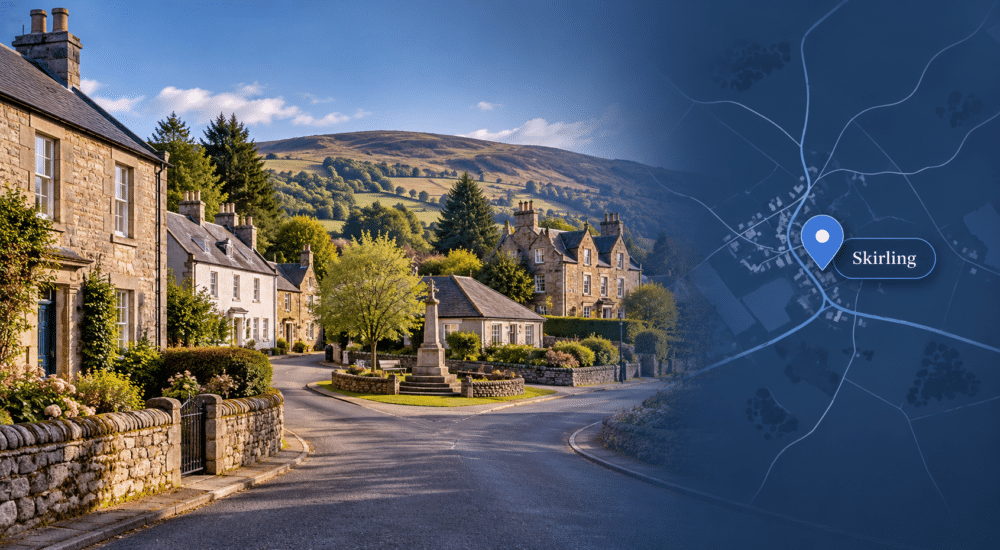
Choosing a Mortgage Broker in Skirling is about more than finding a loan. It means judging whether today’s decision will still serve you tomorrow.
Skirling has a distinctive character, shaped by traditional buildings, rural surroundings and its position east of Biggar. Although historically part of Peeblesshire, the village falls within the Scottish Borders Council area.
Buying here can involve questions beyond affordability. Property condition, construction, lender valuation and future responsibilities can all affect your plans.
Connect Experts helps you find mortgage advisers with experience suited to your circumstances, whether you are buying, remortgaging or considering specialist borrowing.
At a glance: Mortgage Broker in Skirling
- Location: Skirling lies around 2.5 miles east of Biggar, within historic Peeblesshire.
- Postcode: ML12. Despite its Biggar postal address, Skirling falls within the Scottish Borders Council area.
- Local character: Skirling is a designated conservation area with traditional sandstone, harled finishes, slate roofs and historic architectural features.
- Property considerations: Listed buildings, traditional construction and proposed alterations may require additional checks.
- Buying in Scotland: A Home Report normally includes a survey and valuation, a property questionnaire, and an energy report.
- Local education: Community information identifies Broughton Primary School and Peebles High School as the local catchment schools. Buyers should confirm current arrangements with the council.
- Mortgage suitability: The property’s condition, intended use and your finances can matter more than finding an adviser based in the village itself.
When Skirling’s History Becomes a Mortgage Consideration
A village’s history can add character to a home. However, preserving that character may come with responsibilities a buyer should understand.
Skirling’s conservation area includes traditional buildings with features such as sandstone walls, slate roofs and sash-and-case windows.
These features do not automatically prevent mortgage approval. However, lenders may consider the property’s construction, condition, valuation and future saleability.
A Mortgage Broker in Skirling can help identify lender requirements before you commit to a property.
For example, a lender may want further information about significant repairs, unusual construction or planned renovation work.
Properties outside the village centre may also include agricultural land, outbuildings or private access arrangements. Where these features exist, disclose them early in the mortgage process.
A mortgage adviser can assess lender criteria, while a qualified surveyor and solicitor investigate the property’s condition and legal details.
You can review the official Skirling Conservation Area information published by Scottish Borders Council.
Buying in Scotland: Why the Home Report Matters
One key difference between buying in Scotland and elsewhere in the UK is the Home Report.
For most properties offered for sale, the seller provides this report. It contains information about the home’s condition, valuation and energy performance.
However, the reported value and the price you agree to pay may differ.
Imagine finding a traditional home near Skirling. You are comfortable with the asking price, but competition encourages you to offer more than the valuation.
Your lender may calculate your available mortgage based on its accepted valuation rather than your higher offer. As a result, you may need additional savings.
This makes your deposit planning especially important.
Before submitting an offer, consider the property’s valuation, available deposit, legal costs and any repairs highlighted in the report.
You can read the Scottish Government’s Home Report guidance to understand the information provided.
Your solicitor should also explain the Scottish offer process and conclusion of missives. Once missives are concluded, the agreement is normally legally binding.
Good preparation allows you to approach that commitment with greater confidence.
Mortgage Advice That Reflects Your Plans in Skirling
No two mortgage enquiries are identical, even when the properties sit within the same village.
Speaking with a Mortgage Broker in Skirling can clarify which lenders may consider your circumstances and what information they will require.
Buying your first home
A first-time buyer may need guidance on affordability, deposit evidence, credit history and the Scottish purchasing process.
This is especially useful when the property needs additional valuation or repair considerations.
You can find first-time buyer mortgage brokers who can explain the mortgage process and help you prepare for an application.
Reviewing an existing mortgage
If you already own a home in Skirling, an approaching product expiry is a good time to review your borrowing.
Staying with your current lender may be suitable, but remortgaging elsewhere could offer different terms.
Before deciding, compare interest rates, arrangement fees, early repayment charges and future repayment costs.
Find advisers experienced in mortgage rate-ending enquiries to discuss your available options.
Purchasing a property to let
If you intend to rent out a house or cottage, lenders will assess the application differently from a residential mortgage.
They may consider rental income, property condition, deposit size, landlord experience and ownership arrangements.
Those entering the rental market can find a first-time landlord mortgage adviser.
For property purchases or refinancing through a company, the limited company buy-to-let adviser search provides a more specialised starting point.
Converting or redeveloping a building
A larger conversion project can raise different funding questions.
For example, converting an agricultural building into residential accommodation may require planning permission, significant building work and staged finance.
If conventional mortgage lending isn’t suitable for a genuine development project, development finance advisers can explain potential funding structures and repayment strategies.
Compare Mortgage Rates Before Choosing Your Deal
The lowest advertised interest rate is not necessarily the least expensive mortgage.
Arrangement fees, introductory periods, repayment terms, and early repayment charges can affect what you pay.
The UK Mortgage Rates comparison tool from Connect Mortgages lets you explore mortgage products, estimated repayments, and associated fees.
However, comparison results do not confirm that you qualify for a particular mortgage.
Lenders must still assess your income, credit commitments, deposit and the property itself.
A Mortgage Broker in Skirling can help you consider the overall borrowing cost rather than focusing only on the headline interest rate.
This distinction matters when a property’s age or construction affects which lenders will consider it.
Protecting Your Mortgage, Income and Family
Buying a home creates responsibilities that continue long after completion.
Your mortgage payments may depend on employment income, business earnings or contributions from more than one household member.
Consider what would happen if illness, injury or death affected those finances.
Suitable protection policies may help provide financial support, subject to their terms and conditions.
Depending on your circumstances, an adviser may discuss life insurance, critical illness cover or income protection.
These products serve different purposes. Each has its own eligibility requirements, exclusions, benefits and costs.
Connect Experts can help you find mortgage protection advisers who can review your needs alongside your existing cover and mortgage commitments.
The objective is not simply to obtain cover. It is to understand which financial risks you want to address and what protection may be suitable.
Equity Release and Later-Life Mortgage Options in Peeblesshire
For homeowners approaching or already in retirement, the financial questions may change.
You might wish to reduce an existing mortgage, improve your home or access some of its value.
Equity release is one possible route for eligible homeowners, generally aged 55 or over. However, it should be considered alongside other forms of later-life borrowing and possible alternatives.
A lifetime mortgage allows eligible homeowners to borrow against their property while retaining ownership.
The amount available depends on factors including age, property value, borrowing needs and lender criteria.
Interest may compound if it is not paid, increasing the outstanding balance over time.
Equity release can reduce your estate’s value and affect entitlement to means-tested benefits.
Homeowners in Skirling can get advice on equity release and later-life mortgages through Connect Lifetime Mortgages.
Specialist regulated advice and independent legal advice are important before proceeding.
Choosing an Adviser Who Understands Your Circumstances
Skirling’s ML12 postcode is associated with Biggar, but the village belongs to the Scottish Borders.
That distinction can matter when researching local planning rules, conservation information and property records.
It is also worth looking beyond an adviser’s physical location.
An adviser with experience in Scottish purchases, traditional construction or specialist mortgage applications may be more relevant than someone who happens to work nearby.
When reviewing an adviser, consider their mortgage specialisms, communication preferences, relevant experience and fees.
Also establish whether they can advise on your intended type of borrowing.
Connect Experts allows you to compare advisers by location, language, gender and other available search criteria.
Start Your Mortgage Search With Greater Confidence
A home should support your plans, not leave you uncertain about the commitment you have made.
Whether you are buying a traditional village property, reviewing your current mortgage or planning a future investment, informed advice can help you understand your options.
Start your search for a Mortgage Broker in Skirling through the Connect Experts mortgage adviser directory.
Compare adviser profiles, explore relevant experience and choose someone whose services match your circumstances.




