
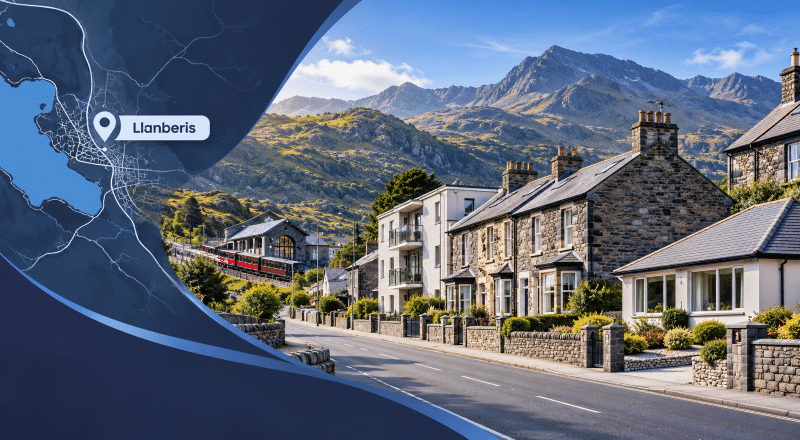
Choosing a Mortgage Broker in Llanberis should begin with the life you want your mortgage to support, not simply the largest loan a lender might offer. The right decision has to work after the excitement of moving has passed, when monthly bills, repairs and future plans become part of everyday life.
Llanberis has its own character. Set beside Llyn Padarn and beneath Yr Wyddfa, it combines a working Welsh community with slate-industry heritage and a busy visitor economy. These features also shape the questions borrowers need to ask about homes, income, and property use.
At a glance: Mortgage Broker in Llanberis
- Location: Llanberis sits in Gwynedd’s LL55 postcode district, beside Llyn Padarn and close to the Llanberis Path up Yr Wyddfa.
- Housing: Older terraces associated with the area’s slate history sit alongside later homes and properties in nearby rural settlements.
- Planning boundaries: The upper village and Nant Peris fall within Eryri National Park’s planning area; the lakeside and lower village are outside it.
- Average price: Gwynedd’s average house price was £204,000 in August 2026, according to provisional ONS figures.
- First-time buyers: The average price first-time buyers paid across Gwynedd was £176,000 in August 2026.
- Property checks: Construction, condition, access, outbuildings and intended use may affect lender criteria.
- Holiday letting: Finance and planning checks differ from those for a home you intend to live in.
- Borrower protection: Life cover, critical illness cover and income protection deserve consideration alongside mortgage repayments.
These figures describe Gwynedd as a whole, not the average sale price for Llanberis specifically. Check the latest ONS housing figures for Gwynedd when planning your budget.
From Slate-Era Terraces to Mountain-Edge Homes
The former Dinorwig slate workings help explain the buildings and heritage around Llanberis. The quarry landscape forms part of the UNESCO-listed Slate Landscape of Northwest Wales, but that does not mean every village home has the same planning designation or lending restrictions.
When buying an older terrace, a converted building, or a house on the edge of the village, the lender may want clarity on its construction, roof, condition, and valuation. Further out towards Nant Peris, private access, extra land, outbuildings or unusual services could require additional information.
An experienced Mortgage Broker in Llanberis can help you understand which details a lender may ask for before a full application. This is especially useful when an appealing property has features that don’t fit standard lending criteria. A survey and the lender’s own valuation remain important.
First Homes, Moving Plans and Mortgage Renewals
Buying your first home. Before making an offer, work out your deposit, affordable monthly payments and purchase costs. In Wales, Land Transaction Tax may apply rather than Stamp Duty Land Tax. Explore first-time buyer mortgage advisers for help understanding lender affordability checks, credit history and deposit evidence.
Working in the visitor economy. Hospitality, guiding, retail and other self-employed work may involve seasonal or variable income. Lenders differ in how they assess accounts, calculate tax, and view income patterns. A self-employed mortgage adviser can help identify the records to prepare.
Reviewing an existing mortgage. When a fixed or introductory deal is approaching its end, consider a product transfer with your current lender alongside remortgage options. Our mortgage rate ending adviser search can help you find relevant expertise. You can also compare UK mortgage rates and fees to start. The lowest advertised rate is not always the lowest overall cost once fees and charges are included.
Holiday Lets in Llanberis: The Intended Use Comes First
A house occupied by its owner, a property rented to long-term tenants and a cottage let to visitors are not interchangeable in a lender’s eyes. Llanberis attracts walkers and visitors, but projected bookings alone don’t guarantee a holiday-let mortgage will be available or affordable.
A Mortgage Broker in Llanberis with holiday-let experience can help you discuss deposit requirements, personal use, seasonal income, management costs and lender restrictions. Search for holiday let mortgage advisers if short guest stays are central to your plan. For a conventional long-term rental, consider a first-time landlord adviser or a limited company buy-to-let adviser if you plan to own through a company.
Check which planning authority covers the address. Eryri National Park’s Article 4 Direction has applied since 1 June 2025 and restricts certain changes to second-home and short-term-let use without planning permission. By contrast, Cyngor Gwynedd’s Article 4 Direction for areas outside the National Park was quashed in November 2025 and is not in force. Review the current guidance from Eryri National Park or Cyngor Gwynedd as appropriate. Other planning conditions, legal restrictions and mortgage terms may still matter.
When a Llanberis Property Supports a Business
A shop, guesthouse or other business premises may require different lending from an ordinary residential mortgage. For example, premises bought for your own trading business may call for an owner-occupied commercial mortgage adviser. Be clear about which parts of the building are residential, commercial or let to others, because the intended use can affect lender choice.
Mortgage Protection Should Be Part of the Conversation
A mortgage is a long-term promise, but income and family circumstances can change unexpectedly. Life insurance, critical illness cover, and income protection serve different purposes and won’t suit every household. Cover, exclusions, costs and eligibility vary between providers.
You can find advisers experienced in mortgage protection advice to review how your household might manage payments if illness, injury or death affected its finances. Check that the adviser you select has the appropriate protection permissions.
Later-Life Mortgage and Equity Release Advice in Gwynedd
Older homeowners in Llanberis may be weighing the cost of repairs, an existing mortgage balance or the wish to stay near family. Equity release is one possible route for eligible borrowers, but it should be compared with alternatives such as downsizing or other later-life mortgage options.
The equity release advisers in Gwynedd guide from Connect Lifetime explains how property type, valuations, rolled-up interest and future plans can affect the decision. Equity release can reduce your estate’s value and affect entitlement to means-tested benefits, so specialist regulated advice is essential.
How to Choose the Right Adviser for LL55
The nearest office is not automatically the strongest match. A Mortgage Broker in Llanberis should explain the mortgage types they advise on, their lender access, any fees and how they will communicate throughout the application. Ask whether they have experience with older construction or holiday-let lending if either applies to your plans.
Welsh is important to everyday life in Gwynedd. If you would prefer to discuss your finances in Welsh or another language, look for bilingual mortgage brokers and confirm the adviser’s language availability. You can also check the firm’s authorisation and relevant permissions on the FCA Financial Services Register.
Start With the Right Mortgage Questions
Speak with a Mortgage Broker in Llanberis by using the Connect Experts mortgage adviser directory. Compare adviser profiles, specialisms, languages and contact options, then choose someone who can explain the implications of your borrowing as clearly as the potential benefits.




