Ashkirk Mortgage Advice: Make Your Rural Move Count
A Mortgage Broker in Ashkirk can help you make a better-informed financial decision, because a home’s character matters as much as its postcode.
Ashkirk sits within the rural Scottish Borders, where buyers may encounter traditional cottages, detached homes, larger plots and properties with outbuildings. Those features can create different questions for mortgage lenders.
The aim is not simply to find a mortgage. It is to understand how the property, deposit, income and future plans fit the lender’s criteria.
At a glance: Mortgage Broker in Ashkirk
- Ashkirk falls within the TD7 postcode area.
- The local market includes cottages, detached homes and properties surrounded by countryside.
- Land, outbuildings, private services or unusual construction can affect a lender’s assessment.
- The average house price in the Scottish Borders was £195,000 in August 2026.
- First-time buyers in the Scottish Borders paid an average of £150,000 during the same month.
- Detached homes averaged £374,000, showing how property type can create a significant price difference.
- Buyers in Scotland should consider the Home Report and Land and Buildings Transaction Tax.
- Specialist experience may matter more than choosing an adviser purely because they are nearby.
A Rural Home Can Ask Different Questions
A Mortgage Broker in Ashkirk may need to look beyond the purchase price when helping with a rural property.
A conventional house on a standard residential plot may fit straightforward lending criteria. A cottage with acreage, agricultural restrictions, several outbuildings or private drainage may require more investigation.
Lenders can consider factors such as:
- the property’s construction;
- the amount and use of surrounding land;
- access arrangements and shared tracks;
- private water or drainage;
- agricultural or occupancy restrictions;
- separate annexes or buildings;
- commercial activity taking place at the property;
- whether part of the property will be let.
This does not automatically make a property unsuitable for mortgage lending. It means the details should be understood before approaching a lender.
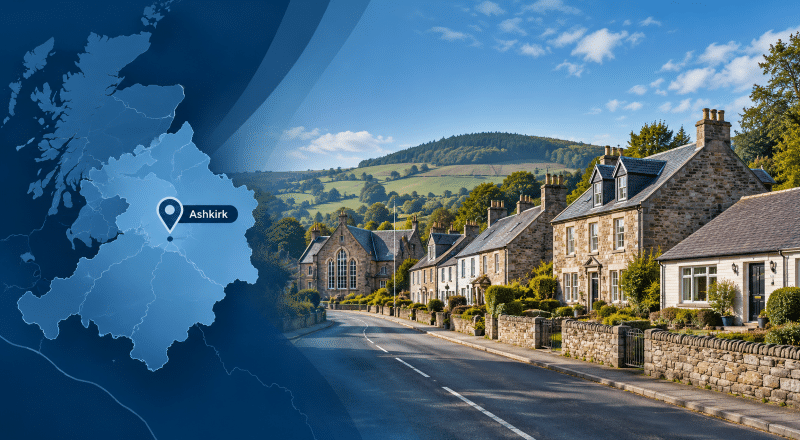
The property photographs available around Ashkirk illustrate why this matters. Homes can sit within substantial rural plots rather than standard urban streets.
Start With the Home Report, Not Just the Asking Price
Scotland has its own home-buying process.
A Home Report normally contains a Single Survey, Energy Report and Property Questionnaire. The system was introduced to give prospective buyers information about a property’s condition before an offer is submitted.
The valuation within the report can be particularly important for mortgage purposes.
A lender will usually base lending on the lower of the purchase price or an acceptable valuation. Therefore, offering significantly above the valuation may increase the amount you need to fund personally.
Buyers should also examine repairs noted within the report.
A lender may want more information if there are concerns about structural movement, damp, roofing, non-standard materials, or other substantial defects.
Mortgage Costs Around Ashkirk
Understanding affordability means looking beyond the mortgage rate.
Scottish Borders house prices vary considerably by property type. Official August 2026 data recorded an overall average of £195,000, compared with £374,000 for detached properties.
These are Scottish Borders averages rather than Ashkirk-specific valuations. Individual rural properties can vary significantly depending on condition, land, and setting.
Before choosing a deal, buyers can also review current products using the UK Mortgage Rates comparison page.
The lowest headline rate is not automatically the cheapest mortgage.
Arrangement fees, valuation charges, incentives, early repayment charges and the initial deal period can all affect the total cost.
Buying Property in Scotland and LBTT
A Mortgage Broker in Ashkirk can help with the mortgage calculation, but buyers should also budget for Scotland’s property transaction costs.
Scotland uses Land and Buildings Transaction Tax, usually called LBTT, rather than Stamp Duty Land Tax.
Revenue Scotland currently applies residential rates in bands. First-time buyer relief can increase the nil-rate threshold to £175,000 where the qualifying conditions are met.
You can check the current rules directly through Revenue Scotland’s residential property guidance.
People buying an additional property should also check whether the Additional Dwelling Supplement applies.
Tax rules can change, so confirm the position that applies when your transaction takes place.
Different Plans Need Different Mortgage Expertise
Two buyers considering similar Ashkirk properties may need completely different mortgage routes.
A first purchase may require deposit evidence, affordability checks, and an understanding of the Scottish offer process. Our first-time buyer mortgage advisers can help you explore suitable options.
If you’re approaching the end of an existing deal, you may benefit from speaking with a mortgage rate-ending adviser. This gives you time to compare staying with your current lender against moving elsewhere.
A property being purchased for rental purposes raises different questions.
Depending on your plans, you may need expertise in:
- becoming a first-time landlord;
- financing several properties as a portfolio landlord;
- purchasing through a limited company;
- arranging a short-term buy-to-let bridge loan.
Rental income, property type, ownership structure and your wider portfolio can influence which lenders are appropriate.
When Rural Property Becomes More Complex
Not every property fits neatly into a standard residential mortgage.
A house combined with workshops, substantial commercial premises or investment property may require specialist assessment.
In those circumstances, expertise might include:
- owner-occupied commercial mortgages where premises support your own business;
- commercial investment property finance where property is held as an investment;
- development finance where significant building work or development is planned;
- short-term bridge loans where appropriate short-term funding is required.
The important question is not whether a property looks unusual. It is how the lender classifies both the property and your intended use.
Choosing a Mortgage Broker in Ashkirk
The nearest adviser is not automatically the adviser with the most relevant experience.
Before choosing someone, ask:
- Do they regularly deal with Scottish property purchases?
- Have they advised on rural or non-standard homes?
- Can they explain how a lender may view land and outbuildings?
- Which lenders can they consider?
- What fees will you pay?
- How will appointments take place?
- Are they appropriately authorised?
For rural purchases, early conversations can be useful.
Providing the Home Report and explaining exactly how the property will be used can help identify potential lending issues before they become problems later.
Protecting the Home You Are Working Towards
Buying a home creates responsibilities that can last for many years.
Mortgage advice can therefore be considered alongside suitable protection planning.
A protection mortgage adviser can discuss relevant options, including life insurance, critical illness cover, or income protection.
The appropriate protection depends on your circumstances, employment, family commitments and existing cover.
Protection policies have exclusions, limitations and eligibility requirements, so the details should be considered carefully.
Later-Life Borrowing in Ashkirk
A Mortgage Broker in Ashkirk may also help older borrowers explore conventional mortgage options where suitable.
Age alone does not determine whether borrowing is possible. Lenders can consider income, pension arrangements, affordability, mortgage term and repayment strategy.
Later-life lending and equity release are specialist areas and should be considered separately from a standard residential mortgage.
Equity release can reduce the value of your estate and may affect entitlement to means-tested benefits. Specialist advice is therefore important before proceeding.
Look at the Property Before Looking at the Product
The right mortgage starts with understanding what you’re actually buying.
That principle matters in Ashkirk, where a property’s land, construction, access, or outbuildings could matter as much as the number of bedrooms.
Once those details are clear, an adviser can consider lenders whose criteria better suit the property and your circumstances.
Search for a Mortgage Broker in Ashkirk through Connect Experts and find an adviser whose experience matches the property and borrowing you have in mind.