
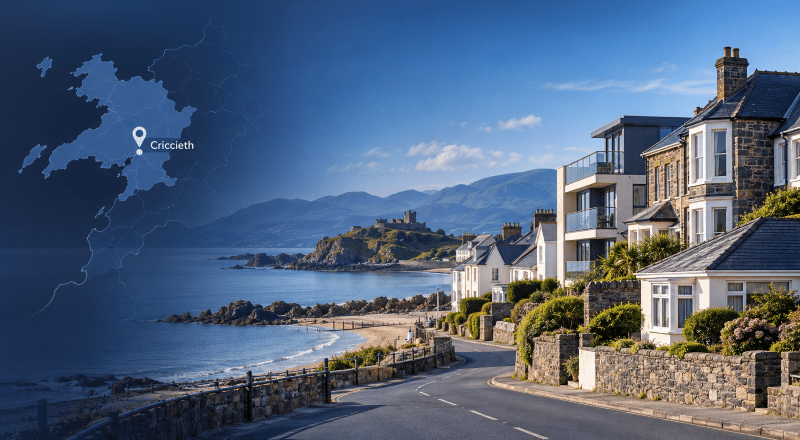
A Mortgage Broker in Criccieth should help you look beyond a property’s appeal and understand what makes it a sound financial commitment.
Criccieth has a character that few coastal towns can replicate. Its medieval castle overlooks two beaches, while traditional homes, residential streets and the surrounding countryside offer different ways to live beside Cardigan Bay.
Yet buying in an attractive location still requires practical thinking. Property condition, mortgage affordability, insurance and your intended use of the home can all influence your borrowing options.
Whether youare buying your first property, moving to Gwynedd, or reviewing an existing mortgage, Connect Experts helps you find advisers whose experience matches your plans.
At a glance: Mortgage Broker in Criccieth
- Location: Criccieth is a coastal town on the southern Llŷn Peninsula in Gwynedd, between Porthmadog and Pwllheli.
- Postcode: LL52 covers Criccieth and surrounding communities, including Llanystumdwy.
- Property character: Buyers may encounter traditional stone properties, older terraced homes, coastal residences and more modern housing.
- Historic surroundings: Criccieth Castle stands on a headland between two beaches. Parts of the town fall within a designated conservation area.
- Transport: Criccieth railway station provides access to the Cambrian Coast Line.
- Coastal considerations: Flood exposure, erosion, building condition and insurance availability should be assessed for individual properties.
- Investment properties: Holiday accommodation and second homes may require different mortgage arrangements from permanent residences.
- Welsh property tax: Land Transaction Tax applies to qualifying Welsh property purchases, with higher rates potentially applying to additional homes.
A Coastal Address Is Only Part of the Property’s Story
Living near the sea can be rewarding, but coastal homes raise practical questions you should consider before committing to a purchase.
Criccieth’s housing includes properties close to the shoreline, established streets around the town centre and residential areas further inland.
A Mortgage Broker in Criccieth may help you identify lenders willing to consider the property you wish to purchase. However, the lender’s valuation and underwriting process will determine whether the property is acceptable security.
For older or coastal properties, consider:
- Construction and condition: Are there signs of damp, weather-related deterioration or previous structural repairs?
- Location: Is the property close to an area potentially affected by coastal flooding or erosion?
- Insurance: Can suitable buildings insurance be obtained at an affordable price?
- Conservation status: Could the property’s location affect future alterations or renovation plans?
- Valuation: Will the lender regard the property’s construction, condition and marketability as acceptable?
Criccieth has a designated conservation area. Therefore, buyers considering alterations should check the relevant requirements with Cyngor Gwynedd.
For homes near the shoreline, the Natural Resources Wales flood risk map provides useful property-level information.
These considerations do not automatically make a coastal property unsuitable for mortgage lending. They help establish whether the home, lender and proposed borrowing are compatible.
Buying Your First Home or Moving to Gwynedd
A first purchase and a move from an existing property can lead to very different financial decisions.
First-time buyers may concentrate on saving a deposit and understanding their monthly commitments. Existing homeowners may need to coordinate a sale, arrange another mortgage and consider any early repayment charges.
Before making an offer in Criccieth, establish:
- How much you can borrow based on your income and financial commitments.
- What deposit or existing property equity is available.
- Whether the property meets your lender’s criteria.
- How mortgage fees, legal costs, surveys and Land Transaction Tax affect your overall budget.
- Whether your chosen mortgage provides sufficient flexibility for future changes.
Find advisers experienced in first-time buyer mortgages through Connect Experts.
Remember that property purchases in Wales are subject to different transaction tax arrangements from England and Northern Ireland. Check the current Land Transaction Tax rates and bands before estimating your purchase costs.
Criccieth Holiday Homes: Think About the Intended Use
A property beside the sea may appeal as a permanent residence, occasional retreat or holiday rental. These uses can create different mortgage requirements.
For a holiday-let purchase, a Mortgage Broker in Criccieth with relevant specialist experience may help you assess lending options before submitting an application.
Lenders may consider expected seasonal rental income, occupancy assumptions, property management arrangements and how often you intend to use the property personally.
Useful adviser searches include:
- Holiday Let Mortgage Brokers for properties intended for short-term guest accommodation.
- First-Time Landlord Advisers for buyers considering their first long-term rental property.
- Limited Company Buy-to-Let Advisers where a company ownership structure is being considered.
- Portfolio Landlord Mortgage Advisers for investors managing multiple rental properties.
What about local planning rules?
Planning requirements and mortgage lending rules should be considered separately.
As at October 2026, Cyngor Gwynedd confirms that its Article 4 Direction concerning changes between main residences, second homes and short-term holiday lets is no longer in force following a court ruling.
However, other planning controls may still apply. Eryri National Park has separate arrangements. Buyers should confirm the rules for their property rather than assuming all Gwynedd properties are treated the same.
Read the current Gwynedd Article 4 guidance before proceeding.
Your Mortgage Rate Is Ending: Consider the Total Cost
An existing mortgage can become more expensive when an introductory deal ends. Review your options in advance to give yourself more time to compare products.
A Mortgage Broker in Criccieth may help you assess whether to remain with your current lender or consider moving your mortgage elsewhere.
Your decision should account for more than the initial interest rate.
Check the product fee, estimated repayments, deal period, early repayment charges and any changes in your circumstances since the original mortgage was arranged.
You can:
- Compare UK Mortgage Rates to explore available deals, estimated repayments and product costs.
- Find a Mortgage Rate Ending Adviser to discuss refinancing and related lending requirements.
Mortgage comparison results do not guarantee eligibility. Your income, credit history, property and lender criteria will still be assessed.
Protecting Your Home and Household Income
A mortgage may help you purchase a home, but it also creates a financial commitment that continues long after completion.
Consider what would happen if illness, injury or the loss of a household income made repayments difficult.
Depending on your circumstances, protection advice may cover life insurance, critical illness cover and income protection.
Each policy has different benefits, eligibility requirements, conditions and exclusions. The right arrangement should reflect your budget and household responsibilities.
Connect Experts provides access to Protection Mortgage Brokers who can explain relevant cover and help you consider how to protect your financial commitments.
Protection advice deserves the same attention as mortgage affordability, not as an afterthought.
Equity Release and Later-Life Mortgage Options in Criccieth
For some homeowners, the next financial decision is not about moving. It is about making existing property wealth work alongside retirement plans.
Homeowners aged 55 or over may wish to explore equity release, later-life remortgaging or other borrowing arrangements.
However, a property’s value alone does not determine whether equity release is suitable.
An adviser must consider the homeowner’s age, circumstances, property, existing borrowing, future plans and available alternatives.
Connect Lifetime provides a dedicated guide to Equity Release Advisers in Gwynedd, including how property characteristics can influence later-life lending decisions.
Equity release may reduce the value of your estate and affect entitlement to means-tested benefits. Interest can accumulate over time, and specialist advice is essential.
Finding an Adviser Who Understands Your Plans
The nearest mortgage adviser isn’t necessarily the most suitable.
Local knowledge can be helpful, particularly when buying a traditional property or considering an unusual building. Yet access to lenders, specialist experience, and clear communication can be equally important.
Choosing a Mortgage Broker in Criccieth should involve asking practical questions:
- Has the adviser handled a mortgage similar to yours?
- Can they explain their range of lenders and products?
- What fees apply, and when must they be paid?
- Do they have experience with the type of property you’re buying?
- Are telephone, online or face-to-face appointments available?
- Does the firm hold the appropriate regulatory permissions?
Welsh is an important part of life across Gwynedd. If you would prefer to discuss your mortgage in Welsh or another language, explore Bilingual Mortgage Brokers and confirm your preferred language is available with the individual adviser.
You should also verify the firm’s details and permissions using the FCA Financial Services Register.
Your Next Move Starts With Better Questions
Criccieth offers more than an attractive coastal setting. It offers different property choices and ways of living, each carrying its own financial considerations.
The best mortgage decisions start with understanding the property, recognising the costs, and asking the right questions before committing.
Connect Experts helps you search for advisers by location, expertise, language and personal preference. Review profiles before deciding whom to contact.
Find a Mortgage Adviser and explore available advisers serving Criccieth and the wider Gwynedd area.




