
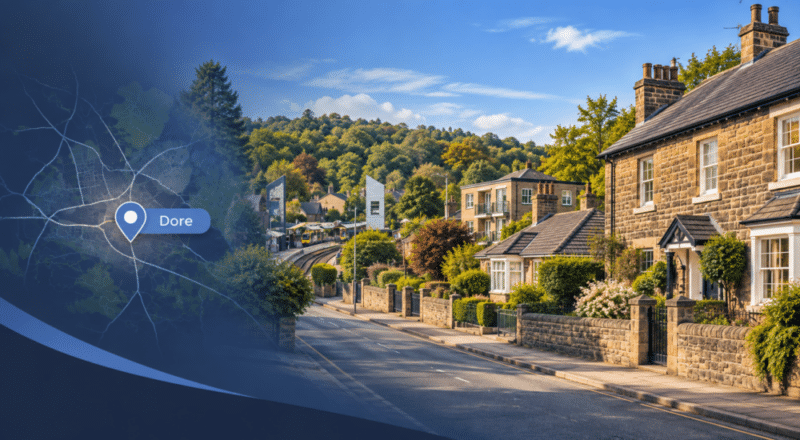
A Mortgage Broker in Dore can help you look beyond the asking price and understand how a lender may view both your finances and the particular home you want to mortgage.
That matters in a place where homes aren’t uniform.
Dore sits on Sheffield’s south-western edge and retains a distinctive village core. Sheffield City Council records that the conservation area includes buildings dating from the eighteenth century onwards, historic lanes, local stone architecture and a number of Grade II listed buildings.
At the same time, the local housing market includes substantial detached and semi-detached properties with values that can sit considerably above wider Sheffield averages.
The mortgage question can therefore become more nuanced:
How should the borrowing be structured when the property, loan amount and applicant’s finances all need to satisfy the lender?
At a glance: Mortgage Broker in Dore
Finding a Mortgage Broker in Dore can be particularly useful when the property value, income structure or home itself needs more detailed lender assessment. Dore combines higher-value homes with an historic conservation area and access to Sheffield and the rail network. Mortgage size, valuation, construction, deposit, income and longer-term affordability may therefore all influence the lending route.
Why Dore’s Housing Character Matters to Mortgage Lending
Dore Conservation Area was designated in 1971.
The City Council identifies the historic street pattern, stone construction, listed buildings, boundary walls and other traditional features as important parts of its character.
A conservation-area location does not automatically make it difficult to obtain a mortgage.
Nor does an older home automatically require specialist finance.
However, certain properties can lead lenders or valuers to look more closely at matters such as:
- construction and materials;
- structural condition;
- previous alterations;
- listed status, where applicable;
- marketability;
- access;
- planning restrictions;
- the property’s suitability as mortgage security.
A lender valuation primarily protects the lender’s interests. It should not be confused with a detailed building survey.
For somebody buying an older or less conventional Dore home, a more detailed survey may therefore provide information that a standard mortgage valuation is not designed to give.
Dore’s adopted Neighbourhood Plan also forms part of the local planning context. Sheffield City Council confirms that the plan was adopted in October 2021, with part of the neighbourhood area extending into the Peak District National Park Authority.
That makes local planning and property characteristics more meaningful here than on a generic city-wide mortgage page.
A Higher-Value Local Market Changes the Numbers
Someone looking for a Mortgage Broker in Dore may be borrowing against a property value that differs substantially from Sheffield-wide averages.
ONS reported the average Sheffield house price at £220,000 in July 2026. The provisional average for a home purchased with a mortgage was £224,000.
Dore-specific commercial sold-price data paints a different local picture.
Rightmove reported an overall Dore sold-price average of approximately £612,000 over the previous year. Detached homes accounted for much of the local activity and averaged around £763,000.
These are not directly comparable statistical datasets, so the figures should not be used to calculate a precise Dore premium over Sheffield.
What they do show is that Dore contains a meaningfully higher-value housing segment.
That can influence practical mortgage decisions.
A larger property price may mean:
- a larger cash deposit;
- a higher mortgage balance;
- greater Stamp Duty Land Tax exposure;
- more equity being transferred from an existing home;
- closer scrutiny of income and expenditure;
- different loan-to-value considerations;
- additional underwriting where income is complex.
An applicant with a large deposit can still fail affordability.
Likewise, someone with substantial income can encounter difficulties if the lender does not treat bonuses, dividends, retained profits, or other income as expected.
The size of the property transaction is only one part of the assessment.
Moving to Dore: Equity and Borrowing Need to Be Considered Together
Dore’s housing profile also makes home-moving particularly relevant.
ONS recorded an average price of £264,000 for Sheffield home movers in July 2026. That is a city-wide figure and should not be treated as a Dore purchase price.
For someone moving into a higher-value Dore property, existing home equity can become an important part of the calculation.
Consider a homeowner who has built substantial equity in their current property.
Selling that home may provide a sizeable deposit, but the lender still needs to determine whether the new mortgage is affordable.
That assessment may include:
- current basic income;
- bonuses or overtime;
- self-employed earnings;
- existing loans and credit commitments;
- childcare and dependants;
- mortgage term;
- deposit or equity;
- proposed borrowing;
- the new property itself.
Homeowners should also check whether they can port their existing mortgage.
Porting does not mean simply moving the mortgage from one address to another.
The lender normally carries out a fresh affordability assessment and considers whether the new property meets its criteria.
The Moving Home Mortgage Guide explains how porting, additional borrowing, equity and lender reassessment can interact.
Sometimes keeping an existing mortgage product may be worthwhile.
In other cases, changing lenders may be worth considering.
The useful comparison is the total financial effect, including rates, fees, early repayment charges and any additional borrowing.
Higher-Value Mortgages and Complex Income in Dore
Dore is one of the locations where a higher-value mortgage section has a genuine local reason to exist.
That does not mean every Dore homeowner or buyer is high-net-worth.
Property value and personal wealth are not the same thing.
However, where a higher-value Dore purchase is combined with larger borrowing or complex financial circumstances, standard affordability calculations may not always tell the whole story.
Connect Experts’ High Net Worth Mortgage Brokers resource explains circumstances including:
- substantial mortgage requirements;
- company ownership;
- retained profits;
- bonuses;
- partnership income;
- investment income;
- multiple income sources;
- overseas income;
- wider assets.
Connect Experts also explains that its high-net-worth mortgage definition follows specific financial thresholds and circumstances, not simply the postcode or value of someone’s home.
A business owner, for example, may have a modest salary but significant profits retained inside their company.
Another applicant may receive a substantial annual bonus.
A third may own investments or other assets while drawing comparatively little regular income.
Different lenders can assess these circumstances differently.
In these cases, the value of advice is often not about finding an exclusive lender. It is about finding a lender whose underwriting method reflects how the applicant’s finances genuinely work.
Dore & Totley Station and the Household Budget
Transport does not determine whether a mortgage application succeeds.
It can, however, influence the household budget that sits behind the decision.
Dore & Totley station is located on Abbeydale Road South. National Rail lists parking for 120 vehicles, cycle storage, bus connections and step-free access to all platforms.
For someone buying in Dore because the location works with their employment or travel patterns, commuting costs should form part of their personal affordability assessment.
That could include:
- rail fares;
- parking;
- fuel;
- working-from-home patterns;
- childcare arrangements;
- travel to different employment locations.
A lender’s affordability model and a household’s comfort level are not necessarily the same.
Someone could theoretically meet lender criteria but decide the resulting monthly commitment leaves too little flexibility for their preferred lifestyle.
A sustainable mortgage decision therefore asks two questions:
What will the lender allow?
And:
What commitment is the household comfortable maintaining?
First-Time Buyers Looking at Dore
A first purchase in Dore can require particularly careful deposit planning because parts of the local market sit above Sheffield-wide first-time buyer averages.
ONS recorded an average first-time buyer price of £194,000 across Sheffield in July 2026.
This does not mean a first-time buyer should expect to find a Dore property at that value.
Nor does Dore’s higher-value housing mean first-time purchases are impossible.
Instead, buyers should base their search on what they can actually afford.
Before making an offer, it can be useful to understand:
- the available deposit;
- achievable borrowing;
- anticipated monthly repayments;
- purchase taxes and legal costs;
- whether income meets lender criteria;
- whether the property itself is acceptable.
You can search for a first-time buyer mortgage adviser through Connect Experts. The directory allows users to compare advisers rather than directing them to one specific firm.
Protection Where the Financial Commitment Is Larger
Protection deserves particular thought when a household takes on a significant mortgage.
Higher property wealth does not necessarily mean somebody has large amounts of immediately accessible cash.
The mortgage, family expenditure and other commitments still have to be maintained if income changes.
Depending on individual circumstances, a protection review might consider:
- life insurance;
- critical illness cover;
- income protection;
- existing employer benefits;
- mortgage liabilities;
- family expenditure;
- business-related risks.
Borrowers can search for Protection Mortgage Brokers where a standard household protection review is appropriate.
Where borrowing, business ownership, assets or family financial commitments are substantially more complex, High-Net-Worth Protection Services may also be relevant.
The purpose is not simply to insure the property’s value.
It is to consider what financial obligations would remain if death, serious illness or loss of income disrupted the household’s plans. Connect Experts’ HNW protection guidance specifically identifies large mortgages, complex income and business interests as factors that can make the discussion more involved.
Later-Life Mortgage Choices in South Yorkshire
For some long-term homeowners, the mortgage question changes with age.
It may move from purchasing a property to considering how an existing home fits retirement plans.
Options could include a standard residential mortgage extending into retirement, retirement interest-only borrowing or, where suitable, equity release.
These are different forms of borrowing.
Age alone does not determine which route is suitable.
Income, property value, existing borrowing, mortgage term and longer-term intentions can all matter.
Users considering conventional later-life lending can search for advisers through the Connect Experts residential directory.
Where the enquiry concerns equity release specifically, the relevant regional resource is Equity Release Advisers in South Yorkshire.
Equity release is a long-term financial commitment. It can reduce the value of an estate and may affect entitlement to means-tested benefits, so regulated advice is required.
What Should You Look for in a Mortgage Broker in Dore?
The nearest adviser isn’t automatically the adviser with the most relevant experience.
A first-time buyer may need help understanding deposit and affordability.
A homeowner moving into a larger property might need to compare porting against a new mortgage.
A company director may need an adviser familiar with retained profits.
Someone buying a high-value home may require experience with larger mortgages and detailed underwriting.
Connect Experts lets users search advisers by criteria including location, language, gender, company, and mortgage area.
Connect Experts itself does not provide mortgage advice.
It operates as a mortgage adviser directory and matching platform. The adviser or firm selected by the user provides advice.
Frequently Asked Questions
How do I find a Mortgage Broker in Dore?
Use the Connect Experts directory to compare mortgage advisers who can cover Dore and South Yorkshire. You can narrow your search by location, mortgage requirement, language, gender preference, and other relevant criteria.
Are Dore house prices higher than the Sheffield average?
Available sold-price data indicates a substantial difference. ONS reported a Sheffield average of £220,000 in July 2026, while Rightmove’s Dore data showed an average of about £612,000 over the preceding year. These sources use different methodologies and cover different areas, so view them as market context rather than a direct statistical comparison.
Does buying in the Dore Conservation Area make getting a mortgage harder?
Not automatically. However, a lender’s valuer may consider construction, condition, alterations and marketability. Listed buildings or unusual construction can require additional assessment depending on the property and lender. Sheffield City Council confirms that Dore’s conservation area contains historic buildings, local stone construction and listed properties.
Do I need a high-net-worth mortgage because I am buying in Dore?
No. A high property price alone does not determine whether somebody is a high-net-worth mortgage customer. Large borrowing, income structure, assets and wider financial circumstances are more relevant to deciding whether specialist HNW mortgage advice may be appropriate.
Can I port my existing mortgage when moving to Dore?
Possibly. Portability depends on the mortgage terms and lender. The lender normally reassesses your current affordability and the new property before approving the move.
Find a Mortgage Broker in Dore for Your Circumstances
A property can look straightforward from the road while presenting a very different picture to a mortgage underwriter.
In Dore, that distinction can matter.
Older housing, conservation considerations, higher property values, larger deposits and more substantial borrowing can each change the questions that need answering.
Connect Experts helps you compare advisers and identify someone whose experience reflects the mortgage you actually need.
Search the Connect Experts Mortgage Adviser Directory




