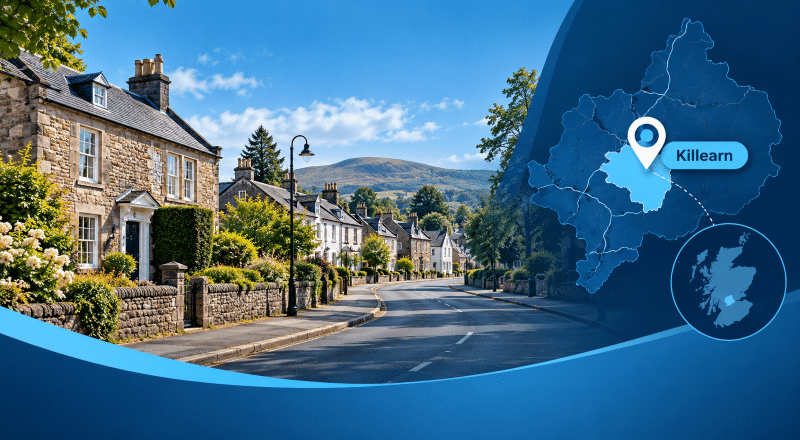
A Mortgage Broker in Killearn can help you look beyond a home’s appeal and consider the financial commitment that comes with it. A property may offer beautiful surroundings, generous space or a fresh start, but the mortgage must also make sense for the years ahead.
Killearn sits within the G63 postcode area of Stirlingshire, surrounded by the Strathendrick countryside and the Campsie Fells. Its historic village centre, established residential streets and nearby rural properties create different considerations for mortgage applicants.
Whether you are buying your first home, moving from Glasgow, refinancing, or purchasing a country property, understanding lender requirements before you commit can help you make a more informed decision.
Connect Experts helps you compare mortgage advisers by location, experience, language and specialism. You can explore adviser profiles and choose who to contact.
At a glance: Mortgage Broker in Killearn
- Location: Killearn is a Stirlingshire village within the Stirling Council area, using the G63 postcode district.
- Housing: The village includes traditional stone properties, established family homes and more modern housing.
- Conservation: Part of Killearn is in a conservation area, so property history and alterations are relevant considerations.
- Scottish buying process: Home Reports provide information about property condition, valuation and energy performance.
- Rural properties: Homes outside the village centre may require additional checks on access, services, outbuildings or land.
- Family considerations: Killearn Primary School and access to surrounding communities may influence where buyers choose to live.
- Mortgage advice: An adviser’s understanding of Scottish property purchases, affordability and lender criteria may matter more than physical distance.
When the Home Report and Your Offer Tell Different Stories
Buying a property in Scotland involves financial considerations that an estate agent’s listing may not make obvious.
A home advertised using an offers-over price may attract bids above its Home Report valuation. However, a lender may calculate the available mortgage against its accepted valuation rather than the price you agree to pay.
This can create an unexpected funding gap.
For example, a buyer may have enough savings for the planned mortgage deposit but still need extra cash if their accepted offer exceeds the lender’s valuation.
Before contacting a Mortgage Broker in Killearn, it helps to understand:
- The property’s Home Report valuation.
- Your proposed purchase price and available deposit.
- Whether you can fund any difference between the valuation and agreed price.
- Potential repair costs identified in the survey.
- Legal fees, Land and Buildings Transaction Tax and other moving expenses.
The Scottish Government explains the purpose of the survey, valuation, property questionnaire and energy assessment in its Home Report guidance.
An adviser can help you assess whether the proposed purchase fits your borrowing capacity, but the lender makes the final lending decision.
Historic Killearn Homes Deserve More Than a Standard Mortgage Check
Killearn’s architectural character is central to its identity.
Traditional buildings around Main Street, the historic village centre and surrounding residential areas sit alongside newer homes. Beyond the settlement, properties may also have larger grounds or countryside features.
These differences can affect how lenders assess a property.
An older stone-built house may raise questions about the roof, construction materials, damp, past alterations or energy performance. A newer property could require checks on building warranties and development arrangements.
Stirling Council has designated a conservation area in Killearn. Buyers considering an older property should check whether it is listed or subject to additional planning controls.
The council’s conservation area information provides a useful starting point.
Properties outside the village centre may have other considerations, including private drainage, water supplies, shared access roads, agricultural land, or buildings used for business.
These features do not automatically prevent mortgage lending. However, they can affect valuation, insurance requirements and the choice of lender.
Understanding these details before applying may help avoid unnecessary delays.
Mortgage Support That Reflects the Way You Live
People looking for homes around Killearn do not all have the same financial circumstances.
Some are purchasing their first property. Others are moving from a larger town or city, seeking more space or reconsidering their mortgage commitments.
The right advice depends on why you’re borrowing.
Buying your first home
If you hope to buy your first property in Killearn, deposit planning and affordability are important starting points. A first-time buyer mortgage broker can explain lender requirements, agreements in principle and the mortgage application process.
Moving home or reviewing your existing deal
Homeowners moving into or within the area may need to sell their current property, transfer an existing mortgage, or arrange new borrowing.
If your fixed or introductory rate is approaching its end, our mortgage rate-ending adviser search can help you find advisers who handle mortgage reviews and refinancing.
Self-employed income and business ownership
Killearn residents who work as contractors, company directors, consultants or sole traders may have income that lenders assess differently.
Our self-employed mortgage brokers directory helps you find advisers experienced in applications involving business accounts, dividends, contracts and variable earnings.
Larger homes and complex financial circumstances
A higher-value countryside property may require a larger mortgage, a substantial deposit, or a more detailed income assessment.
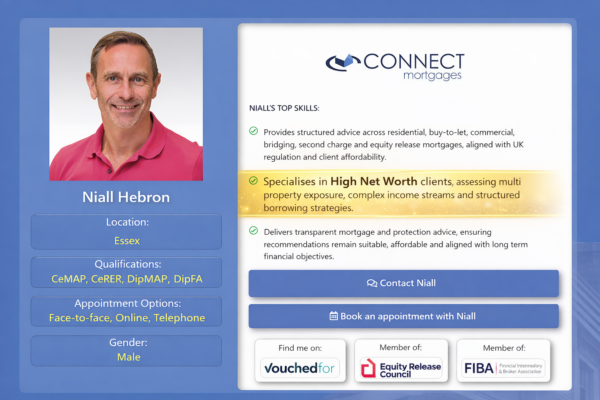
When borrowing involves significant assets, business ownership, or complex income, high net worth mortgage brokers may offer relevant specialist experience.
A Mortgage Broker in Killearn with experience that matches your particular circumstances can help identify lender criteria before a formal application is submitted.
Keeping Your Existing Home or Buying a Rental Property
Moving to Killearn does not always mean selling your previous home.
Some buyers may wish to retain an existing property and let it to tenants. Others may be considering a residential investment within the wider Stirlingshire area.
However, borrowing for a property you intend to let differs from arranging a mortgage for your own residence.
Lenders may assess rental income, existing borrowing, deposit size, property condition and landlord experience.
If you are considering your first rental property, our first-time landlord adviser search can help you identify suitable specialists.
If you buy an investment through a company, a limited company buy-to-let mortgage adviser can explain how lenders assess the ownership structure.
Where an investment property requires significant refurbishment before it can be let, buy-to-let bridging loan advisers may also be relevant. Short-term finance requires a credible repayment strategy and careful cost consideration.
The important distinction is between borrowing for your own home and borrowing for a property intended to generate rental income.
Mortgage Protection: Financial Security Beyond Completion
A mortgage may be arranged over many years, but personal circumstances can change unexpectedly.
Illness, injury, loss of income or the death of a household earner can affect how mortgage payments and other financial commitments are maintained.
When choosing a Mortgage Broker in Killearn, it is sensible to establish whether the adviser can also provide protection advice or whether a separate specialist is required.
Our protection mortgage brokers directory can help you find advisers who deal with:
- Life insurance: Cover that may pay out after death during the policy term.
- Critical illness cover: A potential lump-sum payment following diagnosis of a qualifying serious illness.
- Income protection: Cover designed to replace part of your income if illness or injury prevents you from working.
- Mortgage payment protection: Certain policies may support repayments during specified periods of illness, accident or unemployment, subject to the policy terms.
The right cover depends on your household income, dependants, existing arrangements and monthly budget.
Policy exclusions, waiting periods, premiums and claim conditions should always be reviewed before proceeding.
Equity Release and Later-Life Decisions in Killearn
For homeowners who have lived in Killearn for many years, property wealth may become part of their retirement planning.
Some people consider moving to a smaller home. Others want to stay in familiar surroundings while accessing some of the equity in their property.
Equity release, including lifetime mortgages, is one option for eligible homeowners, but it isn’t suitable for everyone.
Providers assess several factors, including age, property value, outstanding borrowing and the property’s condition and construction.
With a lifetime mortgage, interest may be added to the outstanding loan. This can increase the debt over time and reduce the equity remaining in the property.
It may also affect inheritance and eligibility for means-tested benefits.
Homeowners considering these choices can explore equity release advisers in Stirlingshire through Connect Lifetime.
Specialist advice should consider alternatives, product costs, safeguards and long-term consequences. Independent legal advice is also required before completing an equity release arrangement.
Choosing a Mortgage Adviser Who Understands Your Plans
A good mortgage decision depends on more than identifying the lowest initial interest rate.
The lender must be comfortable with the property, the applicant and the intended borrowing arrangement.
When comparing advisers, consider their experience with Scottish purchases, relevant property types, complex income and any specialist finance requirements.
You should also understand the adviser’s fees, regulatory permissions, lender access and communication arrangements.
To find a Mortgage Broker in Killearn, use the Connect Experts mortgage adviser directory to compare available adviser profiles.
You can search by location, language, and other preferences before choosing who to contact.
The aim isn’t simply to find someone nearby. It is to find someone with the knowledge and permissions to support your particular mortgage requirements.
Start your search with Connect Experts and take the next step towards an informed mortgage decision.