
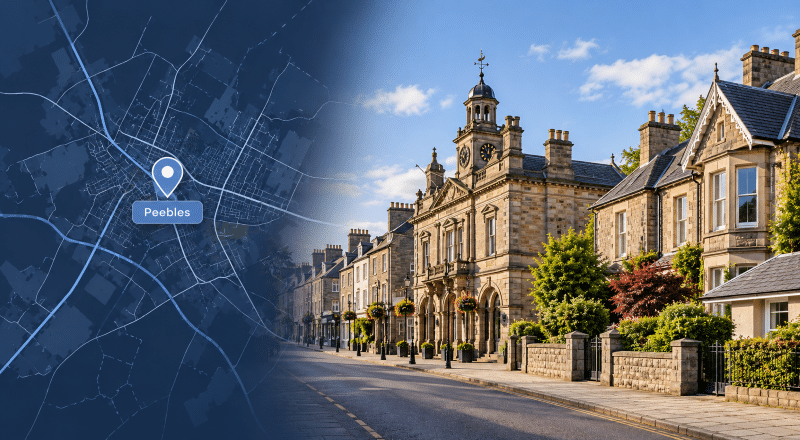
A Mortgage Broker in Peebles can help you see that an offer is more than a number on a page. It is a commitment to monthly repayments, financial security and the life you hope to build beyond collecting the keys.
In Peebles, a home’s character often tells only part of its financial story. A traditional flat near the High Street, a Victorian villa overlooking the River Tweed and a country house towards Eddleston may each raise different questions for a mortgage lender.
The important decision is not simply whether you can borrow enough. It is whether the mortgage, property and monthly commitment make sense together.
Connect Experts helps you find mortgage advisers who can discuss your circumstances, explain your options and support informed decisions before you commit.
At a glance: Mortgage Broker in Peebles
- Peebles is in historic Peeblesshire, now administered by Scottish Borders Council. Its postcode district is EH45.
- Peebles has a designated conservation area covering much of the town, including its historic centre.
- Homes include traditional stone cottages, tenement flats, Victorian villas and more recent residential developments.
- The River Tweed and Eddleston Water make flood-risk and insurance checks relevant for some properties.
- Provisional ONS figures show the average Scottish Borders house price was £195,000 in August 2026.
- First-time buyers across Scottish Borders paid £150,000 on average during the same month. These figures are not specific to Peebles.
- Scottish Home Reports contain important information about condition, valuation and energy performance.
- Rural properties with land, outbuildings or private services may require additional lender consideration.
What Makes Mortgage Advice in Peebles Different?
Peebles has a varied housing market, influenced by its historic streets, riverside setting and surrounding Tweed Valley countryside.
A modern detached house and a traditional sandstone property might have similar asking prices. However, a lender may assess them differently.
For older homes, lenders may consider construction, condition, previous alterations and the surveyor’s valuation. Properties within a conservation area may also require further checks concerning historic features or proposed building work.
Scottish Borders Council’s Peebles Conservation Area information explains the town’s distinctive architecture, including its cottages, tenements and 19th-century villas.
An experienced Mortgage Broker in Peebles can help explain which property characteristics may affect lender selection and which questions should be directed to your surveyor or solicitor.
The aim is to understand any complications before they begin to influence your application.
Understanding the Scottish Home Report Before Making an Offer
Buying a property in Scotland follows a different legal process from purchasing a home in England or Wales.
Most residential properties marketed for sale in Scotland must have a Home Report, although certain exemptions apply.
The report normally contains three sections:
- A single survey covering the property’s condition and valuation.
- A property questionnaire providing information about the home.
- An energy report describing its energy performance.
For buyers considering an older property in Peebles, the report may identify repairs, alterations, or maintenance issues that require further investigation.
The Scottish Government’s Home Report guidance explains what buyers should receive and how the information can support their decision.
However, a Home Report is not a guarantee of mortgage approval. A lender must still be satisfied with the property and its valuation.
Your solicitor will also manage the Scottish offer and missives process. Once missives are concluded, the contract becomes legally binding.
Understanding your borrowing position early can therefore be particularly important.
Borrowing for Traditional Homes and Rural Properties
Peebles sits where the River Tweed and Eddleston Water meet. This setting shapes the town’s character, but it also brings practical considerations.
Homes near watercourses may need additional flood-risk or insurance checks. Risk varies by location and individual property.
The Scottish Environment Protection Agency flood maps provide information about long-term flood risk for an area. These maps do not establish the precise risk for an individual property.
Before committing, buyers should consider whether suitable buildings insurance is available and whether any property-specific investigation is needed.
Outside the town centre, properties towards Eddleston, Cardrona and the surrounding countryside can present different lending considerations.
For example, lenders may need information about:
- Land and outbuildings included in the purchase.
- Access arrangements and private roads.
- Private water supplies or drainage.
- The property’s construction and condition.
- Any separate accommodation or business use.
These features do not automatically prevent mortgage approval. However, they may influence which lenders will consider an application.
For borrowers with substantial assets, complex income, or a particularly high-value purchase, high-net-worth mortgage brokers may offer more suitable specialist experience.
First-Time Buyers in Peebles: Affordability Before Ambition
Buying your first home can be an exciting achievement. Yet the most important figure is not always the maximum amount a lender might offer.
It is the repayment you can comfortably maintain.
The provisional average first-time buyer price across Scottish Borders was £150,000 in August 2026, according to the Office for National Statistics.
However, individual properties in Peebles can differ significantly from regional averages. Your budget should reflect the home you intend to purchase, not a general market figure.
A first-time buyer should consider the deposit, borrowing requirements, monthly expenditure and additional buying costs.
A first-time buyer mortgage adviser can explain affordability assessments, deposit requirements, credit checks and the documentation lenders may request.
This is especially useful for buyers with variable income, recent employment changes or financial commitments that need careful consideration.
Mortgage Rates in Peebles: Understand the Full Commitment
The lowest advertised interest rate is not necessarily the least expensive mortgage overall.
Arrangement fees, the initial product period, repayment type, mortgage term and early repayment charges can all change the total cost.
A Mortgage Broker in Peebles can help you compare suitable options against your income, deposit, borrowing requirements and longer-term plans.
For example, a shorter fixed-rate period may offer an attractive initial rate but require you to review your mortgage sooner. A longer fixed period may offer more payment certainty, although conditions and charges can affect flexibility.
Before choosing a product, use Connect Mortgages’ UK Mortgage Rates comparison tool to explore available rates and associated costs.
The results provide a useful starting point, but eligibility depends on lender criteria, affordability, credit history and the property.
When Your Existing Mortgage Rate Is Ending
Homeowners in Peebles should consider their next mortgage decision before their existing deal expires.
You may be able to move to another product with your existing lender or remortgage elsewhere. The appropriate choice depends on available rates, fees, affordability and any early repayment charges.
If your current deal is approaching its end, find a mortgage rate-ending adviser who can help you review your options.
A well-timed review may help you avoid unnecessary uncertainty about future monthly payments.
Buying a Property to Let in Peebles
A rental property introduces different financial considerations from buying a home to occupy yourself.
A Mortgage Broker in Peebles with relevant buy-to-let experience can explain how lenders assess rental income, deposits, landlord experience and the property’s intended use.
If youare buying your first rental property, a first-time landlord mortgage adviser can help you understand the requirements before you apply.
For applicants considering a company ownership structure, limited company buy-to-let mortgage advisers can discuss lender criteria for company-held investment properties.
Existing landlords looking to expand their holdings may benefit from speaking with portfolio landlord mortgage advisers.
Lenders may assess the wider rental portfolio, outstanding borrowing and financial commitments rather than considering one property in isolation.
If you intend to purchase premises for a business you operate yourself, you’ll need a different type of borrowing. An owner-occupied commercial mortgage adviser may be more appropriate.
Protection Advice: Looking After More Than Your Mortgage
A mortgage may make homeownership possible, but it does not automatically protect your household against financial disruption.
An unexpected illness, injury, or loss of income could affect your ability to keep up with repayments.
For families, self-employed borrowers and homeowners with financial dependants, appropriate protection deserves consideration alongside the mortgage itself.
Protection mortgage brokers can help clients review options such as life insurance, critical illness cover and income protection.
Each serves a different purpose.
Life insurance may provide financial support to beneficiaries following death. Critical illness cover can pay a benefit when a covered condition meets the policy definition. Income protection may provide regular payments if a qualifying illness or injury prevents you from working.
Policy terms, exclusions, eligibility and costs vary.
The objective is not necessarily to purchase every form of cover. The goal is to identify financial vulnerabilities and determine whether suitable protection can address them.
Equity Release and Later-Life Mortgage Advice in Peeblesshire
For some homeowners, mortgage decisions become more personal as retirement approaches.
You may want to repay an outstanding mortgage, adapt your home or understand whether property wealth could support your later-life plans.
However, conventional remortgaging, later-life lending and equity release are not interchangeable.
Some homeowners may qualify for standard mortgage products, while others may need specialist later-life advice.
Connect Lifetime provides a dedicated guide to equity release advisers in Peeblesshire.
The guide explains how property valuation, existing borrowing, lender criteria and financial circumstances can affect later-life borrowing options.
A lifetime mortgage is secured against your home. Interest may accumulate and compound where repayments are not made. Equity release will reduce the value of your estate and may affect entitlement to means-tested benefits.
If you are appropriately qualified and regulated, equity release advice and independent legal advice are essential before proceeding.
Questions Buyers Often Ask About Peebles Mortgages
What happens if I offer more than the Home Report valuation?
A lender will assess the purchase price against the valuation it accepts for mortgage purposes. Many lenders calculate the loan-to-value ratio using the lower of the purchase price and valuation.
If your offer exceeds the accepted valuation, you may need additional funds to cover the difference.
Discuss this with your mortgage adviser and solicitor before committing to an offer.
Do I pay Stamp Duty when buying a home in Peebles?
Scotland uses Land and Buildings Transaction Tax (LBTT) instead of Stamp Duty Land Tax.
Whether you pay LBTT depends on the purchase price and your circumstances. Eligible first-time buyers may qualify for relief, while an additional property can attract further tax.
You can check the rules through Revenue Scotland’s LBTT guidance.
Can I obtain a mortgage for a Peebles flat above commercial premises?
Potentially, yes. However, lenders may consider the nature of the commercial premises, access arrangements, construction, valuation and insurance.
Some lenders restrict certain types of adjoining or neighbouring businesses.
An adviser can help identify lenders whose criteria may accommodate the property.
Find the Right Mortgage Advice for Your Next Move in Peebles
A property may feel right from the first viewing. A mortgage deserves a more measured decision.
The right adviser should understand your borrowing needs, explain your options, and help you spot potential complications before they become costly.
Search for a Mortgage Broker in Peebles through the Connect Experts mortgage adviser directory.
You can compare advisers by location, language, gender and relevant mortgage expertise, then decide who you would like to contact.
A confident decision begins with understanding what you are committing to, not simply what you can borrow.




