A Mortgage Broker in Portrush can help you look beyond the attraction of a coastal address and focus on what will make the borrowing work in practice. A home is never only a postcode or a view. It is a long-term commitment shaped by affordability, property type, intended use, lender criteria and the life you expect to build around it.
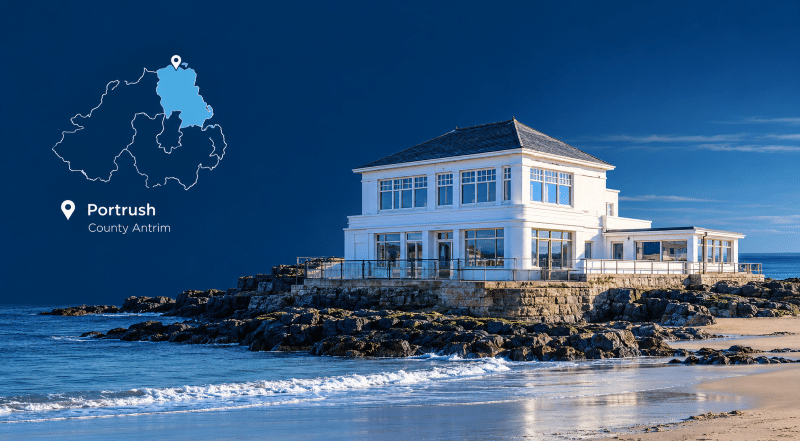
Portrush has a distinct property story. The town sits on a peninsula on Northern Ireland’s north coast, with East Strand, West Strand and Whiterocks helping to define its appeal. That lifestyle can attract owner-occupiers, first-time buyers, home movers and property investors, but each may need a different mortgage route.
At a glance: Mortgage Broker in Portrush
- Portrush uses the BT56 postcode area.
- The town is an established coastal and holiday destination on the Causeway Coast.
- Local properties include apartments, terraces, traditional houses, and homes suited to permanent or short-stay use.
- The average house price in Causeway Coast and Glens was about £219,000 in April to June 2026, up 9.6% year-on-year.
- East Strand stretches about 2.5 km, with West Strand and Whiterocks adding to the town’s strong coastal identity.
- A property intended for holiday letting may require a different mortgage from one bought as a main residence.
- Adviser experience with coastal, landlord and specialist property cases can be more useful than simply choosing the closest adviser.
For wider market context, buyers can also review official Causeway Coast and Glens housing data from the ONS.
Why Portrush Can Change the Lending Conversation
A lender does not approve a mortgage because a property is attractive. It looks at whether the applicant and the security fit its rules.
For a coastal home, the valuation may need to consider condition, construction, exposure, access, nearby commercial activity and insurance availability. For an apartment, the lender may also ask about the wider building, management arrangements and unusual title or maintenance obligations.
None of those points automatically makes a Portrush property difficult to mortgage. They simply make accurate information more important before an application is submitted.
A Mortgage Broker in Portrush can help you identify which details a lender is likely to ask about and whether specialist criteria may be relevant before you commit to a particular route.
Decide What the Property Is for Before Choosing the Mortgage
In a tourism-led location, intended use matters.
If you are buying a home to live in, the starting point is usually residential affordability, deposit, income, credit profile and the property itself. First-time buyers may also want to understand how lenders treat gifted deposits, variable income or smaller deposits. Connect Experts provides a dedicated search for first-time buyer brokers.
If the property will be let to short-stay guests, a normal residential mortgage may not be appropriate. Holiday-let lenders can assess projected seasonal income, personal affordability, occupancy assumptions and how the property will be managed. Portrush’s established visitor economy makes this distinction particularly relevant, so clients considering short-term accommodation can explore holiday-let mortgage brokers.
For longer-term letting, the route may instead involve first-time landlord mortgage advice, portfolio landlord mortgage advice or limited company buy-to-let advice, depending on your experience and ownership structure.
That distinction matters because the wrong mortgage type can create problems after completion. A Mortgage Broker in Portrush should understand how you intend to use the property before recommending a lender.
Rates Matter, but the Lowest Rate Is Not the Whole Decision
A headline rate can help with comparisons, but a mortgage only makes sense if you meet the lender’s criteria and the overall deal fits your plans.
Before choosing, compare the rate with arrangement fees, valuation costs, incentives, early repayment charges, the mortgage term, and the potential cost after any introductory period ends.
You can review current market pricing through UK mortgage rates before discussing suitable options with an adviser.
An adviser can then put those rates into context by considering the borrowing amount, deposit, income, property, and intended use, rather than treating the headline percentage as the decision on its own.
Remortgaging a Portrush Property
If your existing deal is approaching its end, start reviewing your options before you move onto a lender’s follow-on rate.
You may want to compare a product transfer with a full remortgage, particularly if the property value, your income or the way the property is used has changed.
For a residential or rental property, mortgage rate ending advice can help you find an adviser who understands the timing, fees and lender criteria involved.
If you genuinely need short-term finance, perhaps because an investment property needs work before longer-term lending becomes possible, short-term buy-to-let bridging finance may also be relevant.
Bridging is specialist borrowing and normally needs a clear repayment or refinance strategy before the loan is taken.
Protection Should Form Part of the Mortgage Conversation
The mortgage is only one part of the financial commitment.
When you speak to a Mortgage Broker in Portrush, it is worth discussing what could happen if illness, injury, death or loss of income affected your ability to maintain the mortgage. The appropriate solution depends on your circumstances and could include life cover, critical illness cover or income protection.
You can search for protection mortgage brokers who can discuss protection alongside your wider borrowing needs.
Protection policies have terms, conditions, exclusions and eligibility requirements. Advice should reflect your circumstances, existing cover and budget.
Speak to a Mortgage Broker in Portrush
The strongest mortgage decisions are often made before an application is sent.
That means being clear about the property, your income, your deposit, how the home will be used and what flexibility you may need later. In Portrush, that can be especially important where a home sits within a coastal setting or may have short-term letting potential.
Connect Experts helps you search for advisers by location, language, gender and area of expertise so you can choose an adviser whose experience fits the case.
The closest adviser isn’t necessarily the most suitable. The better question is whether the adviser understands the borrower, the property and the purpose behind the mortgage.